- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$6.36 BnMarket Estimate, 2026
$7.30 BnMarket Forecast, 2034
$22.03 BnCAGR, 2026–2034
14.8%Global Healthcare Data Storage Market Size, Growth, Trends & Forecast (2026–2034)
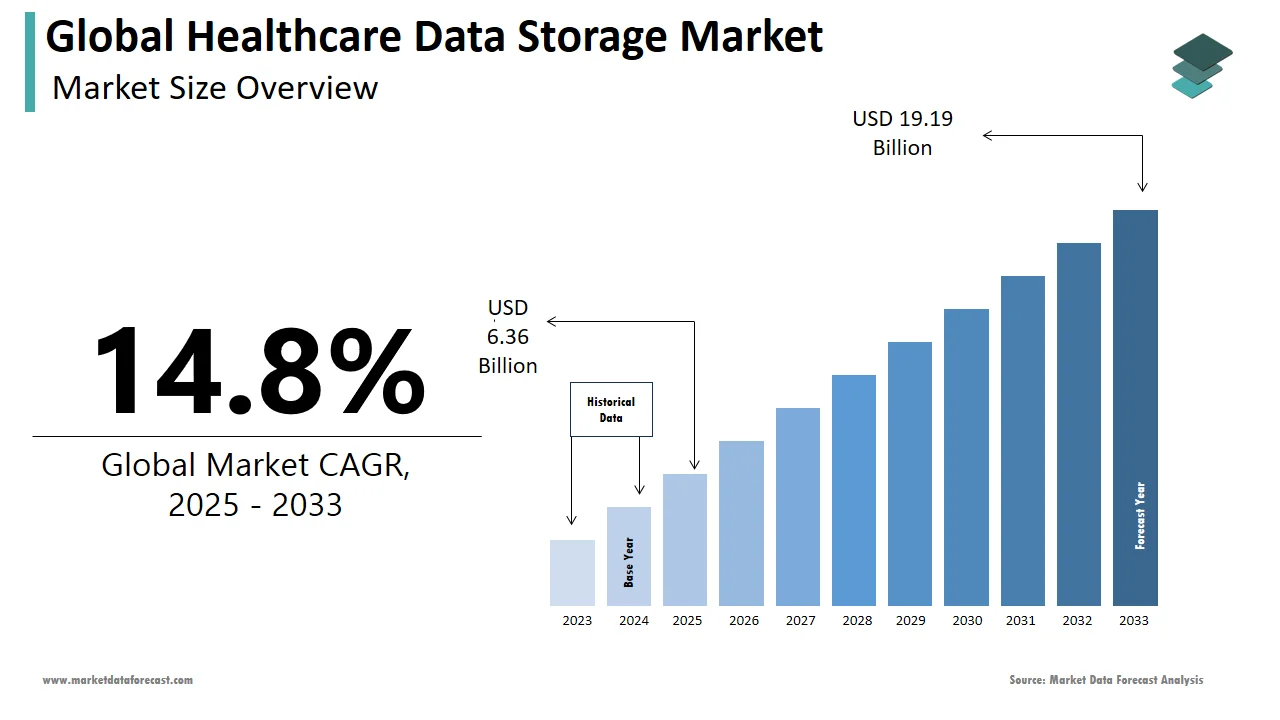
The global healthcare data storage market was valued at US$ 6.36 billion in 2025, is projected to grow from US$ 7.30 billion in 2026, and is expected to reach US$ 22.03 billion by 2034, registering a compound annual growth rate (CAGR) of 14.8% during the forecast period from 2026 to 2034. Driven by the massive explosion of clinical data, increasing IoT integration, and the rapid shift toward hybrid cloud and high-performance storage architectures, the market continues to experience robust expansion.
Key Executive Metrics (At-a-Glance)
- 2025 Base Valuation: US$ 6.36 Billion
- 2026 Current Valuation: US$ 7.30 Billion
- 2034 Forecast Valuation: US$ 22.03 Billion
- Compound Annual Growth Rate (CAGR): 14.8% (2026–2034)
- Dominant Deployment Segment: On-Premises & Hybrid (holding major shares due to data security control and bandwidth-intensive imaging needs)
- Fastest-Growing Deployment Segment: Cloud-Based Storage (expanding rapidly driven by cost efficiency, scalability, and remote access)
- Dominant Type Segment: Flash & Solid-State Storage (holding the biggest share in 2025 backed by higher capacity, speed, and decreasing costs)
- Dominant End-User Segment: Pharmaceutical & Biotechnology Companies, CROs, and CMOs (holding the greatest proportion due to intensive drug discovery data generation)
- Dominant Regional Market: North America (holding the leading global share supported by high unstructured data volumes and advanced health IT infrastructure)
Core Market Drivers
- Adoption of Hybrid Solutions: Growing preference for hybrid data storage models that keep bandwidth-intensive images on-premises while leveraging cloud for backup and disaster recovery.
- Big Data & IoT Proliferation: Escalating volumes of unstructured health data generated by smart hospitals, wearable devices, electronic health records (EHR), and diagnostic imaging.
- Cloud Infrastructure Evolution: Shift toward cost-effective, scalable cloud options supporting big data analytics and mobilized clinical workforces.
Primary Market Restraints & Challenges
- Legacy Integration & Interoperability: Difficulties in reassembling legacy systems, bulk migrating data across platforms, and ensuring seamless interoperability between cloud vendors.
- Compliance & Security Risks: Strict HIPAA and data privacy regulations, ongoing fears of data breaches, maintenance costs, and risks of downtime or latency.
Global Healthcare Data Storage Market Segmentation Breakdown
| Segment Category | Leading Sub-Segment (2025 Base) | Fastest-Growing Sub-Segment (2026–2034) |
|---|---|---|
| By Deployment | On-Premises (dominant segment offering strict data ownership, security, and multi-vendor architecture control) | Hybrid & Remote Cloud (fastest-growing deployment categories for scalable big data analytics) |
| By Architecture | Object & File Storage (dominant structural configurations for managing unstructured clinical and imaging files) | Object Storage (fastest-growing architecture optimized for massive cloud-scale unstructured data pools) |
| By Type | Flash & Solid-State Storage (dominant holding in 2025 due to superior speed, density, and price-performance ratio) | Flash & Solid-State Drives (fastest-growing type replacing traditional magnetic discs and tapes) |
| By Storage System | Storage Area Network (SAN) & Network-Attached Storage (NAS) (dominant enterprise infrastructure models) | Cloud-Integrated Network Storage (fastest-growing systems bridging local and off-site archives) |
| By End User | Pharmaceutical & Biotech Companies, CROs, and CMOs (dominant sector generating massive drug research data) | Hospitals, Clinics, and ASCs (fastest-growing end-users expanding digital health records and smart telemetry) |
| By Region | North America (dominant global market leader backed by high volumes of unstructured data and tech maturity) | Asia-Pacific (fastest-growing regional market driven by wearable device adoption and modernization in China, India, and Japan) |
Major Industry Players Profiled
Key enterprises shaping the global healthcare data storage market include IBM Corporation, Dell Technologies, Hewlett Packard Enterprise (HPE), Samsung Electronics Co., Ltd, NetApp, Huawei Technologies Co., Ltd, Hitachi, Ltd., Pure Storage, Fujitsu Limited, Toshiba Corporation, Western Digital, Cloudian, Scality, Drobo, and Tintri.
 Download Free Sample Report
Global Healthcare Data Storage Market Size
The global healthcare data storage market was worth US$ 6.36 billion in 2025 and is anticipated to reach a valuation of US$ 22.03 billion by 2034, from US$ 7.30 billion in 2026, and it is predicted to register a CAGR of 14.8% during the forecast period 2026 to 2034.
Data is priceless. As cliche as it may sound, data in healthcare is critical for providing up-to-date medical care and driving preventive healthcare in general. Healthcare data management is an unavoidable requirement for comprehensive medical care. Smart hospitals encourage using cutting-edge technologies to collect, analyze, and implement patient data. They combine IoT-based healthcare devices with traditional healthcare data collected via CT scans, MRIs, X-Ray reports, and other medical test reports to generate massive amounts of healthcare data. There are numerous benefits to incorporating public, private, and hybrid clouds into a company's long-term storage strategy. Healthcare organizations are building their IT infrastructures to be more flexible and scalable to meet the growing data demand. The volume of data collected and stored will increase as healthcare organizations embrace advanced health IT infrastructure technology. To protect patient data, organizations must ensure that their data is securely stored and accessible. Clinicians must also have access to data where and when needed for data storage to be successful. Analysts expect the healthcare cloud will become the preferred choice for healthcare back-office applications, backup and disaster recovery, revenue cycle management, and patient engagement in the coming years.
MARKET DRIVERS
The growing adoption of hybrid data storage solutions is one of the primary factors driving the growth of the global healthcare data storage market.
When scaling up or implementing a more advanced storage solution, most organizations opt for hybrid data storage. Organizations may choose to keep more bandwidth-intensive data, such as images, on-premises so that it can be accessed quickly. Hybrid data storage uses more than one cloud or server option to access data shared by two or more infrastructure hosting solutions. Data backup and recovery also benefit from hybrid solutions. Many cloud data storage solutions provide backup and recovery services and the ability to duplicate on-premises data into the cloud in the event of a disaster where the on-premises data is destroyed.
Growing healthcare cloud data storage options resulting from data storage system adoption are anticipated to accelerate the market’s growth rate.
Cloud data storage options have become popular in healthcare over the last few years as the stigma associated with hosting data off-site has faded. As more organizations adopt mobile apps, storing clinical data in the cloud provides users with more comprehensive access. Cloud data storage also saves organizations money by allowing them to buy more storage space as needed rather than investing in it upfront. Healthcare organizations are demanding more storage space for big data analytics and the increased volume of unstructured data required for analytics initiatives. According to an earlier SADA Systems survey, 89 percent of healthcare organizations use cloud-based health IT infrastructure, including cloud-based apps. Over the next few years, many providers are likely to increase their investment in these tools. Cost savings, scalability, speed, freed-up internal storage, a mobilized workforce, and improved user applications are all advantages of the cloud. According to another study, healthcare data will exceed 250,000 Petabytes by 2020. As a result, it is critical to store and manage this data effectively.
Additionally, factors such as the growing adoption of the Internet of Things (IoT), artificial intelligence, and the emergence of social media are further expected to promote the global healthcare data storage market. The quick and simple deployment of cloud storage solutions is rising, which is expected to favor the global healthcare data storage market. The demand for cloud computing has resulted in various cloud deployment models. These models use similar technology, but they differ in scalability, cost, performance, and privacy. Over the last decade, more businesses have relied on it for faster time to market, improved efficiency, and scalability. As part of their digital strategy, it assists them in achieving long-term digital goals. Alongside this, a growing number of initiatives and programs from various governments are expected to boost the market’s growth rate. Amid the COVID-19 pandemic, there is a growing demand for virtual healthcare worldwide.
MARKET RESTRAINTS
One of the most difficult data storage challenges that healthcare organizations face is putting legacy systems back together while integrating new systems into the infrastructure.
HIPAA compliance is also a concern for organizations considering cloud migration. Many organizations still hesitate to entrust EHRs and PHI to a third-party vendor, fearing that lax security will result in a data breach. In addition, many organizations cannot afford to migrate data in bulk from one storage system to another, so interoperability between cloud vendors is essential for a smooth transition. Additionally, Inadequate scalability, the larger infrastructure required, data security, increased maintenance costs, and risk of latency & downtime are expected to hamper the growth of the healthcare data storage market.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Covered | By Deployment, Architecture, Type, Storage System, End-user, and Region. |
| Various Analyses Covered | Global, Regional, and Country-Level Analysis, Segment-Level Analysis, Drivers, Restraints, Opportunities, Challenges; PESTLE Analysis; Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Regions Covered | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Market Leaders Profiled | IBM Corporation, Samsung Electronics Co., Ltd, Dell Technologies, Drobo, Huawei Technologies Co., Ltd, Cloudian, Hewlett Packard Enterprise (HPE), Fujitsu Limited, Scality, Hitachi, Ltd., Pure Storage, NetApp, Tintri, Toshiba Corporation, and Western Digital, and Others. |
SEGMENTAL ANALYSIS
By Deployment Insights
The on-premises segment is expected to account for most of the market share in the global healthcare data storage market during the forecast period. The most extensively used storage solutions on the market are on-premises systems. This deployment methodology may take advantage of multi-vendor architecture while reducing the risk of a data breach and external attacks. Users also control their deployment, backup, and data recovery systems because they own on-premises storage. These benefits are propelling the market for on-premises solutions forward.
By Type Insights
The flash and solid-state storage segment held the biggest market share in 2025 and is predicted to grow fastest throughout the forecast period. End-users increasingly adopt flash and solid-state drives due to their higher capacity and lower prices than magnetic discs.
By End-User Insights
The pharmaceutical and biotechnology companies, contract research organizations (CROs), and contract manufacturing organizations (CMOs) segment accounted for the greatest proportion of the market. This is because pharmaceutical and biotechnology businesses conduct intensive drug development research, which creates a large amount of data.
REGIONAL ANALYSIS
The North American healthcare data storage market accounted for most of the global market share in 2025, and this trend is likely to continue throughout the forecast period. This is due to the increased volume of unstructured healthcare data in the region and rapid technological advancements. As a result, demand for safe, dependable, and cost-effective storage infrastructure has increased in North America.
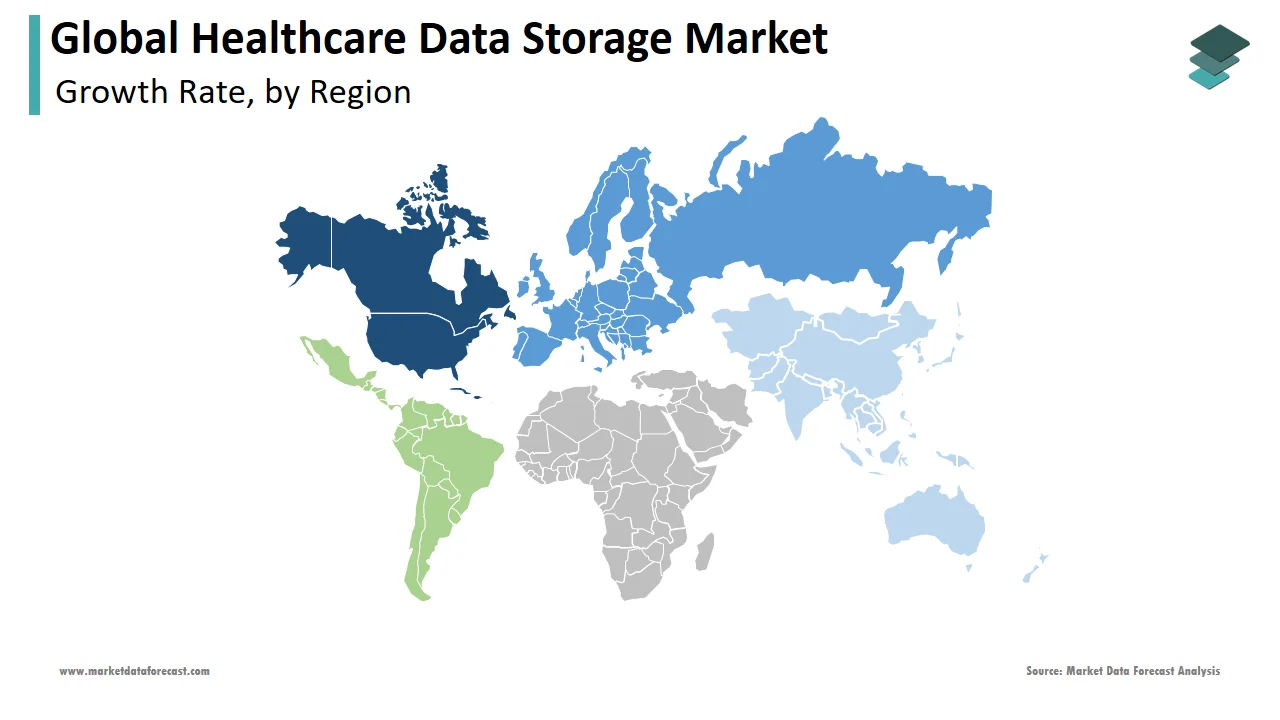
Due to several healthcare businesses providing diagnosis and treatment products, Europe holds the second-largest share in the global healthcare data storage market. It is expected to maintain its position during the forecast period, driving the healthcare data storage IT solutions market. In addition, the advent of a huge patient population suffering from arthritis, diabetes, and cancer is also fuelling market growth.
Because of rapid technological advancements and numerous growing nations, particularly China, India, and Japan, the APAC region's worldwide healthcare data storage market is expected to expand quickly throughout the forecast period. In addition, people are becoming more health conscious. As a result, they acquire healthcare wearables and smart gadgets, resulting in more data stored in the cloud and on-premises, resulting from market growth in this region.
KEY MARKET PLAYERS
Some of the companies that are playing a dominating role in the global healthcare data storage market include
- IBM Corporation
- Samsung Electronics Co., Ltd
- Dell Technologies
- Drobo
- Huawei Technologies Co., Ltd
- Cloudian
- Hewlett Packard Enterprise (HPE)
- Fujitsu Limited
- Scality
- Hitachi, Ltd.
- Pure Storage
- NetApp
- Tintri
- Toshiba Corporation
- Western Digital
GLOBAL HEALTHCARE DATA STORAGE MARKET NEWS
- Egnyte, Inc.'s unique security features and independent cloud file-sharing were combined into a single content solution in February 2020. In addition, with machine learning technologies and tiered storage, the services provide greater insights.
- In July 2020, HPE acquired SD-WAN pioneer Silver Peak, accelerating its Edge-to-Cloud strategy. Aruba's Edge Services Platform will benefit from Silver Peak's self-driving WAN to accelerate WAN transformation for cloud-first enterprises.
MARKET SEGMENTATION
This research report on the global healthcare data storage market has been segmented and sub-segmented based on deployment, architecture, type, storage system, end-user, and region.
By Deployment
- On-premises
- Remote
- Hybrid
By Architecture
- Object Storage
- File Storage
- Block Storage
By Type
- Magnetic Storage
- Magnetic Disks
- Magnetic Tapes
- Flash & Solid-state Storage
By Storage System
- Direct-attached Storage
- Network-attached Storage
- Storage Area Network
By End User
- Pharmaceutical & Biotechnology Companies, CROs, and CMOS
- Research Centers, Academic & Government Institutes, and Clinical Research Labs
- Hospitals, Clinics, and ASCs
- Diagnostic & Clinical Laboratories
- Other End Users
By Region
- North America
- Europe
- Asia-Pacific
- Latin America
- The Middle East and Africa