- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$934.22 BnMarket Estimate, 2026
$973.64 BnMarket Forecast, 2034
$1,355.22 BnCAGR, 2026–2034
4.22%Executive Summary: Hotel and Other Travel Accommodation Market
- Market Scope: Comprehensive global hotel and other travel accommodation industry analysis covering property types, operational segments, regional leadership frameworks, strategic developments, and competitive landscapes.
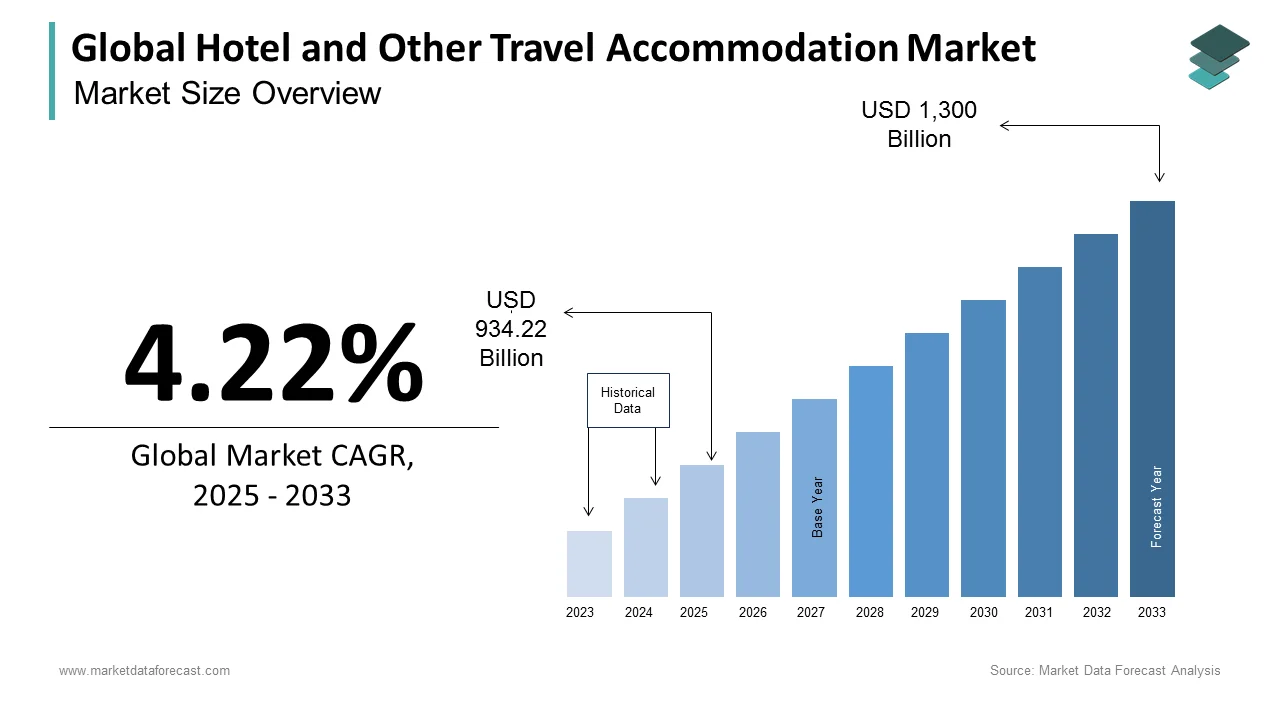
- Market Valuation: Valued at USD 934.22 billion (2025), estimated at USD 973.64 billion (2026), and projected to reach USD 1,355.22 billion by 2034, registering a steady CAGR of 4.22% (2026–2034).
- Primary Growth Drivers: Integration of guest-enhancing technologies (NFC, AI-driven personalization), rising social media influence, adoption of automated service robots and infrared sensors, personalized digital marketing, and growing demand for sustainable accommodations. Restraints include post-pandemic travel restrictions and variable cost pressures.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment / Region | Fastest-Growing / Resilient Segment |
|---|---|---|
| By Type | Hotel and motel segment (led the global market by type) | Budget hotels (demonstrating resilience through lower variable costs and extended-stay demand) |
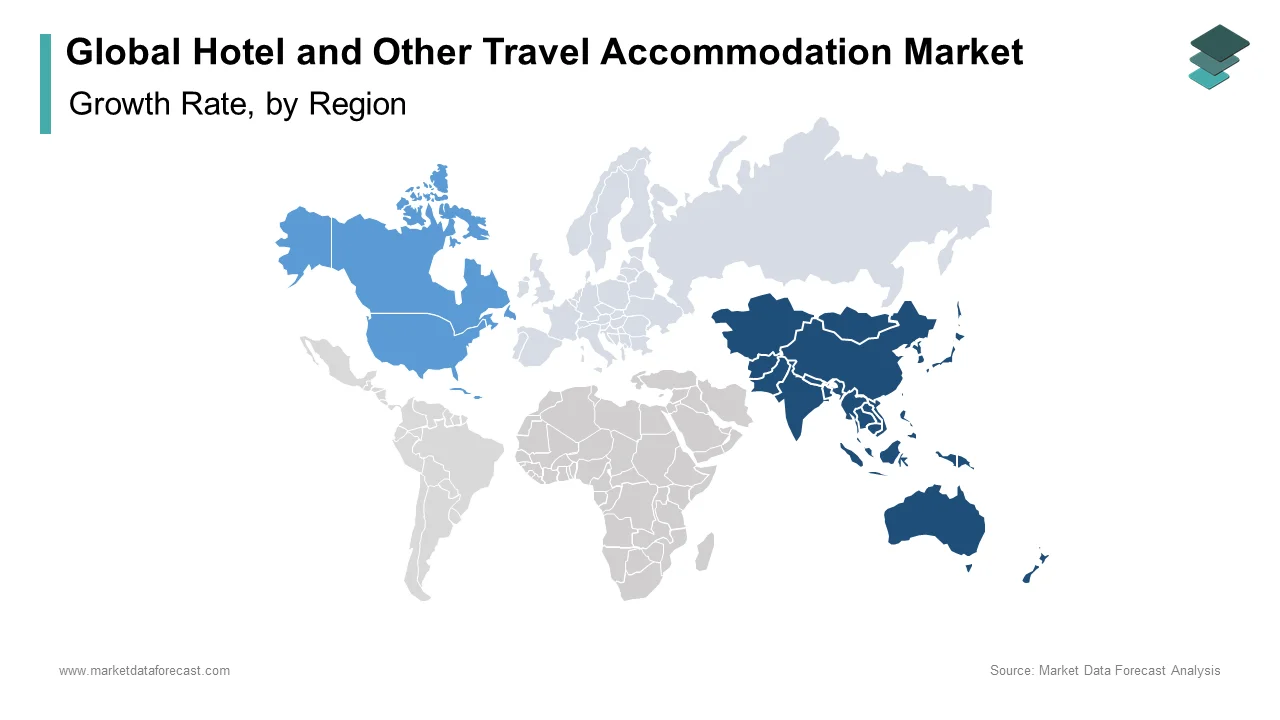
| By Region (Dominant) | Asia-Pacific (largest region, accounting for 36% of the industry) | North America (second-largest region with 27% market share) |
| By Region (Emerging) | Africa (smallest region but offering promising future opportunities) | Expanding tourism infrastructure and experience-led travel hubs |
Major Market Players & Market Structure
Market Structure: Highly competitive global hospitality landscape characterized by major international brand expansions, website personalization investments, alternative property introductions, and targeted flash-sale promotional strategies.
Key Companies: Marriott International, Hilton Worldwide, Wyndham Corporation, Hyatt Hotels Corporation, and Four Seasons Hotels & Resorts.
Global Hotel and Other Travel Accommodation Market Size
The global hotel and other travel accommodation market is expected to grow from US$ 934.22 billion in 2025 to reach a valuation of US$ 1,355.22 billion by 2034, from US$ 973.64 billion in 2026, at a compound annual growth rate (CAGR) of 4.22% between 2026 and 2034.
Hotel and other travel accommodations are commercial lodging establishments providing temporary shelter, including full-service hotels, limited-service properties, resorts, hostels, serviced apartments, and alternative short-term rentals. This sector serves as critical infrastructure that enables global mobility, business continuity, and cultural exchange, while representing significant fixed-asset investment with high operational leverage. According to the United Nations World Tourism Organization, international tourist arrivals reached 1.4 billion in 2024, creating foundational demand for approximately 35 million guest rooms worldwide across formal and informal accommodation categories. Unlike retail or digital services, accommodation supply is geographically fixed and capital intensive, requiring decades-long amortization horizons, making it uniquely sensitive to interest rate cycles, zoning regulations, and infrastructure development. This definition excludes permanent residential leasing, focusing exclusively on transient stays under 30 days where revenue management, dynamic pricing, and service differentiation create distinct economic dynamics shaped by seasonality, location specificity, and perishable inventory characteristics inherent to hospitality operations.
MARKET DRIVERS
Business Travel Recovery and Corporate Mobility Resurgence
Corporate mobility restructuring following pandemic disruptions has created sustained demand for accommodation tailored to hybrid work patterns, extended project assignments and distributed team collaboration rather than traditional overnight sales calls. The business travel recovery and corporate mobility resurgence is driving the growth of the hotel and other travel accommodation market. According to a 2025 report, approximately 68% of Fortune 500 companies revised travel policies to permit weekend extensions at employer expense recognizing the retention benefits of flexible mobility arrangements. Unlike pure leisure demand subject to consumer sentiment, volatility corporate accommodation demand correlates with GDP growth trade volumes and foreign direct investment creating predictable baseline occupancy. This normalization of blended travel creates durable demand floor supporting premium positioning for properties offering workspace connectivity and residential amenities aligned with evolving corporate mobility protocols.
Experiential Differentiation Commanding Premium Pricing Power
Travelers increasingly select accommodation based on unique experiential attributes rather than standardized room specifications, enabling differentiated properties to command rate premiums independent of star rating classifications. The experiential differentiation commanding premium pricing power is amplifying the growth of the hotel and other travel accommodation market. As per the McKinsey Consumer Sentiment Survey 2024, approximately 74% of travelers indicate willingness to pay 20% or more for accommodations offering authentic local immersion cultural programming or distinctive design narratives versus generic alternatives. According to the report, unique category listings including treehouses, yurts, and converted heritage buildings grew 48% year-on-year, indicating demand migration toward nonstandard accommodation formats. Unlike commoditized limited service segments where price dominates selection criteria, experiential properties compete on emotional resonance and social media shareability, creating defensible positioning against scale players. Millennial and Gen Z travelers prioritize Instagram-worthy design elements over traditional luxury markers when booking decisions are made. This aesthetic and narrative-driven consumption enables independent operators to capture a disproportionate share of high-margin segments without brand affiliation costs, transforming accommodation from functional shelter into a destination component justifying premium expenditure through identity alignment and memory creation value propositions.
MARKET RESTRAINTS
Labor Shortages Constraining Service Delivery Capacity
Chronic workforce deficits across housekeeping, food service, and front desk roles create hard capacity ceilings preventing operators from selling available inventory, despite robust demand signals. The labor shortages constraining service delivery capacity are hindering the growth of the hotel and other travel accommodation market. As per the study, the US hospitality sector faced 158000 unfilled positions in 2024, representing a 9% vacancy rate, with housekeeping experiencing a 23% shortfall, directly limiting room turnover capability during peak periods. EU accommodation workers report burnout symptoms driving attrition rates exceeding 30% annually and preventing institutional knowledge retention essential for consistent service quality, as per the reports. Unlike cyclical labor fluctuations, current shortages reflect structural demographic shifts, immigration restrictions, and post pandemic career reassessment, reducing the available workforce pool permanently. Automation provides partial mitigation but cannot replicate human interaction central to hospitality value proposition, particularly in upscale segments where service expectations remain uncompromised. This labor constraint creates an artificial supply ceiling capping revenue growth regardless of demand strength or pricing power.
Regulatory Restrictions on Short Term Rental Supply
Municipal governments worldwide increasingly impose caps, licensing requirements, and outright bans on short-term rentals, reducing available accommodation supply and fragmenting distribution channels. The regulatory restrictions on short term rental supply are additionally declining the growth of the hotel and other travel accommodation market. The European Parliament approved the Platform Work Directive in 2024, mandating data sharing and registration systems enabling enforcement against noncompliant hosts, creating compliance costs that eliminate marginal suppliers. According to the study, regulated European countries experienced a 28% decline in active short term rental listings in 2024 while hotel occupancy increased 9%, demonstrating substitution effects from regulatory supply restriction. Unlike hotels operating under established zoning frameworks, short term rentals face continuous policy uncertainty, preventing long term investment and professionalization of the segment. These regulatory interventions reflect political responses to housing affordability crises and neighborhood disruption concerns, creating structural headwinds for alternative accommodation growth regardless of consumer preference trends or platform innovation capabilities.
MARKET OPPORTUNITIES
Adaptive Reuse of Distressed Commercial Real Estate
The post-pandemic office vacancy and retail distress create unprecedented opportunity to convert underutilized commercial assets into accommodation, addressing both supply constraints and urban revitalization objectives simultaneously. The adaptive reuse of distressed commercial real estate is solely to promote new opportunities for the growth of the hotel and other travel accommodation market. As per Moody’s Analytics, US office vacancy reached 19.8% in Q4 2024, representing a record high, with 18 billion square feet of space classified as functionally obsolete, creating a massive conversion pipeline for hospitality developers. The adaptive reuse projects are new hotel openings in 2024, demonstrating accelerating developer recognition of conversion economics versus ground-up construction. Unlike greenfield development constrained by land availability and entitlement, conversions leverage existing infrastructure, zoning variances, and historic tax credits, improving return profiles in supply-constrained urban cores. Marriott and Hilton launched dedicated conversion brands in 2024 specifically targeting distressed commercial assets, signaling mainstream acceptance of this strategy. Municipalities actively incentivize conversions through expedited permitting and tax abatements, recognizing hospitality as a catalyst for downtown activation and tax base recovery. This convergence of distressed supply, sustainability imperatives, and policy support creates a decade-long opportunity cycle for operators capable of navigating conversion complexity.
Technology Enabled Operational Efficiency Gains
Artificial intelligence, automation, and IoT integration enable accommodation operators to reduce labor dependency, improve margin structures, and enhance guest personalization, simultaneously addressing multiple strategic priorities. The technology-enabled operational efficiency is also gaining traction with the growth of the hotel and other travel accommodation market. The automated check-in kiosks and mobile key deployment reduced front desk labor requirements by 35%, while improving guest satisfaction scores by 18 points through wait time elimination. The smart building technologies, including predictive maintenance and energy optimization, reduce utility costs by 22% annually, representing direct bottom-line impact in energy-intensive accommodation operations, as per a new survey. Unlike legacy property management systems requiring manual intervention, modern platforms enable autonomous operations, scaling service delivery without proportional staff increases. Guest data integration across touchpoints enables hyper-personalized experiences previously reserved for the ultra-luxury segment, democratizing customization through algorithmic insight rather than labor-intensive relationship management. Cloud native architectures reduce IT maintenance burdens, enabling small independent operators to access enterprise-grade capabilities previously cost-prohibitive. This technological leverage creates competitive advantage for early adopters while establishing new operational benchmarks that laggards must match to remain viable.
MARKET CHALLENGES
Debt Servicing Pressure From Elevated Interest Rates
Accommodation sector capital intensity combined with refinancing needs at elevated interest rates creates cash flow compression threatening solvency for leveraged operators and constraining new development pipelines. The data servicing pressure from elevated interest rates is expected to act as a major challenge for the growth of the hotel and other travel accommodation market. According to the study, cap rate expansion of 150 basis points since 2022 implies a 25% valuation decline for stabilized assets, forcing equity write-downs and impairing balance sheet capacity for reinvestment. Distressed asset sales increased 67% in 2024, indicating forced liquidation pressure as owners unable to refinance exit positions. Development feasibility has deteriorated with construction costs up 38% since 2020, while revenue projections remain uncertain, creating paralysis in the new supply pipeline. This capital market dislocation threatens operational continuity for marginal operators while rewarding well-capitalized players acquiring distressed assets at discounted valuations, reshaping the competitive landscape through financial stress rather than operational merit.
Climate Physical Risk Exposure and Insurance Retrenchment
The geographic concentration of accommodation assets in coastal resort destinations creates disproportionate exposure to climate physical risks, while insurance market contraction eliminates traditional risk transfer mechanisms. The climate physical risk exposure and insurance retrenchment is additionally to degrade the growth of the hotel and other travel accommodation market. According to the study, property insurance premiums for coastal hotels increased 45% in 2024, while coverage limits decreased 30% forcing operators to retain larger uninsured exposures or abandon vulnerable locations entirely. Unlike diversified portfolios, accommodation assets are immobile and irreplaceable creating binary loss scenarios where single events can eliminate entire property value. Florida and California insurers have withdrawn from high-risk zones leaving state backed plans of last resort as only option with inadequate capacity for commercial scale operations. Adaptation investments including elevation floodproofing and fire suppression require capital expenditure averaging 18% of replacement cost, according to the study.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Covered | By Type, Mode Of Booking, Application, Price Point, OwnerShip, and Region. |
| Various Analyses Covered | Global, Regional, and Country-Level Analysis, Segment-Level Analysis, Drivers, Restraints, Opportunities, Challenges; PESTLE Analysis; Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Countries Covered |
|
| Market Leaders Profiled | Marriott International, Hilton Worldwide, Wyndham Corporation, Hyatt Hotels Corporation, Four Seasons Hotels & Resorts, Airbnb Inc, and Others. |
SEGMENTAL ANALYSIS
By Type Insights
The hotel and motel segment was the largest by accounting for a significant share of the hotel and other travel accommodation market in 2025 due to standardized service delivery and extensive global distribution network integration that alternative lodging types cannot match. According to the study, branded hotels accounted for 74% of total global room supply in 2025, providing consistent quality benchmarks that reduce consumer decision risk significantly. Loyalty program ecosystems create powerful retention mechanisms with Marriott Bonvoy and Hilton Honors collectively exceeding 400 million members worldwide, according to the study. Digital infrastructure maturity enables real time inventory synchronization across hundreds of online travel agencies and global distribution systems maximizing occupancy optimization capabilities. Scale economies allow significant capital investment in sustainability certifications and smart room technologies that independent bed and breakfasts cannot afford individually. This structural advantage sustains dominance despite growing niche competition from alternative accommodation providers seeking personalized experiences.
The bed and breakfast accommodations segment is likely to grow at an anticipated CAGR of 18.7% throughout the forecast period, with the authentic experience demand and digital platform democratization. Phocuswright research indicates that millennials specifically seek locally owned accommodations to support community economies and gain insider destination knowledge unavailable through conventional hotels. Digital marketplace platforms have dramatically reduced marketing barriers, enabling small operators to reach global audiences without expensive direct booking engine investments or brand affiliation fees. Rural B&B occupancy rates increased between 2023 and 2025, as remote work trends extended average stay durations beyond traditional weekend visits. Sustainability credentials inherent in adaptive reuse of historic buildings resonate strongly with eco-conscious consumers avoiding new construction environmental impacts. Government tourism diversification programs in countries like Japan and Portugal provide subsidies for the conversion of traditional ryokan and quintas, preserving cultural heritage while creating economic opportunities. Personalized host interactions fulfill post pandemic desire for human connection that automated hotel services cannot replicate authentically.
By Application Insights
The hospitality segment held a prominent share of the hotel and other travel accommodation market in 2025 due to universal demand across leisure, business, and transit travel purposes. Unlike specialized medical or aerospace applications requiring specific facilities and regulatory approvals, hospitality serves fundamental human needs during any journey regardless of purpose or duration. UNWTO data confirms international tourist arrivals reached 1.5 billion in 2025, with each visitor requiring overnight accommodation creating massive baseline demand volume. Standardization of safety, hygiene, and service protocols enables cross-border recognition, reducing traveler anxiety about unknown destinations compared to complex medical procedures requiring extensive pre-visit research. Hotel loyalty programs generate proprietary first-party data, enabling sophisticated personalization and direct relationship management, reducing third-party platform dependency. Infrastructure density ensures availability even in secondary markets where specialized medical tourism facilities remain concentrated in major urban centers. Recurring revenue streams from business travelers averaging 12 annual stays per GBTA statistics provide predictable cash flows supporting continuous reinvestment cycles that niche segments cannot sustain economically.
The medical tourism segment is expected to witness the fastest CAGR of 26.4% throughout the forecast period, with the healthcare cost disparities and specialized treatment accessibility abroad. Rising domestic healthcare costs drive patients from developed nations to seek affordable alternatives, with procedures like joint replacement costing 75% less in Thailand or Mexico compared to United States prices, according to research. Digital platforms specializing in medical travel facilitate complex decision-making through verified provider directories, outcome databases, and virtual consultations, reducing information asymmetry historically deterring cross-border care seeking. UK patients now consider overseas options due to National Health Service backlogs exceeding 20 months for elective surgeries, accelerating adoption of integrated medical hospitality packages. Accreditation bodies like Joint Commission International certified over 1400 facilities globally by 2025, creating trust infrastructure essential for high-stakes purchasing decisions involving health outcomes. Postoperative recovery requires extended accommodation stays averaging 14 days per case, generating higher revenue per guest than typical leisure visits.
REGIONAL ANALYSIS
North America Hotel and Other Travel Accommodation Market Analysis
North America was the top performer in the global hotel and other travel accommodation market by capturing 36.5% of share in 2025, with mature branded chain penetration and advanced technological adoption setting industry standards worldwide. Canada demonstrates exceptional cross-border integration with Statistics Canada reporting 68% of international visitors originate from the United States, facilitated by seamless loyalty program reciprocity and shared distribution infrastructure. Labor shortages accelerated automation adoption with properties implementing mobile key and self-service kiosks permanently transforming operational models. Regulatory frameworks like ADA compliance create uniform accessibility standards, enhancing inclusivity, while increasing renovation costs for older properties.
Europe Hotel and Other Travel Accommodation Market Analysis
Europe hotel and other travel accommodation market was positioned next, holding 22.3% of share in 2025, with regulatory sophistication, heritage preservation mandates, and multilingual operational complexity serving diverse linguistic communities. Cross-border Schengen travel generates 1.3 billion overnight stays annually, creating massive intra-regional transaction flows supported by harmonized consumer protection regulations reducing friction. Short term rental regulation intensifies with cities like Barcelona and Amsterdam imposing strict licensing requirements, redirecting demand toward licensed hotels and registered B&Bs, improving tax compliance. Historic building adaptation creates unique inventory, differentiating European offerings from newer global competitors, though renovation costs are higher than new construction, as per research. Public sector digital transformation initiatives enable single sign-on across government tourism services, reducing administrative burdens for small operators navigating complex bureaucratic requirements.
Asia Pacific Hotel and Other Travel Accommodation Market Analysis
Asia Pacific hotel and other travel accommodation market growth is likely to grow with rising middle-class mobility, mobile-first consumer behavior, and super app ecosystem integration. India witnessed 71% year-on-year growth in online accommodation bookings reaching 32 billion dollars in 2025, as affordable smartphone penetration and vernacular language localization drive inclusion, according to the study. Japan’s aging population creates unique demand for senior-friendly interfaces, with JTB Corporation reporting 45% of travelers over 65 now book independently through simplified applications. ASEAN mutual recognition arrangements facilitate cross-border hospitality employment supported by digital credential verification systems addressing labor shortages. Rural tourism digitization connects 22000 village enterprises to global markets through government-subsidized onboarding programs promoting inclusive development.
Latin America Hotel and Other Travel Accommodation Market Analysis
Latin America hotel and other travel accommodation market growth is anticipated to grow with resilience and adaptation, despite infrastructural constraints, currency volatility, and security concerns affecting traveler confidence. Mercado Libre’s travel vertical grew 94% in 2025, leveraging existing e-commerce trust and installment payment infrastructure, overcoming credit card penetration limitations, as per company disclosures. Chile and Peru lead sustainable accommodation digitization with 68% of protected areas offering online reservation systems, reducing overtourism pressures according to the study. Mobile money solutions like Pix in Brazil processed 4.8 billion accommodation transactions in 2025, enabling instant settlements for small vendors previously excluded from the formal digital economy.
Middle East and Africa Hotel and Other Travel Accommodation Market Analysis
Middle East and Africa hotel and other travel accommodation market growth is driven by the demonstrate divergent trajectories, with Gulf states achieving world-class luxury maturity, while sub-Saharan Africa pursues mobile-centric inclusion strategies. Nigeria’s burgeoning middle class drives 59% annual growth in online bookings per PwC Africa Hospitality Outlook despite foreign exchange restrictions limiting outbound travel. Egypt’s national e-visa platform processed 9 million applications in 2025, reducing entry friction and improving satisfaction scores by 36 points per Ministry statistics. Rwanda’s smart destination initiative integrates IoT sensors across national parks, creating premium positioning justifying higher price points.
COMPETITIVE LANDSCAPE
The competitive landscape exhibits intense rivalry between established hotel chains and alternative accommodation platforms, reshaping industry dynamics fundamentally through divergent value propositions. Traditional operators leverage standardized service quality, safety protocols, and loyalty programs to retain corporate and risk-averse leisure travelers seeking predictability. Peer-to-peer platforms compete on authenticity, unique inventory, and price flexibility, attracting experience-seeking demographics willing to trade consistency for cultural immersion. Vertical specialization creates fragmented niches, where boutique operators outperform generalists in specific segments like wellness or heritage tourism through deeper expertise. Price transparency enabled by comparison engines compresses margins, forcing differentiation through superior service, exclusive amenities, or technological innovation rather than cost leadership alone. Consolidation accelerates as larger entities acquire innovative startups to absorb capabilities and neutralize potential threats before achieving scale independently. Consumer trust remains paramount, with hygiene breaches or safety incidents causing irreversible brand damage in an industry built entirely on confidence and reliability expectations.
KEY MARKET PLAYERS
The leading companies operating in the global hotel and other travel accommodation market include:
- Marriott International
- Hilton Worldwide
- Wyndham Corporation
- Hyatt Hotels Corporation
- Four Seasons Hotels & Resorts
- Airbnb Inc.
TOP PLAYERS IN THE MARKET
- Marriott International operates as a global hospitality leader managing diverse accommodation brands across luxury, premium, and select segments worldwide. The company contributes significantly to industry standards through comprehensive sustainability programs and digital innovation that enhance guest experiences while reducing environmental impact. Recent strategic initiatives include expanding their Homes and Villas portfolio to capture extended stay demand from remote workers seeking residential-style amenities with hotel services. They launched enhanced mobile app features enabling seamless contactless journeys and personalized service requests, improving operational efficiency. Their loyalty program integration across brands strengthens direct relationships, reducing third-party dependency and increasing lifetime customer value through unified reward ecosystems globally.
- Hilton Worldwide Holdings maintains extensive global presence through franchised and managed properties serving leisure business and group travel segments across multiple price points. The organization contributes to market development through proprietary technology platforms that optimize revenue management and guest personalization at scale. Recently, they accelerated digital key adoption across portfolios, enabling frictionless arrival experiences and reducing front desk labor requirements permanently. Strategic partnerships with entertainment and credit card companies expand loyalty earning opportunities beyond stays, increasing engagement frequency. Their sustainability commitments include eliminating single-use plastics and achieving net zero operations by 2050, aligning with evolving traveler values and regulatory expectations worldwide.
- Airbnb transformed accommodation markets by creating peer-to-peer marketplaces connecting individual hosts with travelers seeking authentic local experiences beyond traditional hotel offerings. The platform contributes to economic distribution by enabling property owners to monetize unused space while providing guests unique cultural immersion opportunities globally. Recent actions include introducing AI-powered listing enhancement tools helping hosts optimize pricing, presentation, and communication quality automatically. They expanded long-term stay categories, capturing remote work demand segments previously underserved by conventional short-term rental models. Host education initiatives improve service consistency and regulatory compliance, strengthening trust infrastructure essential for sustainable community-driven marketplace growth across diverse international jurisdictions.
TOP STRATEGIES USED BY KEY MARKET PARTICIPANTS
Key players prioritize technological integration to enhance guest personalization and operational efficiency across digital touchpoints continuously. Companies invest substantially in artificial intelligence for dynamic pricing optimization and predictive maintenance, reducing costs while improving satisfaction scores. Sustainability certification programs differentiate offerings as environmentally conscious travelers increasingly factor ecological impact into booking decisions, requiring verifiable transparency mechanisms. Direct booking incentives reduce intermediary commissions, improving margins, while building proprietary customer databases for targeted marketing campaigns. Loyalty ecosystem expansion increases lifetime value through experiential rewards beyond room nights, fostering emotional connections. Mobile-first design ensures seamless functionality, capturing spontaneous micro-moment bookings during travel inspiration phases. Strategic acquisitions of niche technology startups accelerate capability development in areas like virtual reality previews and blockchain verification without lengthy internal research cycles. Labor optimization through automation addresses chronic staffing shortages, while maintaining service quality standards consistently. Content commerce integration transforms social media inspiration into immediate action, shortening purchase cycles significantly. Regulatory technology investments ensure compliance across fragmented jurisdictions, minimizing operational risks in volatile geopolitical environments, affecting cross-border travel flows.
MARKET SEGMENTATION
This global hotel and other travel accommodation market research report has been segmented and sub-segmented based on type, mode of booking, application, price point, ownership, and region.
By Type
- Hotel and Motel
- Casino Hotels
- Bed and Breakfast Accommodations
- All Other Traveller Accommodations
By Mode of Booking
- Online Bookings
- Direct Bookings
- Others
By Application
- Tourist Accommodation (Leisure)
- Hospitality
- Medical Tourism
- Official Business (Professional)
By Price Point
- Economy
- Mid-range
- Luxury
By Ownership
- Chained
- Standalone
By Region
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa