- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$102.94 BnMarket Estimate, 2026
$136.55 BnMarket Forecast, 2034
$1,309.03 BnCAGR, 2026–2034
32.65%Executive Summary: Global Modular Data Centers Market
- Market Scope: Global analysis of the modular data center sector, detailing containerized and portable units, energy efficiency frameworks, edge computing deployments, and regional growth trajectories.
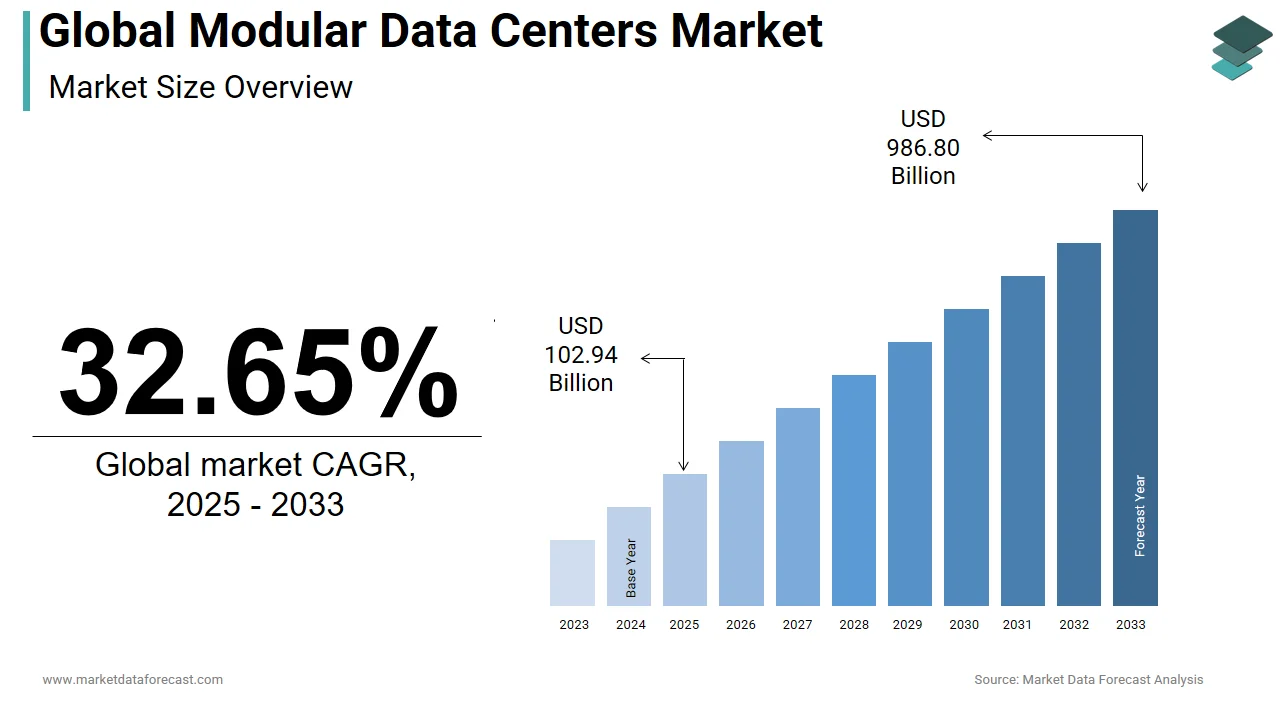
- Market Valuation: Valued at USD 102.94 billion in 2025, reaching USD 136.55 billion in 2026, and projected to surge to USD 1,309.03 billion by 2034, growing at a remarkable CAGR of 32.65% from 2026-2034.
- Primary Growth Drivers: Rapid deployment requirements accelerating infrastructure expansion, rising energy efficiency and sustainability goals, and the exponential expansion of edge computing.
Key Market Segment Metrics
| Category | Leading Segment (Base Position) | Fastest-Growing / High-Growth Segment |
|---|---|---|
| By Type | Containerized Data Centers (accounted for 61.6% share in 2025, driven by self-contained infrastructure and rapid deployment) | Portable Data Centers (growing at a notable 13.3% CAGR, fueled by mobile computing needs in emergency/temporary scenarios) |
| By Size | Large Data Centers (led with 54.6% share in 2025, supported by hyperscale operators and massive cloud scaling requirements) | Mid-Sized Data Centers (projected at a 15.4% CAGR, driven by hybrid cloud adoption and regional enterprise digital transformation) |
| By End-User Industry | IT and Telecommunications (occupied 46.4% share in 2025, propelled by data traffic growth, 5G rollouts, and edge networks) | Healthcare (predicted to expand at a 16.4% CAGR, driven by electronic health records, telemedicine, and compliance needs) |
| By Region | North America (held 40.4% share in 2025, backed by advanced digital infrastructure, hyperscalers, and stringent PUE regulations) | Asia-Pacific (fastest-growing region at a 16.8% CAGR, fueled by rapid internet penetration, smart cities, and e-commerce surges) |
Major Market Players & Industry Landscape
Market Structure: Highly competitive global marketplace featuring specialized modular infrastructure providers and multinational technology giants focusing on energy-optimized prefabricated designs.
Key Companies: Rittal GmbH & Co. KG, Cisco Systems, Inc., IBM Corporation, Huawei Technologies Co., Ltd., Commscope, Inc., Baselayer Technology, LLC, Schneider Electric SE, The Hewlett Packard Enterprise Company, Dell, Inc., SGI Corporation, IO Data Centers LLC, Flexenclosure AB, BladeRoom Group Ltd., Cannon Technologies, Eaton Corporation, Vertiv Co., and STULZ GmbH.
 Download Free Sample Report
Global Modular Data Centers Market Size
The global modular data center market was valued at USD 102.94 billion in 2025. The global modular data center market is predicted to reach USD 136.55 billion in 2026 and USD 1,309.03 billion by 2034, growing at a CAGR of 32.65% during the forecast period.
The modular data centers market comprises prefabricated and standardized computing infrastructure units that can be rapidly deployed and scaled to meet specific processing needs. These systems integrate power, cooling, networking, and security components into single- or multi-containerized modules, offering a flexible alternative to traditional brick-and-mortar facilities. According to the International Energy Agency, data centers currently consume approximately 1% of global electricity demand, a figure projected to rise significantly with the expansion of digital services. Additionally, according to the Uptime Institute, over 60% of enterprise IT leaders prioritize speed of deployment when selecting new infrastructure solutions to support agile business operations. These operational imperatives drive organizations toward modular architectures that reduce construction timelines from years to months. The market serves diverse sectors, including telecommunications, healthcare, finance, and government entities, requiring edge computing capabilities and disaster recovery sites. As cloud computing and artificial intelligence workloads intensify, the need for distributed and efficient processing power becomes critical. Modular data centers provide the scalability and energy efficiency necessary to handle these evolving demands while minimizing capital expenditure. This shift toward decentralized and rapid deployment models ensures the market remains central to modern digital infrastructure strategies globally.
MARKET DRIVERS
Rapid Deployment Requirements Accelerate Infrastructure Expansion
Rapid deployment requirements accelerate infrastructure expansion within the modular data centers market by addressing the urgent need for scalable computing resources in dynamic business environments. Traditional data center construction often takes two to three years to complete due to complex permitting, zoning, and building processes, which delays time-to-market for digital services. According to the Uptime Institute, modular data centers can be deployed in as little as 12 to 16 weeks, allowing organizations to respond quickly to sudden spikes in data demand. This speed is crucial for industries such as e-commerce and media streaming, where latency and availability directly impact revenue. Furthermore, according to the Global Data Center Association, the ability to scale capacity incrementally reduces upfront capital risk and aligns investment with actual usage patterns. Companies can add modules as needed rather than over-provisioning for future growth, which optimizes financial resources. The plug-and-play nature of modular units simplifies installation and integration with existing IT systems. This agility supports digital transformation initiatives by ensuring that infrastructure keeps pace with software development cycles. As businesses increasingly adopt hybrid cloud strategies, the demand for fast-track infrastructure solutions continues to grow. The competitive advantage gained through quicker service launches reinforces the preference for modular architectures.
Energy Efficiency and Sustainability Goals Drive Adoption
Energy efficiency and sustainability goals drive adoption within the modular data centers market by enabling organizations to meet stringent environmental regulations and corporate social responsibility targets. Modular units are designed with advanced cooling technologies, such as liquid immersion and hot aisle containment, which significantly reduce power consumption compared to legacy facilities. According to the International Renewable Energy Agency, improving data center energy efficiency is essential for achieving global climate goals as the sector’s carbon footprint expands with digitalization. Modular designs often achieve Power Usage Effectiveness ratings below 1.2, whereas traditional centers typically operate between 1.5 and 2.0. This superior efficiency translates to lower operational costs and reduced greenhouse gas emissions. Additionally, according to the European Commission, large enterprises disclose their environmental impact, including energy usage from IT infrastructure, prompting a shift toward greener solutions. Modular data centers facilitate the integration of renewable energy sources, such as solar and wind, due to their smaller footprint and flexible location options. Manufacturers are increasingly using recycled materials and designing for end-of-life recyclability, further enhancing sustainability credentials. The ability to monitor and optimize energy usage in real time through embedded sensors supports continuous improvement. These environmental benefits make modular data centers an attractive choice for eco-conscious organizations.
MARKET RESTRAINTS
High Initial Capital Costs Limit Accessibility for SMEs
High initial capital costs limit accessibility for small and medium-sized enterprises within the modular data centers market by creating financial barriers to entry. Although modular solutions offer long-term savings, the upfront expense of purchasing fully equipped containers with integrated power and cooling systems can be prohibitive. According to the World Bank, access to affordable financing remains a significant challenge for smaller businesses in developing economies where interest rates are high. A single modular unit can cost hundreds of thousands of dollars, excluding land acquisition and site preparation expenses. This substantial investment discourages smaller organizations from adopting modular architectures despite their operational benefits. Furthermore, the total cost of ownership includes ongoing maintenance, software licensing, and specialized technical support, which adds to the financial burden. According to the International Finance Corporation, many SMEs lack the credit history or collateral required to secure loans for such large capital projects. Consequently, these businesses may rely on public cloud services instead of owning physical infrastructure, limiting the market potential for modular hardware vendors. The perceived risk of technological obsolescence also makes companies hesitant to commit significant funds. Without flexible leasing options or government subsidies, the high entry cost restricts market expansion among smaller players.
Security and Physical Vulnerability Concerns Hinder Trust
Security and physical vulnerability concerns hinder the modular data centers market expansion by raising doubts about the safety of data in decentralized and potentially remote locations. Unlike traditional fortified data centers, modular units are often deployed in less secure environments, such as industrial parks or rural areas, making them susceptible to physical tampering or theft. According to the Cybersecurity and Infrastructure Security Agency, physical security breaches can lead to significant data loss and operational disruption, particularly if surveillance and access controls are inadequate. Modular designs may lack the robust perimeter defenses and biometric access systems found in large tier-four facilities. Additionally, the transportable nature of these units raises concerns about supply chain integrity and potential interception during transit. According to the Information Systems Audit and Control Association, decentralized infrastructure increases the attack surface for cyber threats, requiring comprehensive security protocols at each node. Ensuring consistent security standards across multiple modular sites is complex and resource-intensive. Organizations handling sensitive data, such as healthcare records or financial transactions, may hesitate to use modular solutions due to compliance risks. The need for enhanced encryption and remote monitoring capabilities adds to the complexity and cost. Until security perceptions improve, adoption in highly regulated sectors may remain limited.
MARKET OPPORTUNITIES
Edge Computing Expansion Creates New Deployment Scenarios
Edge computing expansion creates new deployment scenarios within the Modular Data Centers Market by necessitating processing power closer to data sources to reduce latency. The proliferation of Internet of Things devices, autonomous vehicles, and smart city applications generates massive amounts of data that require real-time analysis. According to the GSMA, 5G networks enable billions of connected devices, driving the need for distributed computing infrastructure at the network edge. Modular data centers are ideal for edge deployments due to their compact size and ability to operate in harsh environmental conditions. They can be installed at cell towers, factory floors, or retail locations, providing localized processing capabilities. This proximity reduces bandwidth costs and improves application performance for latency-sensitive tasks. According to the Telecommunications Industry Association, edge computing accounts for a significant portion of future data processing workloads, requiring scalable and flexible infrastructure. Modular units allow service providers to rapidly expand their edge footprint without constructing permanent buildings. The ability to standardize hardware across multiple edge locations simplifies management and maintenance. As industries digitize their operations, the demand for edge-capable modular data centers will surge. This trend opens lucrative markets in telecommunications, manufacturing, and logistics sectors.
Disaster Recovery and Business Continuity Solutions Offer Growth Potential
Disaster recovery and business continuity solutions offer growth potential within the modular data centers market by providing resilient and rapidly deployable backup infrastructure. Natural disasters, cyberattacks, and power outages can cripple traditional data centers, leading to significant financial losses and reputational damage. According to the Federal Emergency Management Agency, 40% of businesses do not reopen after a major disaster, highlighting the critical need for robust recovery plans. Modular data centers can be pre-configured and stored off-site, allowing for quick activation when primary facilities fail. Their self-contained design ensures independence from local grid failures if equipped with backup power sources. According to the Disaster Recovery Institute International, regular testing of recovery systems is easier with modular units that can be spun up temporarily. Organizations in hurricane-prone or earthquake-susceptible regions are increasingly investing in modular backup sites to ensure operational continuity. The flexibility to relocate these units post-disaster provides additional resilience. Insurance companies are beginning to recognize modular data centers as effective risk mitigation tools, potentially lowering premiums for insured entities. This strategic value proposition drives adoption among enterprises prioritizing uptime and data integrity. The growing frequency of extreme weather events further underscores the importance of flexible recovery solutions.
MARKET CHALLENGES
Standardization and Interoperability Issues Complicate Integration
Standardization and interoperability issues complicate integration within the modular data centers market by creating compatibility challenges between different vendors and existing IT ecosystems. The lack of universal standards for module dimensions, connectivity interfaces, and management software hinders seamless integration with legacy infrastructure. According to the Institute of Electrical and Electronics Engineers, proprietary protocols used by various manufacturers can lead to vendor lock-in and increased complexity in multi-vendor environments. Organizations attempting to mix and match modules from different suppliers often face technical hurdles related to power distribution and cooling alignment. This fragmentation increases the cost and time required for system integration and troubleshooting. Additionally, the absence of standardized security frameworks for modular units raises concerns about consistent protection across heterogeneous setups. The Open Compute Project aims to address some of these issues, but widespread adoption of open standards remains slow. Enterprises must invest in custom middleware or gateways to bridge compatibility gaps, which adds to operational overhead. The lack of interoperability also limits the secondary market for used modules, as buyers may struggle to integrate them into existing systems. Until industry-wide standards are established, integration challenges will persist. This uncertainty discourages some organizations from committing to modular architectures.
Skilled Workforce Shortage Impedes Effective Management
Skilled workforce shortage impedes effective management within the modular data centers market by limiting the availability of personnel trained in specialized modular technologies. Managing modular data centers requires expertise in both traditional IT infrastructure and unique aspects of prefabricated systems, such as integrated cooling and power management. According to the CompTIA Technology Industry Council, the global IT workforce faces a deficit of millions of skilled professionals, with particular shortages in data center operations and maintenance. Modular units often employ proprietary technologies that require specific training, which is not widely available in standard educational curricula. This skills gap leads to longer resolution times for technical issues and increased reliance on vendor support services. The high turnover rate in the IT sector exacerbates the problem as experienced staff move to other opportunities. Organizations must invest heavily in training programs to upskill existing employees, which adds to operational costs. The complexity of managing distributed modular sites further strains limited human resources. Remote monitoring tools help alleviate some burdens but cannot replace hands-on expertise for physical maintenance. The shortage of qualified technicians poses a significant risk to operational reliability. Addressing this human capital challenge is essential for sustainable market growth.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Covered | By Type, Size, Industries, and Region. |
| Various Analyses Covered | Global, Regional, and Country-Level Analysis, Segment-Level Analysis, Drivers, Restraints, Opportunities, Challenges; PESTLE Analysis; Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Regions Covered | North America, Europe, APAC, Latin America, Middle East & Africa |
| Market Leaders Profiled | Rittal GmbH & Co. KG, Cisco Systems, Inc., IBM Corporation, Huawei Technologies Co., Ltd., Commscope, Inc., Baselayer Technology, LLC, Schneider Electric SE, The Hewlett Packard Enterprise Company, Dell, Inc., SGI Corporation, IO Data Centers LLC, Flexenclosure AB, BladeRoom Group Ltd., Cannon Technologies, Eaton Corporation, Vertiv Co., STULZ GmbH, and Others. |
SEGMENTAL ANALYSIS
By Type Insights
The containerized data centers segment accounted for 61.6% of the global modular data center market share in 2025 due to their ability to provide complete self-contained infrastructure with minimal site preparation. These units integrate servers, storage, networking, power, and cooling into standard shipping containers, allowing for rapid deployment in diverse environments. According to the Uptime Institute, containerized solutions can reduce deployment time by up to 50% compared to traditional brick-and-mortar facilities, which is critical for businesses needing immediate capacity. This speed-to-market advantage drives adoption among hyperscalers and enterprises facing sudden demand spikes. Furthermore, according to the Green Grid Association, containerized designs often achieve superior Power Usage Effectiveness ratings through optimized airflow and integrated cooling systems. This energy efficiency aligns with corporate sustainability goals and reduces operational expenditures significantly. The standardized form factor of shipping containers facilitates easy transportation via rail, road, or sea, enabling global scalability. Companies can deploy these units in remote locations where building permanent structures is impractical or cost-prohibitive. The plug-and-play nature simplifies maintenance and upgrades as entire modules can be swapped out quickly. Regulatory compliance is easier to manage since manufacturers pre-certify units for safety and performance standards. The robustness of containerized units against environmental factors, such as dust, humidity, and temperature extremes, ensures reliability in harsh conditions. These operational benefits solidify the dominance of containerized data centers in the global modular data center market.
However, the portable data centers segment is estimated to register a notable CAGR of 13.3% over the forecast period in the global modular data center market owing to the rising need for mobile computing capabilities in temporary or emergency scenarios. These compact units are designed for high mobility and quick setup, making them ideal for disaster recovery, military operations, and event support. According to the Federal Emergency Management Agency, rapid restoration of IT infrastructure is crucial for effective disaster response, with portable units enabling communication and data access within hours of a crisis. This capability is increasingly valued by government agencies and humanitarian organizations operating in unstable regions. Additionally, according to the Department of Defense, the strategic importance of tactical edge computing for modern warfare requires secure and transportable data processing units. Portable data centers allow military forces to process intelligence data locally, reducing latency and bandwidth dependency. The entertainment industry also drives demand for portable units to support high-bandwidth requirements at film shoots and live events. Advances in miniaturization and battery technology have enhanced the performance and autonomy of portable systems. The ability to scale down infrastructure for specific short-term needs offers cost advantages over permanent installations. As remote work and field operations expand, the versatility of portable data centers fuels their rapid growth trajectory.
By Size Insights
The large data centers segment led the market with 54.6% of the global modular data center market share in 2025. The dominance of large data centers segment in the global modular data center market is attributed to the massive scaling requirements of cloud service providers and hyperscale operators. These facilities utilize multiple modular units arranged in clusters to achieve capacities comparable to traditional mega-data centers while retaining flexibility. According to the International Data Corporation, global cloud infrastructure spending has grown by 20% annually, driving the need for expansive and efficient computing resources. Hyperscalers prefer large modular deployments because they allow for incremental capacity addition without disrupting existing operations. Furthermore, according to the Open Compute Project, modular designs enable standardization of hardware components across vast fleets, reducing maintenance complexity and costs. Large modular data centers benefit from economies of scale in procurement and energy management. They can be located in areas with cheaper land and renewable energy sources since they do not require complex urban infrastructure. The ability to decommission and relocate modules extends the asset lifecycle and improves return on investment. Major technology companies use large modular setups to balance load across geographic regions, ensuring low latency for global users. The structural integrity and security features of large modular installations meet stringent enterprise-grade requirements. This alignment with the growth of big data and artificial intelligence workloads sustains the leadership of large data centers.
On the other end, the mid-sized data centers segment is anticipated to record a prominent CAGR of 15.4% over the forecast period owing to the digital transformation needs of medium enterprises and regional service providers. These facilities offer a balance between capacity and cost, making them suitable for organizations that have outgrown small server rooms but do not require hyperscale infrastructure. According to the Small Business Administration, medium-sized enterprises are increasingly adopting hybrid cloud strategies, requiring local data processing for compliance and performance reasons. Mid-sized modular data centers provide the necessary infrastructure to support these hybrid models efficiently. Additionally, according to the Telecommunications Industry Association, regional telecom operators are deploying mid-sized modular units to support 5G network expansion and edge computing services. These units fit well in suburban areas or industrial parks where space is available but construction timelines must be short. The modularity allows businesses to start with a smaller footprint and expand as their data needs grow, avoiding over-provisioning. Energy efficiency improvements in mid-sized units make them attractive for companies focused on reducing carbon footprints. The lower capital expenditure compared to large facilities lowers the barrier to entry for growing businesses. This flexibility and scalability drive the rapid adoption of mid-sized modular solutions.
By End User Industry Insights
The IT and telecommunications segment occupied 46.4% of the global modular data center market share in 2025. The leading position of IT and telecommunications segment in the global modular data center market can be driven by the relentless growth of data traffic and the rollout of next-generation networks. Service providers require scalable and distributed infrastructure to handle increasing video streaming, cloud gaming, and Internet of Things data. According to the GSMA, global mobile data traffic is expected to triple by 2030, necessitating robust and flexible data center solutions at the network edge. Modular data centers allow telecom operators to rapidly deploy infrastructure near cell towers to reduce latency and improve user experience. Furthermore, according to the Cloud Security Alliance, telecommunications companies are prioritizing modular designs to enhance network resilience and disaster recovery capabilities. The ability to quickly replace or upgrade modules ensures continuous service availability during maintenance or failures. The sector’s shift toward software-defined networking and virtualization aligns well with the flexible nature of modular hardware. Standardized interfaces in modular units facilitate integration with existing network management systems. The competitive pressure to offer faster and more reliable services drives continuous investment in modular infrastructure. Regulatory requirements for data sovereignty also prompt telecoms to build local modular data centers in various jurisdictions. This strategic necessity cements the IT and telecommunications sector as the primary consumer of modular data center technologies.
However, the healthcare segment is predicted to expand at a CAGR of 16.4% over the forecast period in the global modular data center market owing to the digitization of medical records and telemedicine expansion. Hospitals and clinics generate vast amounts of patient data from electronic health records, imaging systems, and wearable devices, requiring secure and compliant storage. According to the World Health Organization, digital health initiatives are critical for improving healthcare access and efficiency, particularly in remote and underserved areas. Modular data centers enable healthcare providers to deploy secure local processing units in rural clinics where connecting to central servers is unreliable. Additionally, according to the Health Information and Management Systems Society, data privacy and security under regulations like HIPAA are supported through isolated and controlled environments. The rapid deployment capability is vital for setting up temporary hospitals or testing centers during public health emergencies. Telemedicine platforms rely on low-latency connections, which edge-based modular data centers can provide effectively. The aging population and rise in chronic diseases increase the volume of health data, necessitating scalable infrastructure. Healthcare organizations are increasingly investing in modular solutions to ensure business continuity and protect sensitive patient information. This focus on digital transformation and regulatory compliance drives strong growth in the healthcare segment.
REGIONAL ANALYSIS
North America Modular Data Centers Market Analysis
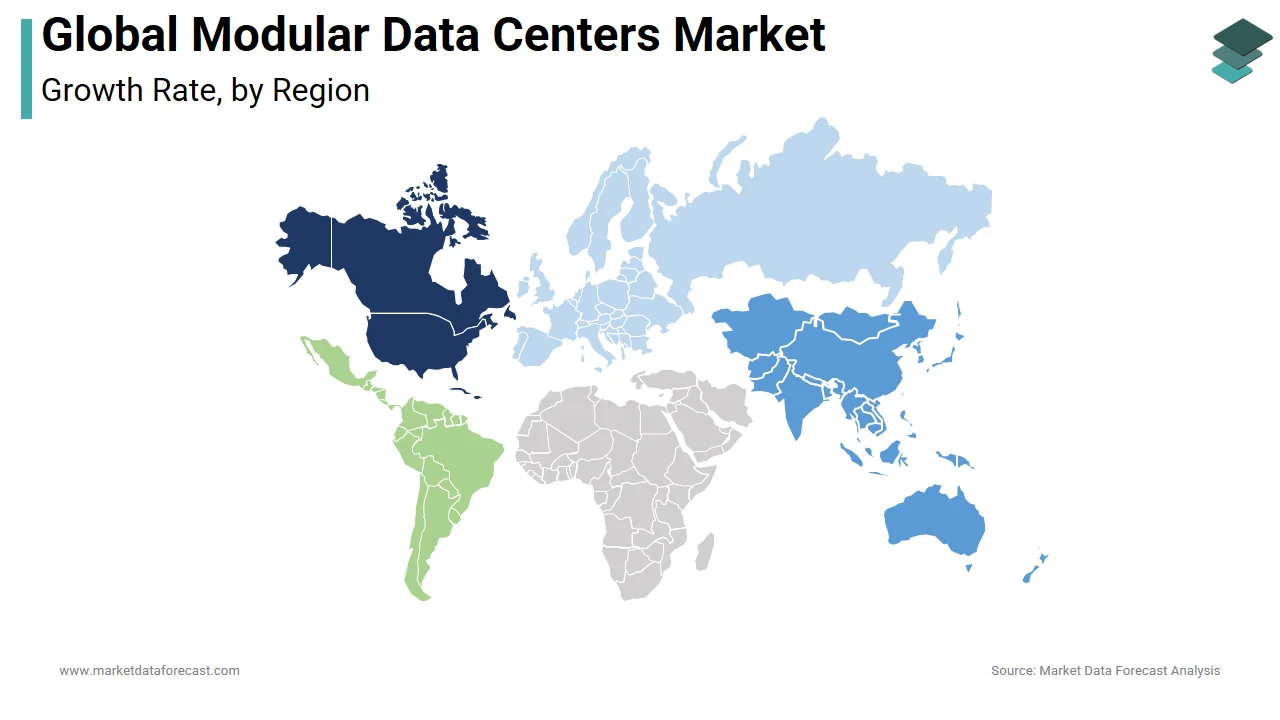
North America held 40.4% of the global modular data center market share in 2025 and is expected to experience robust economic and digital expansion over the next few years due to the advanced digital infrastructure and high adoption of cloud technologies. The region is home to major hyperscale providers and technology giants who drive demand for scalable and efficient data center solutions. According to the United States Department of Commerce, the digital economy contributes significantly to national GDP, fostering continuous investment in IT infrastructure. Strict energy efficiency regulations in states like California and New York encourage the adoption of modular units with superior Power Usage Effectiveness. The presence of leading manufacturers and innovation hubs in Silicon Valley and Texas supports technological advancements in modular design. Disaster recovery needs due to frequent natural disasters, such as hurricanes and wildfires, also boost demand for portable and containerized solutions. The mature telecommunications sector actively deploys modular edge data centers to support 5G rollouts. High labor costs for traditional construction further incentivize the use of prefabricated modular units. Government initiatives promoting broadband access in remote areas create opportunities for modular deployments in remote locations. The strong focus on cybersecurity and data sovereignty drives enterprises to adopt localized modular infrastructure. These factors collectively sustain North America’s leadership in the global modular data center market.
Europe Modular Data Centers Market Analysis
Europe is anticipated to achieve steady digital transformation and green infrastructure development over the next few years, occupying a significant position in the Modular Data Centers Market driven by stringent environmental regulations and a strong commitment to sustainability. The European Union’s Green Deal mandates significant reductions in carbon emissions, prompting data center operators to seek energy-efficient modular solutions. According to the European Commission, data centers must adhere to strict energy performance standards, which modular units often exceed through advanced cooling technologies. Countries like Germany, France, and the Netherlands are key markets due to their robust industrial bases and digital transformation initiatives. The General Data Protection Regulation imposes strict data residency requirements, encouraging companies to build local modular data centers rather than relying solely on foreign cloud providers. Rising energy costs in the region make the efficiency of modular systems financially attractive. Urban space constraints in major cities favor compact modular designs that can be deployed in limited areas. The region’s focus on circular economy principles supports the use of recyclable materials in modular construction. Government subsidies for green technology adoption further accelerate market growth. Collaboration between European tech firms and modular providers fosters innovation in sustainable data center designs. These regulatory and economic drivers ensure steady market expansion in Europe.
Asia-Pacific Modular Data Centers Market Analysis
Asia-Pacific is projected to witness accelerated technological adoption and massive digital infrastructure investments over the next few years, standing as the fastest-growing region in the Modular Data Centers Market, with a compound annual growth rate of 16.8%, due to rapid digitalization and expanding internet penetration. Countries like China, India, Japan, and Australia are witnessing a surge in data consumption driven by mobile internet usage and e-commerce growth. According to the International Telecommunication Union, internet users in Asia-Pacific have increased by 10% annually, creating immense demand for data processing capacity. Governments in the region are investing heavily in smart city projects, which require distributed and scalable data infrastructure. Modular data centers offer a quick solution to bridge the infrastructure gap in developing economies. The rising middle class and adoption of digital services in Southeast Asia drive demand for local data hosting. Natural disasters in countries like Indonesia and the Philippines increase the need for resilient and portable data center solutions. The presence of major global cloud providers expanding their footprint in the region boosts demand for large modular facilities. Lower labor and land costs in certain areas make modular deployments economically viable. The region’s focus on becoming a global digital hub supports sustained investment in modern data center technologies. These dynamics position Asia-Pacific as a key growth engine for the market.
Latin America Modular Data Centers Market Analysis
Latin America is likely to experience progressive digital upgrades and expanding telecommunications networks over the next few years, representing an emerging segment in the Modular Data Centers Market characterized by growing digital adoption and infrastructure development needs. Brazil, Mexico, and Chile are leading markets where increasing internet connectivity and smartphone usage drive data demand. According to the Economic Commission for Latin America and the Caribbean, digital transformation is a priority for regional governments to improve public services and economic competitiveness. Modular data centers provide a cost-effective way to expand IT infrastructure in regions with limited construction resources. Power instability in some areas makes the integrated backup power features of modular units attractive. The growth of fintech and e-commerce sectors requires secure and reliable data hosting solutions. Telecommunications companies are deploying modular edge data centers to improve network performance in urban and rural areas. Government initiatives to promote broadband access in remote communities create opportunities for portable data center deployments. The region’s vulnerability to climate change increases the appeal of resilient modular infrastructure. Foreign investment in local data center projects is rising as international companies seek to serve the Latin American market. These factors contribute to the gradual but steady growth of the modular data center market in the region.
Middle East and Africa Modular Data Centers Market Analysis
The Middle East and Africa are expected to witness sustained infrastructural development and smart city investments over the next few years, representing a niche but strategically important segment in the Modular Data Centers Market driven by extreme climate conditions and digital economy ambitions. Countries in the Gulf Cooperation Council are investing heavily in smart infrastructure and cloud computing to diversify their economies beyond oil. According to the International Renewable Energy Agency, the region’s abundant solar energy potential supports the operation of energy-efficient modular data centers. Extreme heat and dust storms make traditional construction challenging, favoring sealed and cooled modular units. South Africa and Kenya are emerging hubs for digital services in Africa, requiring scalable data infrastructure. Modular data centers offer a rapid solution to meet the growing data needs of these developing markets. Government initiatives like Saudi Vision 2030 promote digital transformation and data localization, driving demand for local data centers. The lack of established infrastructure in many African countries makes modular deployments a practical alternative to building permanent facilities. International aid and investment in digital literacy and connectivity support market growth. The need for disaster recovery solutions in politically unstable regions also boosts demand for portable units. These unique environmental and economic factors shape the market dynamics in the Middle East and Africa.
COMPETITIVE LANDSCAPE
The competition in the Modular Data Centers Market is characterized by intense rivalry among established infrastructure giants and specialized modular vendors. Large multinational corporations leverage their extensive product portfolios and global service networks to offer comprehensive end-to-end solutions. Specialized players differentiate themselves through niche innovations such as advanced liquid cooling or unique form factors tailored for specific use cases. Price competition is significant, particularly in commoditized segments where standard containerized units face pressure from low-cost manufacturers. Technological differentiation serves as a key competitive lever, with companies racing to achieve superior energy efficiency and power density metrics. Strategic alliances with software providers and system integrators help vendors deliver integrated value propositions beyond hardware alone. Regional variations in regulations and climate conditions require competitors to adapt their offerings locally, creating barriers to entry for global players lacking local expertise. The emergence of open source hardware standards introduces new competitive dynamics by reducing vendor lock-in concerns. Customer loyalty increasingly depends on demonstrated operational reliability and total cost of ownership rather than initial price alone. This dynamic landscape necessitates continuous innovation and strategic agility for sustained success.
KEY MARKET PLAYERS
The leading companies operating in the global modular data center market include:
- Rittal GmbH & Co. KG
- Cisco Systems, Inc.
- IBM Corporation
- Huawei Technologies Co., Ltd.
- CommScope, Inc.
- Baselayer Technology, LLC
- Schneider Electric SE
- The Hewlett Packard Enterprise Company
- Dell, Inc.
- SGI Corporation
- IO Data Centers LLC
- Flexenclosure AB
- BladeRoom Group Ltd.
- Cannon Technologies
- Eaton Corporation
- Vertiv Co.
- STULZ GmbH
TOP PLAYERS IN THE MARKET
- Schneider Electric SE maintains a prominent position in the Modular Data Centers Market through its comprehensive EcoStruxure platform and prefabricated modular solutions. The company integrates power management, cooling, and software into standardized units that enable rapid deployment for edge and hyperscale applications. Schneider recently expanded its manufacturing capabilities in North America to reduce lead times and support local supply chains. They also launched updated liquid cooling modules designed specifically for high-density artificial intelligence workloads requiring superior thermal management. Their focus on sustainability drives innovation in energy-efficient designs that help clients meet carbon reduction targets. The organization actively collaborates with cloud providers to develop customized modular architectures. These strategic initiatives reinforce their leadership in delivering resilient and scalable data center infrastructure globally.
- Huawei Technologies Co Ltd. contributes significantly to the Modular Data Centers Market by offering integrated smart modular solutions that combine digital power technologies with advanced cooling systems. The company emphasizes artificial intelligence-driven energy optimization to achieve industry-leading Power Usage Effectiveness ratings in its prefabricated units. Huawei recently introduced next-generation containerized data centers featuring indirect evaporative cooling to minimize water consumption in arid regions. They have strengthened their global service network to provide faster installation and maintenance support for international clients. Their research and development efforts focus on integrating renewable energy sources directly into modular designs. The company also promotes open standards to improve interoperability across different infrastructure components. These actions enhance their competitiveness in delivering sustainable and intelligent modular data center solutions worldwide.
- Vertiv Holdings Co plays a vital role in the Modular Data Centers Market by providing critical digital infrastructure and continuous expertise for modular deployments. The company offers a wide range of prefabricated modules, including all-in-one units and specialized power or cooling pods tailored for diverse applications. Vertiv recently enhanced its modular portfolio with advanced thermal management solutions capable of supporting high-performance computing densities. They have invested in digital tools that enable remote monitoring and predictive maintenance for distributed modular sites. The organization focuses on helping clients navigate complex regulatory environments through pre-certified and compliant designs. Vertiv also partners with system integrators to deliver turnkey solutions for edge computing scenarios. These strategic moves strengthen their ability to serve customers requiring reliable and scalable modular infrastructure.
TOP STRATEGIES USED BY KEY MARKET PARTICIPANTS
Key players in the Modular Data Centers Market employ several strategic approaches to maintain competitive advantage and drive growth. Product innovation remains a primary strategy, with companies investing heavily in research and development to create more energy-efficient and high-density modular solutions. Strategic partnerships with cloud service providers and telecommunications operators enable firms to align their offerings with evolving workload requirements. Geographic expansion through localized manufacturing helps reduce supply chain risks and shorten delivery timelines for regional customers. Companies also focus on sustainability by integrating renewable energy compatibility and circular economy principles into their modular designs. Digital transformation strategies involve embedding artificial intelligence and remote monitoring capabilities to enhance operational efficiency. Mergers and acquisitions allow firms to acquire specialized technologies or expand their service portfolios rapidly. Standardization initiatives aim to improve interoperability and reduce integration complexity for multi-vendor environments. Customer education programs help bridge knowledge gaps and accelerate adoption of modular architectures. These combined strategies enable market participants to address diverse customer needs while navigating technological and regulatory challenges effectively.
MARKET SEGMENTATION
This research report on the global modular data centers market has been segmented and sub-segmented into the following categories.
By Type
- Portable
- Containerized
By Size
- Mid-Sized Data Centre
- Large Data Centre
- Enterprise Data Centre
By Industries
- BFSI
- IT & Telecom
- Media & Entertainment
- Healthcare
- Aerospace & Defense
- Energy
- Retail
- Manufacturing
- Others
By Region
- Europe
- North America
- Asia-Pacific
- Middle East and Africa (MEA)
- Latin America