- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$82.84 BnMarket Estimate, 2026
$88.88 BnMarket Forecast, 2034
$156.18 BnCAGR, 2026–2034
7.3%Executive Summary: Global Non-Invasive Cancer Diagnostics Market
- Market Scope: Comprehensive global non-invasive cancer diagnostics market analysis covering therapeutics/cancer types, diagnostic techniques, regional leadership frameworks, growth drivers, and market challenges.
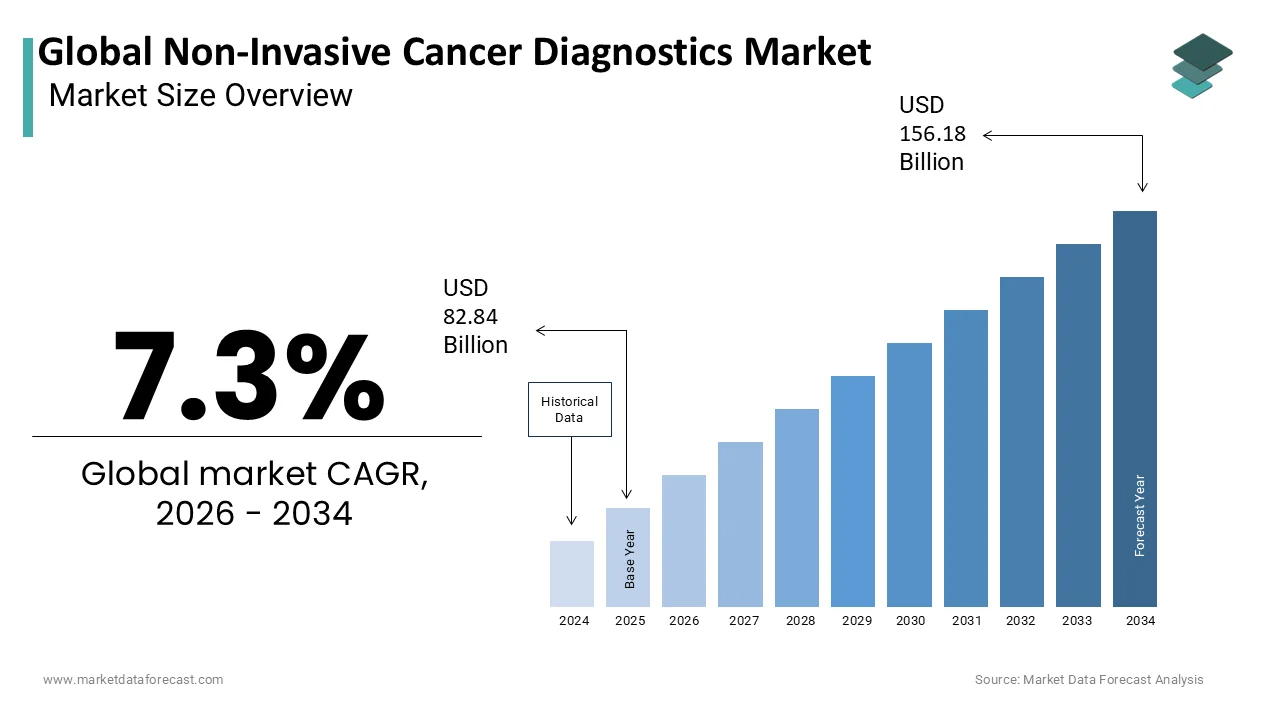
- Market Valuation: Valued at USD 82.84 billion (2025), estimated at USD 88.88 billion (2026), and projected to reach USD 156.18 billion by 2034, registering a robust CAGR of 7.3% (2026–2034).
- Primary Growth Drivers: Rising cancer prevalence, an aging population, escalating demand for non-invasive diagnostic technologies, expanding awareness of early cancer detection, and growing research and development activities. Key operational metrics include the WHO estimating roughly 15 million new cancer cases annually, with breast, ovarian, and gastrointestinal cancers among the most common.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (2025 Position) | Fastest-Growing Segment |
|---|---|---|
| By Therapeutics | Breast Cancer (recorded the majority share driven by high case volumes and healthcare sector improvements) | Lung Cancer & Solid Tumors (experiencing rising demand for advanced liquid biopsy and biomarker testing) |
| By Techniques | Clinical Chemistry (expected to hold a leading share backed by robust clinical data availability) | Molecular Diagnostics & Immunochemistry (driven by advancements in circulating tumor DNA and biomarker detection) |
| By Region | North America (dominated the global market due to high healthcare expenditure and R&D investments) | Asia-Pacific (anticipated to witness the fastest growth rate driven by increasing cancer prevalence and rising awareness) |
Major Market Players & Market Structure
Market Structure: Highly competitive landscape featuring notable diagnostics leaders competing on advanced liquid biopsy technologies, sensitivity and specificity enhancements, strategic partnerships, and global distribution networks.
Key Companies: Precision Therapeutics, Laboratory Corporation of America Holdings (LabCorp), BIOVIEW Inc., Affymetrix Inc., AVIVA Biosciences Corporation, A&G Pharmaceutical, Quest Diagnostics Incorporated, Cancer Genetics Inc., Digene Corporation, and Gen-Probe Incorporated.
Global Non-Invasive Cancer Diagnostics Market Size
The Global Non-invasive Cancer Diagnostics Market is projected to grow from USD 82.84 billion in 2025 to USD 88.88 billion in 2026 and reach USD 156.18 billion by 2034, registering a CAGR of 7.3% during the forecast period from 2026 to 2034.
Non-invasive cancer diagnostics are advanced technologies and methodologies designed to detect, monitor, and characterize malignancies without the need for surgical biopsy or tissue extraction. The primary objective is to enable early detection, real-time monitoring of treatment response, and identification of minimal residual disease with minimal patient discomfort and risk. As per the World Health Organization, cancer remains a leading cause of death globally, accounting for nearly 10 million deaths in 2020, which promotes the urgent need for accessible and precise diagnostic tools. According to the American Cancer Society, approximately 2.1 million new cancer cases will be diagnosed in the United States in 2026. Traditional invasive biopsies carry risks of complications,s sampling errors, rs aan nd inability to capture tumor heterogeneity, which non-invasive methods aim to mitigate. Regulatory bodies such as the Food and Drug Administration are increasingly approving liquid biopsy assays for specific indications, reflecting growing clinical validation. The integration of artificial intelligence in image analysis and genomic data interpretation further enhances diagnostic accuracy.
MARKET DRIVERS
Rising Global Cancer Incidence and Aging Population
The escalating global prevalence of cancer coupled with demographic shifts towards an aging population is driving the growth of the non-invasive cancer diagnostics market. As life expectancy increases, the cumulative exposure to carcinogens and genetic mutations leads to higher incidence rates of malignancies requiring frequent monitoring and early detection. According to the International Agency for Research on Cancer, the number of new cancer cases worldwide is projected to rise by 77% between 2022 and 2050, reaching approximately 35 million annually. This surge creates an overwhelming demand for diagnostic solutions that can handle high volumes efficiently without the logistical and clinical burdens of invasive procedures. The Centers for Disease Control and Prevention reports that the majority of cancer diagnoses occur in individuals aged 65 and older,r a demographic segment that is expanding rapidly in developed nations. Older patients often present with comorbidities that make surgical biopsies risky or contraindicated, thereby making non-invasive alternatives such as liquid biopsies and advanced imaging necessary for safe management. Furthermore, the shift towards screening programs for breast, colorectal, and lung cancers in asymptomatic populations drives the utilization of non-invasive modalities like low-dose computed tomography and stool DNA tests.
Advancements in Genomic Sequencing and Liquid Biopsy Technologies
The rapid technological advancements in next-generation sequencing and the commercialization of liquid biopsy platforms are significantly accelerating the growth of the non-invasive cancer diagnostics market. Liquid biopsies analyze circulating tumor DNA, circulating tumor cells,s and exosomes from blood samples, providing a comprehensive view of tumor genetics and heterogeneity that single-site tissue biopsies may miss. This cost reduction enables the development of multi-cancer early detection tests that can screen for dozens of cancer types from a single blood draw. Clinical studies published in journals such as The Lancet Oncology demonstrate that liquid biopsies can detect molecular residual disease months before radiographic recurrence, allowing for earlier intervention. The ability to monitor treatment response in real time through serial blood draws reduces the need for repeated invasive procedures and radiation exposure from frequent imaging. Pharmaceutical companies are increasingly incorporating liquid biopsies into clinical trials to stratify patients and assess drug efficacy, accelerating regulatory acceptance.
MARKET RESTRAINTS
High Cost of Advanced Diagnostic Tests and Limited Reimbursement
The substantial financial burden associated with advanced non-invasive diagnostic tests, particularly multi-analyte liquid biopsies and high-resolution molecular imaging, is hindering the growth of the non-invasive cancer diagnostics market. These technologies require sophisticated laboratory infrastructure,e specialized reagents, and complex bioinformatics analysis, resulting in high per-test costs that often exceed thousands of dollars. Insurance coverage for novel non-invasive diagnostics remains inconsistent, with many payers classifying them as experimental or investigational due to limited long-term clinical utility data. The Centers for Medicare and Medicaid Services has strict coverage determinations that often exclude newer liquid biopsy assays unless they are specifically approved for guiding treatment decisions in advanced stages. This lack of standardized reimbursement creates uncertainty for healthcare providers who hesitate to prescribe tests that may not be covered, leading to delayed diagnoses. The economic disparity restricts the equitable distribution oflife-savingg technologies and slows down the volume growth necessary for manufacturers to achieve economies of scale.
Regulatory Complexity and Lack of Standardized Guidelines
The intricate and evolving regulatory landscape surrounding non-invasive cancer diagnostics, coupled with the absence of universally accepted clinical guidelines, is additionally hindering the growth of the non-invasive cancer diagnostics market. Regulatory bodies such as the Food and Drug Administration and the European Medicines Agency have different classification criteria for laboratory-developed tests versus commercial kits, creating compliance challenges for manufacturers. The regulatory oversight of laboratory-developed tests has been a subject of ongoing debate and legal contention, creating uncertainty for developers of innovative diagnostic assays. The lack of harmonized standards for sample collection, processing, and data interpretation leads to variability in test performance and reliability across different laboratories. Clinical practice guidelines from organizations like the National Comprehensive Cancer Network are slow to incorporate new non-invasive technologies due to the need for extensive validation studies. This lag means that oncologists may not have clear recommendations on when and how to use these tests,ests leading to underutilization or inappropriate application. The complexity of validating multi-omic algorithms against clinical outcomes requires large prospective trials, which are time-consuming and expensive.
MARKET OPPORTUNITIES
Integration of Artificial Intelligence in Image and Data Analysis
The integration of artificial intelligence and machine learning algorithms into non-invasive diagnostic platforms to enhance diagnostic accuracy and workflow efficiency is likely to promote new opportunities for the growth of the non-invasive cancer diagnostics market. AI-powered software can analyze complex medical images such as mammograms, CT scans, and MRI sequences with greater speed and precision than human radiologists, identifying subtle patterns indicative of early-stage malignancies. AI algorithms have demonstrated performance comparable to or exceeding board-certified radiologists in detecting breast cancer from screening mammograms, reducing false positives and negatives. In liquid biopsies, AI helps interpret vast amounts of genomic data to distinguishtumor-derivedd signals from background noise, improving sensitivity for rare mutations. The ability to aggregate data from multiple sources,s including imaging, genomics, and electronic health records,ords enables the development of comprehensive predictive models for cancer risk and progression. Healthcare providers are increasingly adopting these digital tools to reduce diagnostic errors and streamline reporting times. Payers are recognizing the value of AI in reducing unnecessary follow-up procedures and treatments driven by misdiagnosis.
Expansion into Multi-Cancer Early Detection Screening
The development and commercialization of multi-cancer early detection tests by shifting the focus from single-organ screening to pan-cancer surveillance is also leveraging the growth of the non-invasive cancer diagnostics market. These tests utilize methylation patterns or protein biomarkers in blood samples to detect signals from multiple cancer types simultaneously, offering a holistic approach to early diagnosis. The current screening guidelines cover only a few cancer types, such as breast, cervical, colorectal, and lung, leaving many deadly cancers like pancreatic and ovarian undetected until late stages. Multicancer early detection tests aim to fill this gap by identifying cancers that currently lack effective screening methods,s potentially saving millions of lives through earlier intervention. Clinical trials such as the PATHFINDER study have shown promising results in detecting various cancer types with high specificity, although sensitivity varies by stage and type. Large-scale population studies are underway to validate the clinical utility and cost-effectiveness of these tests in average-risk populations.
MARKET CHALLENGES
Biological Variability and False Positive Results
The inherent biological variability in biomarker levels among healthy individuals and the risk of false positive results is likely to act as a major barrier for the growth of the non-invasive cancer diagnostics market. Circulating tumor DNA levels can be influenced by factors such as age, inflammation,n clonal hematopoiesis, i,s and benign conditions, ns leading to signals that mimic cancer presence. According to research, clonal hematopoiesis of indeterminate potential is a common source of false positives in liquid biopsy tests, particularly in older adults,lts complicating interpretation. False positive results can trigger unnecessary anxiety and additional invasive testing, such as biopsies, and even unwarranted treatments, exposing patients to physical and emotional harm. The psychological toll of a cancer scare can be profound,d affecting mental health and quality of life even after cancer is ruled out. Clinicians face the difficult task of communicating uncertain results and managing patient expectations while awaiting confirmatory tests. The lack of standardized thresholds for what constitutes a positive result across different platforms adds to the confusion. Reducing false positives requires larger and more diverse reference datasets to account for biological noise, which is resource-intensive to generate.
Ethical and Privacy Concerns Regarding Genetic Data
The collection, storage, and analysis of sensitive genetic and genomic data from non-invasive diagnostics raise profound ethical and privacy concerns and also impede the growth of the non-invasive cancer diagnostics market. Liquid biopsies and genomic sequencing reveal not only cancer-related mutations but also incidental findings regarding hereditary diseases and predispositions that patients may not wish to know. Protections exist in the United States, but gaps remain in life insurance, long-term care insurance,ce and international jurisdictions, where discrimination based on genetic data is possible. Patients worry about data breaches and unauthorized access to their genetic information, which could have lifelong implications for employment and insurability. The ownership of genetic data and who has the right to profit from its use in research and drug development is a contentious issue. Regulatory frameworks such as the General Data Protection Regulation in Europe impose strict requirements on data consent and anonymization, ion increasing operational complexity for diagnostic companies. Ensuring robust cybersecurity measures to protect against hacking and data theft is essential but costly. The lack of public trust in how genetic data is handled can deter individuals from undergoing testing, limiting the pool of data needed for algorithm improvement.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Covered | By Therapeutics, Techniques, and Region |
| Various Analyses Covered | Global, Regional & Country Level Analysis, Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview on Investment Opportunities |
| Regions Covered | North America, Europe, APAC, Latin America, Middle East & Africa |
| Market Leaders Profiled | Precision Therapeutics, Laboratory Corporation of America Holdings (LabCorp) |
SEGMENTAL ANALYSIS
By Therapeutics Insights
The lung cancer segment accounted for 44.5% of the non-invasive cancer diagnostics market share in 2025 due to its status as the leading cause of cancer-related mortality globally and the critical need for early detection to improve survival rates. The high incidence rate combined with the availability of effective screening modalities such as low-dose computed tomography drives substantial diagnostic volume. As per the World Health Organization, lung cancer accounted for approximately 1.8 million deaths worldwide in 2020, representing nearly 18% of all cancer deaths. Furthermore, the rise of liquid biopsy technologies for detecting circulating tumor DNA in lung cancer patients allows for real-time monitoring of treatment response and resistance mechanisms without repeated tissue biopsies. The American Thoracic Society guidelines strongly recommend annual screening for high-risk individuals, creating a standardized pathway for diagnostic utilization.

The breast cancer segment is likely to grow at the fastest CAGR of 12.5% during the forecast period, driven by increasing awareness, extensive screening programs, and the development of novel liquid biopsy assays. Breast cancer is the most commonly diagnosed cancer in women globally, creating a vast addressable population for diagnostic services. As per the International Agency for Research on Cancer, there were approximately 2.3 million new cases of breast cancer in 202,0 making it the most prevalent malignancy. The shift towards personalized medicine has spurred the development of non-invasive tests that can detect minimal residual disease and predict recurrence risk. The Food and Drug Administration has approved several blood-based tests for monitoring metastatic breast cancer, encouraging their integration into clinical practice. Additionally, the demand for alternatives to invasive surgical biopsies for routine monitoring is rising among patients seeking less painful and lower-risk options. Advances in methylation analysis and protein biomarker detection are improving the sensitivity of blood tests for early-stage breast cancer. Public health campaigns promoting regular mammography and self-examination further drive diagnostic uptake.
By Techniques Insights
The molecular diagnostics segment accounted for 48.2% of the non-invasive cancer diagnostics market share in 2025 due to its ability to provide precise genetic and genomic information essential for personalized oncology. This technique includes polymerase chain reaction, next-generation sequencing,g and fluorescence in situ hybridization, which analyze circulating tumor DNA, RNA, and other biomarkers in bodily fluids. As per the Association for Molecular Pathology, molecular testing has become standard of care for many cancers, including lung, rectal, and melanoma, to identify targetable mutations. The precision offered by molecular diagnostics enables clinicians to select targeted therapies that improve outcomes and reduce unnecessary toxicity. The cost of next-generation sequencing has decreased significantly, making it accessible for routine clinical use. According to the National Institutes of Health, the cost of sequencing a human genome has dropped from millions of dollars to under 1000 dollar,s facilitating widespread adoption. Liquid biopsies relying on molecular techniques allow for the detection of rare mutations and monitoring of clonal evolution over time. Regulatory approvals for companion diagnostics linked to specific drugs further drive demand. The ability to assess tumor heterogeneity and resistance mechanisms non-invasively makes molecular diagnostics indispensable in modern cancer care.
The immunochemistry segment is anticipated to grow at the fastest CAGR of 11.8% from 2026 to 2034 with the rising importance of immunotherapy and the need to assess immune checkpoint markers. This technique involves the detection of specific protein antigens and antibodies in blood or tissue samples using labeled antibodies. The use of immune checkpoint inhibitors has transformed the treatment landscape for various cancers, creating a demand for diagnostic tests that predict response. Biomarkers such as PD-L1 are routinely assessed to determine eligibility for immunotherapy, driving the adoption of immunochemical assays. The development of highly sensitive immunoassays for circulating tumor cells and exosomes enhances the capability of liquid biopsies. Combining molecular and immunochemical data improves diagnostic accuracy and prognostic value. Advances in multiplexing technologies allow for the simultaneous detection of multiple biomarkers from a single sample, increasing efficiency. The growing pipeline of immunotherapeutic agents requires robust diagnostic companions to guide treatment decisions.
COUNTRY LEVEL ANALYSIS
North America Non-Invasive Cancer Diagnostics Market Analysis
North America was the top performer of the global non-invasive cancer diagnostics market by occupying 38.2% of the share in 202,5 wite advanced healthcare infrastructure, high research and development investment, and favorable reimbursement policies. The Food and Drug Administration actively supports the approval of novel diagnostic tests, including liquid biopsies, accelerating entry. High healthcare expenditure per capita allows for the adoption of premium diagnostic technologies. The National Comprehensive Cancer Network guidelines frequently incorporate non-invasive diagnostic methods,s ensuring standardized clinical use. Strong intellectual property protection encourages pharmaceutical and diagnostic firms to invest in new technologies. The prevalence of chronic diseases and an aging population further sustains demand. Collaborative efforts between industry and government agencies promote early detection initiatives.
Europe Non-Invasive Cancer Diagnostics Market Analysis
Europe non-invasive cancer diagnostics market was ranked second, holding a 20.5% share in 2025, with universal healthcare systems, stringent regulatory standards, and a strong focus on preventive care. The region emphasizes evidence-based medicine and cost-effectiveness, leading to selective but high-quality adoption of diagnostic technologies. As per the European Commission, cancer affects millions of Europeans annually, prompting coordinated efforts to improve early detection and diagnosis. Countries like Germany, France, and the United Kingdom have established national screening programs for breast, colorectal, and cervical cancer,s driving diagnostic volume. The European Society for Medical Oncology provides guidelines that influence clinical practice across member states. Public funding for research supports the development of innovative diagnostic tools. However, budget constraints in some countries limit the adoption of expensive new tests. The aging population and rising cancer incidence sustain steady demand.
Asia-Pacific Non-Invasive Cancer Diagnostics Market Analysis
The Asia-Pacific non-invasive cancer diagnostics market growth is expected to have prominent growth opportunities in the coming years, with rapid healthcare infrastructure development, increasing disposable income, and rising cancer prevalence. Countries such as China, India, Japan, and Australia are investing heavily in modernizing diagnostic facilities to meet growing demand. As per the World Health Organization, the Asia-Pacific region accounts for more than half of global cancer cases, es creating immense potential for diagnostic services. Governments are implementing national cancer control plans that include screening and early detection initiatives. The growing middle class is increasingly able to afford advanced diagnostic tests, reducing reliance on late-stage presentation. Local manufacturers are developing cost-effective diagnostic solutions tailored to regional needs. The rise of medical tourism in countries like Thailand and Singapore brings international standards to local practices. Increasing awareness of cancer risks and the benefits of early detection drives patient demand. However, disparities in access between urban and rural areas remain a challenge.
Latin America Non-Invasive Cancer Diagnostics Market Analysis
Latin America non-invasive cancer diagnostics market growth is expected to grow with improving healthcare access and increasing government focus on noncommunicable diseases. While economic volatility poses challenges, the region is seeing steady growth in demand for essential diagnostic services. As per the Pan American Health Organization, cancer is a leading cause of death in the region, prompting efforts to strengthen diagnostic capabilities. Brazil and Mexico are the largest contributor,s driven by their large populations and expanding private healthcare sectors. The implementation of universal health coverage programs in countries like Colombia and Chile that improves access to basic diagnostic tests. Healthcare expenditure in the region is gradually rising, supporting the acquisition of medical technologies. Local distributors are partnering with international manufacturers to introduce affordable yet reliable diagnostic tools. The prevalence of infectious diseases and limited resources often prioritize acute care over preventive diagnostics. However, increasing awareness and advocacy efforts are shifting focus towards early detection. Currency fluctuations and import tariffs can affect device pricing and availability.
The Middle East and Africa Non-Invasive Cancer Diagnostics Market Analysis
The Middle East and Africa non-invasive cancer diagnostics growth is driven by varying levels of economic development and healthcare infrastructure maturity. Gulf Cooperation Council countries such as Saudi Arabia and the United Arab Emirates are leading the region with significant investments in smart healthcare and digital transformation initiatives. These nations are implementing national health strategies to improve healthcare quality and efficiency,y supporting Vision 2030 goals. The establishment of world-class medical cities drives demand for state-of-the-art diagnostic technologies. In Africa, countries like South Africa and Kenya are leveraging mobile technology to overcome infrastructure challenges and improve health data collection. Initiatives to combat infectious diseases and improve maternal health require robust healthcare systems that include diagnostic services. International aid and partnerships support the provision of diagnostic tools in low-resource settings. The growing awareness of cancer as a public health priority encourages governments to invest in screening programs. Challenges related to supply chain logistics and skilled workforce remain but are being addressed through regional cooperation.
COMPETITIVE LANDSCAPE
The competitive landscape of the non-invasive cancer diagnostics market is characterized by intense rivalry between established diagnostic giants and innovative biotechnology startups vying for dominance in liquid biopsy and imaging sectors. Leading companies differentiate themselves through superior analytical sensitivity, broad panel coverage,e and robust clinical validation data that support regulatory approvals. Competition extends beyond technical specifications to include reimbursement strategy, physician relationships, ps and patient accessibility initiatives. Strategic alliances with healthcare systems and insurance payers are important for securing coverage and driving volume. Price competition is moderate for specialized tests but intensifies, as more players enter the screening market with similar offerings. Intellectual property protection and patent portfolios serve as significant barriers to entry,ry favoring incumbents with extensive research backgrounds.
KEY MARKET PLAYERS
Some of the companies that are playing a dominating role in the Global Non-Invasive Cancer Diagnostics Market include
- Precision Therapeutics
- Laboratory Corporation of America Holdings (Labcorp)
- BIOVIEW Inc.
- Affymetrix Inc.
- AVIVA Biosciences Corporation
- A&G Pharmaceutical
- Quest Diagnostics Incorporated
- Cancer Genetics, Inc.
- Digene Corporation
- Gen-Probe Incorporated
TOP LEADING PLAYERS IN THE MARKET
- Guardant Health Inc is a pioneering leader in the non-invasive cancer diagnostics market by specializing in liquid biopsy technologies for early detection and monitoring. The company developed the Guardant Reveal test, which detects circulating tumor DNA to identify minimal residual disease in colorectal cancer patients. Recently, Guardant Health expanded its portfolio with multi-cancer early detection tests aiming to screen for various malignancies from a single blood sample. They actively collaborate with healthcare providers and payers to demonstrate clinical utility and secure reimbursement coverage. Their focus on rigorous clinical validation and large-scale studies strengthens their position as a trusted partner in precision oncology.
- Exact Sciences Corporation serves as a key player in the non-invasive cancer diagnostics market, known for its Cologuard stool DNA test for colorectal cancer screening. The company leverages advanced molecular biology to detect abnormal DNA and blood biomarkers in stool samples by offering a convenient alternative to colonoscopy. Recently, Exact Sciences acquired Guardant Health to expand its capabilities in liquid biopsy and multi-cancer early detection. They invest heavily in direct-to-consumer marketing and physician education to increase screening rates among eligible populations. Their integration of genomic science with practical delivery models enhances accessibility and patient compliance.
- F Hoffmann La Roche Ltd holds a significant position in the non-invasive cancer diagnostics market through its comprehensive portfolio of tissue and liquid biopsy solutions. The company provides advanced molecular diagnostic tests and instruments that support personalized cancer treatment decisions. Recently, Roche launched new companion diagnostics for targeted therapies,ies ensuring patients receive the most effective treatments based on their genetic profiles. They partner with pharmaceutical companies to co-develop diagnostic assays that accompany novel drug launches. Their global distribution network and strong regulatory expertise facilitate widespread access to high-qualitydiagnostic tools.
TOP STRATEGIES USED BY KEY MARKET PARTICIPANTS
Key players in the non-invasive cancer diagnostics market prioritize strategic partnerships with pharmaceutical companies to co-develop companion diagnostics that guide targeted therapy selection. Manufacturers invest heavily in clinical trials and real-world evidence generation to validate the accuracy and clinical utility of their tests for regulatory approval and reimbursement. Expansion into multi-cancer early detection platforms allows companies to address unmet needs in screening for cancers lacking effective methods. Focus on artificial intelligence and machine learning enhances data analysis capabilities, improving sensitivity and specificity of diagnostic algorithms. Direct-to-consumer marketing campaigns increase public awareness and demand for non-invasive screening options. Regulatory engagement ensures compliance with evolving standards across different geographic regions.
RECENT HAPPENINGS IN THE MARKET
-
Roche Diagnostics introduced the first in vitro diagnostic immunohistochemistry (IHC) assay in 2019 to improve lung cancer diagnosis.
-
In 2014, the U.S. The FDA approved the product for non-invasive colorectal cancer testing, which is one of the most common cancers seen in recent years.
MARKET SEGMENTATION
This research report on the global non-invasive cancer diagnostics market has been segmented and sub-segmented into the following categories andanalyzed thee market size and forecast until 2029.
By Therapeutics
- Blood cancer
- Breast Cancer
- Lung Cancer
- Solid Tumors
By Techniques
- Immunochemistry
- Clinical Chemistry
- Molecular Diagnostics
By Region
- North America
- Europe
- Asia-Pacific
- Latin America
- Middle East and Africa