- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$15.17 BnMarket Estimate, 2026
$16.71 BnMarket Forecast, 2034
$36.13 BnCAGR, 2026–2034
10.12%Executive Summary: Global Oxygen Therapy Market
- Market Scope: Comprehensive global market analysis of the oxygen therapy industry covering product variants, therapeutic applications, care settings, and regional market shares.
- Market Valuation: Valued at USD 15.17 billion (2025), estimated at USD 16.71 billion (2026), and projected to reach USD 36.13 billion by 2034, registering a strong CAGR of 10.12% (2026–2034).
- Primary Growth Drivers: Rising prevalence of chronic respiratory diseases (such as COPD affecting ~392 million people globally), an aging global population, and rapid technological advancements in lightweight portable oxygen concentrators.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (2025 Position) | Fastest-Growing Segment |
|---|---|---|
| By Product Type | Oxygen concentrators (dominated market share due to long-term cost-effectiveness and ambient air extraction) | Portable oxygen concentrators (growing due to patient demand for mobility, active lifestyles, and pulse dose technology) |
| By Application | Chronic Obstructive Pulmonary Disease (COPD) (holding dominant share due to high mortality rates and chronic hypoxemia management) | Obstructive sleep apnea (growing at an 8.2% CAGR driven by global obesity trends and home diagnostic improvements) |
| By End User | Home healthcare (led market share favored by cost containment strategies, telemedicine integration, and patient preference) | Hospitals (projected at a 7.1% CAGR driven by emergency admissions for acute respiratory distress and critical care infrastructure) |
| By Region / Country | North America (dominated with 36.3% global share supported by advanced healthcare infrastructure and strong reimbursement models) | Asia Pacific (rapid market acceleration driven by industrialization, rising air pollution, and expanding healthcare access) |
Major Market Players & Market Structure
Market Structure: Highly competitive global marketplace characterized by strict regulatory compliance (FDA, EMA, ISO standards), supply chain resilience strategies, and a shift toward digital health and smart remote patient monitoring.
Key Companies: Respironics Inc., Teleflex Incorporated, AirSep Corporation, DeVilbiss Healthcare, ResMed Inc., Fisher & Paykel Healthcare Limited, Invacare, Essex Industries Inc., HERSILL S.L., and Weinmann Emergency Medical Technology.
Global Oxygen Therapy Market Size
The global oxygen therapy market size was valued at USD 15.17 billion in 2025. The market is expected to grow at a significant CAGR of 10.12% from 2026 to 2034 and be worth USD 36.13 billion by 2034 from USD 16.71 billion in 2026.

According to the World Health Organization, chronic respiratory diseases affect approximately 400 million people globally, creating a substantial baseline demand for long term oxygen therapy. The aging global population further exacerbates this need, with the United Nations Department of Economic and Social Affairs projecting that the number of persons aged 65 years or older will double to 1.5 billion by 2050. This demographic shift necessitates scalable home healthcare solutions that allow patients to manage their condition outside clinical environments. Technological advancements have led to the development of lighter, quieter, and more energy efficient devices that enhance patient compliance and quality of life. Regulatory bodies such as the Food and Drug Administration in the United States and the European Medicines Agency enforce strict safety standards to ensure device reliability. The integration of digital health technologies enables remote monitoring of oxygen saturation levels, allowing clinicians to adjust prescriptions in real time. This evolution transforms oxygen therapy from a static treatment into a dynamic component of personalized respiratory care.
MARKET DRIVERS
Rising Prevalence of Chronic Respiratory Diseases
The rising incidence of chronic respiratory disorders is a major factor propelling the global oxygen therapy market expansion. Conditions such as Chronic Obstructive Pulmonary Disease, asthma, and interstitial lung disease require consistent oxygen supplementation to maintain adequate blood oxygen levels and prevent organ damage. According to the Global Initiative for Chronic Obstructive Lung Disease, COPD affects approximately 392 million people worldwide and is projected to become the third leading cause of death globally by 2030. This high disease burden drives sustained demand for both acute and long term oxygen therapy devices. Environmental factors including air pollution and smoking continue to contribute to the onset and progression of these conditions. According to the World Health Organization, ambient air pollution causes an estimated 4.2 million premature deaths annually, many of which are linked to respiratory complications. Consequently, healthcare systems are increasingly prioritizing early diagnosis and management of respiratory insufficiency. Home oxygen therapy has emerged as a cost effective alternative to hospitalization, reducing the strain on medical facilities while improving patient outcomes. The availability of reimbursement policies in developed nations further facilitates access to these essential therapies. Pharmaceutical and device manufacturers are collaborating to create integrated care packages that include oxygen delivery systems alongside medication. This holistic approach ensures better adherence to treatment protocols. The persistent nature of chronic respiratory diseases guarantees a steady stream of new patients requiring oxygen support, thereby sustaining market growth over the long term.
Technological Advancements in Portable Oxygen Concentrators
Innovation in portable oxygen concentrator technology significantly propels the oxygen therapy market by enhancing patient mobility and independence. Traditional oxygen tanks are heavy and require frequent refilling, which restricts patient activity and social engagement. Modern portable concentrators utilize advanced sieve bed technology to extract oxygen from ambient air, offering a continuous supply without the need for refills. According to the American Lung Association, over 1.5 million Americans use supplemental oxygen therapy due to various breathing issues. These devices weigh as little as 2 kilograms, allowing patients to travel and participate in daily activities with minimal burden. The integration of pulse dose technology delivers oxygen only during inhalation, conserving battery life and extending usage duration. Smart connectivity features enable devices to transmit usage data to healthcare providers, facilitating remote monitoring and timely interventions. Manufacturers are focusing on noise reduction and ergonomic designs to improve user comfort and acceptance. The development of longer lasting lithium ion batteries supports extended outdoor use, addressing a key limitation of earlier models. Regulatory approvals for new portable models accelerate their entry into the market, providing patients with more choices. The shift toward patient centric care emphasizes quality of life, making portable solutions the preferred choice for active individuals. This technological evolution expands the addressable market beyond bedridden patients to those seeking an active lifestyle despite respiratory limitations.
MARKET RESTRAINTS
High Cost of Advanced Oxygen Delivery Systems
The substantial financial burden associated with acquiring and maintaining advanced oxygen therapy equipment is a significant barrier to market penetration. High end portable oxygen concentrators and liquid oxygen systems involve considerable upfront costs that may not be fully covered by insurance plans in all regions. According to the Centers for Medicare and Medicaid Services, beneficiaries typically pay 20% of the Medicare approved amount for durable medical equipment after meeting their deductible. This financial strain discourages patients from upgrading to newer, more efficient devices, forcing them to rely on older, less convenient technologies. Maintenance costs including filter replacements, battery upgrades, and professional servicing add to the long term expenditure. In developing economies, the lack of robust reimbursement frameworks limits access to even basic oxygen concentrators. Healthcare providers may hesitate to prescribe expensive portable units if patients cannot afford them, which is leading to suboptimal treatment adherence. The economic disparity between urban and rural populations further exacerbates accessibility issues. Small scale distributors struggle to compete with large manufacturers who can offer bundled pricing, limiting market diversity. Budget constraints in public healthcare systems often prioritize acute care over chronic disease management tools, restricting procurement volumes. Patients may resort to illicit or unregulated sources of oxygen equipment to save money, posing safety risks. This economic hurdle stifles the adoption of innovative technologies and slows overall market growth.
Strict Regulatory Compliance and Approval Processes
Navigating the complex regulatory landscape for medical devices imposes significant delays and costs on manufacturers in the oxygen therapy market. Agencies such as the Food and Drug Administration and the European Medicines Agency require rigorous clinical testing and documentation to ensure device safety and efficacy. According to the International Organization for Standardization, compliance with ISO standards for medical electrical equipment involves extensive quality control measures and periodic audits. These stringent requirements extend the time to market for new products, delaying revenue generation for innovators. Changes in regulatory guidelines necessitate costly redesigns and re certification processes, straining research and development budgets. Small and medium sized enterprises often lack the resources to navigate these bureaucratic hurdles effectively, limiting competition and innovation. Post market surveillance obligations require continuous monitoring of device performance and adverse events, adding to operational overhead. Variations in regulatory requirements across different countries complicate global expansion strategies for manufacturers. Delays in approval can result in missed market opportunities and reduced competitive advantage. The fear of non-compliance penalties encourages conservative product development, potentially stifling breakthrough innovations. Healthcare providers may also face liability concerns when prescribing newer devices that have not yet established a long term safety record. This regulatory caution slows the adoption of cutting edge technologies and maintains reliance on traditional, proven methods.
MARKET OPPORTUNITIES
Integration of Telemedicine and Remote Patient Monitoring
The convergence of oxygen therapy with telemedicine platforms is a promising opportunity for the global oxygen therapy market. Smart oxygen concentrators equipped with Internet of Things sensors can transmit real time data on oxygen saturation, flow rates, and device status to healthcare providers. For instance, healthcare institutions implementing remote patient monitoring experienced a substantial 38% decrease in hospital admissions. This data driven approach allows clinicians to adjust oxygen prescriptions dynamically based on actual usage patterns rather than periodic clinic visits. Early detection of deviations in oxygen levels enables proactive interventions, preventing acute exacerbations and emergency room visits. Insurance providers are increasingly recognizing the cost savings associated with remote monitoring, leading to broader reimbursement coverage. Technology companies are partnering with medical device manufacturers to develop user friendly apps that empower patients to manage their therapy actively. The integration of artificial intelligence algorithms can predict potential health declines, prompting timely medical attention. This digital ecosystem enhances patient engagement and adherence to treatment protocols. Healthcare systems benefit from reduced workload and improved resource allocation. The scalability of telemedicine solutions makes them suitable for large patient populations, particularly in remote areas. This technological synergy creates new revenue streams for device manufacturers through software subscriptions and data analytics services.
Expansion into Emerging Markets with Improving Healthcare Infrastructure
Emerging economies in Asia Pacific, Latin America, and Africa offer substantial growth potential for the oxygen therapy market as healthcare infrastructure improves. Governments in these regions are investing heavily in expanding hospital capacity and primary care networks to address rising burdens of non-communicable diseases. According to the World Bank, health expenditure in low and middle income countries has grown steadily over the past decade, reflecting increased prioritization of healthcare access. The rising middle class in these regions has greater disposable income to spend on private healthcare and home medical equipment. Local manufacturing initiatives are reducing the cost of oxygen concentrators, making them more accessible to broader populations. International organizations and non-governmental entities are supporting oxygen supply chain improvements in rural areas. Partnerships between global device manufacturers and local distributors facilitate market entry and cultural adaptation of products. The increasing awareness of respiratory health issues drives demand for diagnostic and therapeutic services. Mobile health clinics equipped with portable oxygen devices are reaching underserved communities, expanding the customer base. Regulatory reforms in countries like India and Brazil are streamlining medical device approvals, accelerating product availability. This geographic expansion diversifies revenue sources for manufacturers and reduces dependence on saturated mature markets. The long term demographic trends in these regions promise sustained demand growth.
MARKET CHALLENGES
Supply Chain Vulnerabilities for Critical Components
The global oxygen therapy market faces significant challenges due to vulnerabilities in the global supply chain for essential components such as sieves, compressors, and electronic sensors. Disruptions caused by geopolitical tensions, natural disasters, or pandemics can lead to shortages of raw materials and finished goods. According to the Institute for Supply Management, a vast majority of manufacturing companies reported supply chain disruptions affecting production schedules and delivery times. The concentration of semiconductor production in specific regions increases the risk of bottlenecks for smart oxygen devices. Fluctuations in the price of aluminum and steel affect the manufacturing costs of concentrators and cylinders. Logistics challenges including port congestion and freight cost volatility further complicate distribution networks. Manufacturers struggle to maintain inventory levels without incurring excessive holding costs. Dependence on single source suppliers for specialized components creates single points of failure. Quality control issues in upstream suppliers can lead to recalls and reputational damage. The just in time manufacturing model, while efficient, lacks resilience against sudden shocks. Companies are forced to invest in dual sourcing strategies and regional warehousing, increasing operational complexity. These supply chain instabilities threaten the reliable availability of life saving equipment. Patients in remote areas are disproportionately affected by distribution delays. Ensuring supply chain continuity remains a critical operational challenge for industry participants.
Patient Adherence and Proper Usage Issues
Ensuring consistent patient adherence to oxygen therapy protocols remains a significant challenge to the global oxygen therapy market expansion. Many patients fail to use their oxygen devices for the prescribed duration due to discomfort, stigma, or lack of understanding. According to the European Respiratory Society, up to 50% of patients with Chronic Obstructive Pulmonary Disease do not adhere to long term oxygen therapy recommendations. Non adherence leads to poor health outcomes, increased hospitalizations, and higher healthcare costs, undermining the value proposition of the therapy. Physical discomfort from nasal cannulas or masks discourages prolonged use, particularly during sleep or physical activity. Psychological factors such as denial of disease severity or depression also contribute to non-compliance. Lack of adequate patient education and training results in improper device operation, which is reducing therapeutic efficacy. Healthcare providers often lack the time to provide comprehensive counselling during busy clinic visits. The complexity of modern devices with multiple settings can confuse elderly patients. Caregiver burden also plays a role, as family members may struggle to assist with equipment management. Addressing these behavioral and educational gaps requires multifaceted interventions including support groups and digital reminders. Failure to improve adherence limits the perceived effectiveness of oxygen therapy, potentially affecting reimbursement decisions. Manufacturers must design more intuitive and comfortable devices to mitigate these issues.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Covered | By Product Type, Application, End-User, and Region |
| Various Analyses Covered | Global, Regional & Country Level Analysis, Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview on Investment Opportunities |
| Regions Covered | North America, Europe, Asia Pacific, Latin America, Middle East, and Africa |
| Market Leaders Profiled | Respironics Inc., Teleflex Incorporated, AirSep Corporation, DeVilbiss Healthcare, ResMed Inc., Fisher & Paykel Healthcare Limited, Invacare, Essex Industries Inc., HERSILL S.L., and Weinmann Emergency Medical Technology. |
SEGMENTAL ANALYSIS
By Product Type Insights
The oxygen concentrators segment dominated the market by accounting for the highest share of the global market in 2025. The dominance of oxygen concentrators segment in the global market is attributed to their cost effectiveness and convenience for long term use. Unlike oxygen cylinders which require regular refilling and pose safety risks, concentrators extract oxygen from ambient air providing an unlimited supply as long as electricity is available. According to the American Lung Association, approximately 1.5 million Americans use home oxygen therapy with the majority relying on concentrators for daily management of chronic conditions. This widespread adoption is driven by the high prevalence of Chronic Obstructive Pulmonary Disease and the aging population requiring continuous care. The technological maturity of sieve bed technology ensures reliable oxygen purity levels between 90% and 95% meeting clinical standards. Healthcare providers prefer prescribing concentrators because they reduce the logistical burden of delivery services associated with compressed gas. Insurance reimbursement policies in developed nations often cover the rental or purchase of concentrators making them financially accessible. The ability to operate continuously without depletion makes them ideal for patients requiring overnight therapy. Manufacturers have focused on improving energy efficiency and noise reduction enhancing user comfort in domestic settings. The shift toward home healthcare further accelerates the demand for these stationary units. Their role as the primary source of oxygen for stable patients cements their market leadership. The integration of smart features allows for remote monitoring adding value for both patients and clinicians. This combination of reliability affordability and ease of use sustains their dominance.
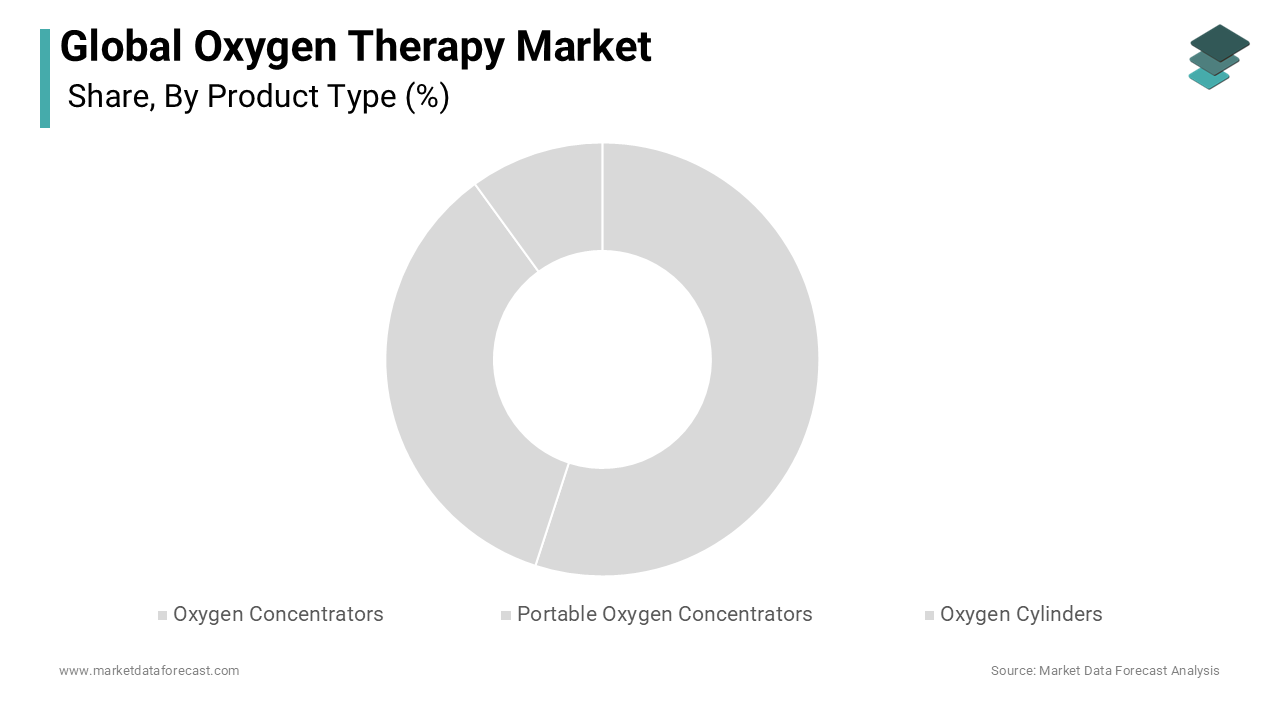
On the other side, the portable oxygen concentrators segment represent the fastest growing segment in the oxygen therapy market and is expected to grow at a CAGR of 9.1% during the forecast period owing to the growing desire among patients to maintain an active lifestyle despite respiratory limitations. According to clinical insights on respiratory care, patient quality of life is significantly improved when they can engage in social and physical activities outside the home. Portable units weigh significantly less than stationary models often less than 3 kilograms allowing for easy transport in cars or on public transit. Advances in battery technology have extended operating times enabling full day usage without recharging. The development of pulse dose technology delivers oxygen only during inhalation conserving battery life and extending device usability. Regulatory approvals for travel friendly devices have expanded their use in aviation and tourism sectors. Manufacturers are investing heavily in miniaturization and ergonomic design to enhance portability. The rising disposable income in emerging markets allows more patients to afford these premium devices. Insurance coverage for portable units is expanding recognizing their role in preventing hospital readmissions through better mobility. The stigma associated with visible oxygen tanks is reduced by the discreet design of modern portable concentrators. This psychological benefit encourages earlier adoption and consistent use. The convergence of technology and lifestyle needs drives this segment's accelerated expansion.
By Application Insights
The COPD segment held the dominant share of the global market in 2025. The growth of the COPD segment in the global market can be credited to its high global prevalence and severe impact on respiratory function. COPD causes irreversible airflow limitation requiring long term oxygen therapy to prevent hypoxemia and improve survival rates. According to the World Health Organization, COPD is responsible for approximately 3.23 million deaths annually making it the third leading cause of death worldwide. The progressive nature of the disease means that patients often require escalating levels of oxygen support over time. Smoking remains the primary risk factor although exposure to indoor air pollution from biomass fuel also contributes significantly in developing regions. Clinical guidelines strongly recommend long term oxygen therapy for patients with severe resting hypoxemia as it has been proven to extend life expectancy. The aging global population increases the pool of individuals susceptible to COPD exacerbations. Hospital discharge protocols frequently include prescriptions for home oxygen therapy to prevent readmission. The chronic nature of the condition ensures a steady and recurring demand for oxygen delivery devices. Pharmaceutical companies and device manufacturers collaborate on integrated care models focusing on COPD management. Public health campaigns aimed at smoking cessation help slow incidence rates but the existing patient base remains large. This sustained clinical necessity secures the segment's dominant position. The economic burden of COPD drives healthcare systems to invest in effective home care solutions.
However, the obstructive sleep apnea segment is the fastest growing application segment in the oxygen therapy market and is estimated to grow at a CAGR of 8.2% during the forecast period. While Continuous Positive Airway Pressure is the primary treatment supplemental oxygen is increasingly used for patients with comorbid respiratory conditions or residual hypoxemia. According to the World Health Organization, global obesity rates have doubled since 1980, significantly expanding the prevalence of conditions like sleep apnea. Obesity is a major risk factor for obstructive sleep apnea and this demographic shift expands the potential patient pool requiring sleep related respiratory support. Awareness campaigns have improved diagnosis rates leading to more patients seeking treatment. The integration of oxygen therapy with positive airway pressure devices addresses complex sleep disordered breathing. Technological advancements allow for seamless delivery of oxygen during sleep without disrupting therapy comfort. Home sleep testing kits have simplified diagnosis making it easier for patients to enter the treatment pathway. The recognition of obstructive sleep apnea as a risk factor for cardiovascular diseases drives aggressive management strategies. Insurance coverage for sleep disorder treatments is expanding reflecting their importance in preventive care. The growing acceptance of home based sleep solutions fuels market growth. This segment benefits from the broader trend toward personalized sleep medicine. The convergence of obesity trends and diagnostic improvements drives rapid expansion.
By End User Insights
The home healthcare segment led the market with the leading share of the global market in 2025. The growth of the home healthcare segment is primarily driven by the status of preferred setting for managing chronic respiratory conditions. The shift from hospital based care to home based management is driven by cost containment strategies and patient preference for comfort. According to healthcare administration data, home healthcare services have expanded steadily as hospitals focus on acute care and discharge patients earlier. Oxygen therapy is ideally suited for home use due to the availability of compact and user friendly devices. Patients report higher satisfaction and better quality of life when treated in familiar environments. Family members often serve as caregivers reducing the need for professional nursing visits. Reimbursement policies in many countries favor home care as it reduces the burden on expensive hospital resources. The development of telemedicine allows clinicians to monitor patients remotely ensuring safety and compliance. Home healthcare providers offer comprehensive services including equipment setup training and maintenance. This holistic support system enhances treatment adherence and outcomes. The aging population prefers to age in place driving demand for home medical equipment. Technological advancements in portable devices further facilitate home based therapy. The economic efficiency of home care ensures its continued dominance in the market. This setting allows for personalized care plans tailored to individual lifestyles.
However, the hospitals segment is predicted to showcase a healthy CAGR of 7.1% over the forecast period owing to the growing complexity of acute care and the rise in emergency admissions for respiratory distress. According to the World Health Organization, pneumonia and other acute respiratory infections remain leading causes of hospitalization globally. The aftermath of recent pandemics has heightened awareness of respiratory care capabilities in medical facilities. Hospitals are upgrading their central oxygen supply systems and acquiring high flow nasal cannula devices for critical care units. The integration of advanced monitoring systems requires compatible oxygen delivery infrastructure. Emergency departments are expanding capacity to handle surges in respiratory cases necessitating robust oxygen resources. Teaching hospitals are adopting the latest technologies for research and training purposes. The focus on reducing length of stay drives the use of efficient oxygen therapy to stabilize patients quickly. Investment in hospital infrastructure in emerging economies contributes to global growth. Regulatory standards for hospital safety mandate redundant oxygen supply systems. The need for precise oxygen titration in intensive care units drives demand for sophisticated devices. This institutional demand ensures steady market expansion. The critical role of hospitals in acute care sustains their growth trajectory.
REGIONAL ANALYSIS
North America Oxygen Therapy Market Analysis
North America dominated the market by capturing 36.3% of the global market share in 2025 and is likely to experience stable market growth over the next few years supported by advanced healthcare infrastructure and high adoption rates of portable devices. The region benefits from a highly developed healthcare infrastructure and favorable reimbursement policies. According to the Centers for Medicare and Medicaid Services, millions of beneficiaries receive coverage for home oxygen therapy driving consistent demand. The high prevalence of chronic respiratory diseases such as COPD and asthma in the United States and Canada creates a substantial patient base. Technological innovation is concentrated in this region with major manufacturers headquartered here. The adoption of portable oxygen concentrators is highest in North America due to high disposable income and active lifestyles. Strict regulatory standards ensure high quality and safety of medical devices. The presence of leading home healthcare providers facilitates efficient distribution and service. Government initiatives focusing on reducing hospital readmissions promote home oxygen therapy. The aging baby boomer population further accelerates market growth. Private insurance coverage complements public programs ensuring broad access. Research and development investments drive continuous product improvement. The mature market focuses on value added services and digital integration. This combination of factors maintains North America's leadership position.
Europe Oxygen Therapy Market Analysis
Europe is likely to witness steady expansion over the next few years driven by stringent environmental standards and robust public health frameworks. Europe occupies the second largest position in the global oxygen therapy market characterized by strong public healthcare systems and stringent regulatory frameworks. According to Eurostat, the aging population in Europe is growing rapidly increasing the need for long term care solutions. National health services in countries such as France and Italy provide comprehensive coverage for oxygen therapy equipment. The European Union’s medical device regulation ensures high safety and performance standards. There is a strong emphasis on energy efficient and environmentally friendly devices. Home healthcare is well established in Northern Europe while Southern Europe relies more on hospital based care. Cross border trade facilitates access to diverse products. Government initiatives to reduce carbon emissions influence device design. The prevalence of smoking in certain Eastern European countries drives higher disease rates. Reimbursement policies vary by country but generally support essential therapy. The focus on patient centered care promotes portable solutions. This balanced mix of public support and regulatory rigor sustains market stability.
Asia Pacific Oxygen Therapy Market Analysis
Asia Pacific is likely to exhibit rapid market acceleration over the next few years fueled by rising industrialization and expanding healthcare investments. Rapid industrialization and urbanization have led to increased air pollution contributing to respiratory diseases. According to the World Health Organization, several Asian countries have some of the highest rates of COPD globally. Rising disposable incomes in China India and Southeast Asia enable more patients to afford private healthcare and home equipment. Governments are investing heavily in healthcare infrastructure to meet growing demand. Local manufacturing is reducing costs making devices more accessible. The large population base provides immense growth potential. Awareness campaigns are improving diagnosis rates. The expansion of private insurance coverage supports market growth. Technological adoption is accelerating with mobile health solutions gaining traction. The prevalence of smoking in countries like Indonesia and China drives demand. Medical tourism in Thailand and Singapore boosts high end device sales. Urbanization leads to lifestyle changes increasing obesity and sleep apnea rates. This dynamic environment creates diverse opportunities for manufacturers. The region’s growth trajectory outpaces mature markets.
Latin America Oxygen Therapy Market Analysis
Latin America is likely to show progressive market development over the next few years supported by improving healthcare access and rising chronic disease management programs. Latin America represents a developing market for oxygen therapy with significant growth potential driven by improving healthcare access. According to the Pan American Health Organization, non-communicable diseases are rising due to lifestyle changes and aging populations. Public healthcare systems are expanding coverage for chronic disease management. Economic challenges limit access to premium devices but basic concentrators are becoming more common. Local distributors are partnering with international manufacturers to improve supply chains. The prevalence of respiratory infections in tropical climates drives acute care demand. Urban centers are seeing increased adoption of home healthcare services. Government programs aim to reduce inequality in healthcare access. The growing middle class is investing in personal health devices. Regulatory frameworks are evolving to ensure device safety. Cultural preferences for family care support home based therapy. Infrastructure improvements in rural areas are expanding market reach. This emerging market offers long term growth opportunities. The focus on basic access drives volume growth.
Middle East and Africa Oxygen Therapy Market Analysis
Middle East and Africa is likely to experience gradual market progression over the next few years driven by targeted health infrastructure investments and increasing chronic care awareness. The Middle East has high rates of smoking and genetic respiratory conditions driving demand. According to the World Bank, healthcare spending in Gulf Cooperation Council countries is increasing significantly. Africa faces challenges with infectious diseases like pneumonia and tuberculosis requiring oxygen support. Initiatives by global health organizations are improving oxygen supply in African hospitals. Lack of infrastructure limits home care adoption but hospital demand is rising. South Africa and Egypt have more developed markets with private healthcare sectors. Government investments in health infrastructure are gradual but steady. The prevalence of indoor air pollution from cooking fuels affects respiratory health in rural areas. International aid supports equipment procurement in low income countries. Local manufacturing is limited leading to reliance on imports. Regulatory harmonization efforts are underway to improve standards. The market is fragmented but shows signs of consolidation.
COMPETITIVE LANDSCAPE
The competition in the oxygen therapy market is characterized by established global manufacturers and specialized niche players competing on technology and service quality. Leading companies differentiate themselves through innovation in portable device design digital connectivity and patient support services. The market exhibits high barriers to entry due to strict regulatory requirements and the need for clinical validation. Established brands leverage their extensive distribution networks and brand reputation to secure contracts with healthcare providers and insurers. Regional players often focus on cost effective solutions for emerging markets where price sensitivity is high. The shift toward home healthcare intensifies competition in developing user friendly and reliable devices. Collaboration with telemedicine platforms creates new avenues for value added services. Supply chain resilience has become a critical factor following recent global disruptions influencing procurement strategies. Local manufacturing capabilities are valued for ensuring timely delivery and reducing costs. The emphasis on total lifecycle cost and patient outcomes drives purchasing decisions. Customer retention is achieved through comprehensive maintenance and support programs. The market remains dynamic with continuous advancements in battery technology and sensor integration shaping competitive dynamics.
KEY MARKET PLAYERS
Some of the prominent companies operating in the global oxygen therapy market include
- Respironics Inc.
- Teleflex Incorporated
- AirSep Corporation
- DeVilbiss Healthcare
- ResMed Inc.
- Fisher & Paykel Healthcare Limited
- Invacare
- Essex Industries Inc.
- HERSILL S.L.
- Weinmann Emergency Medical Technology
Top Players in the Market
Philips
Philips is a global leader in the oxygen therapy market providing a comprehensive portfolio of respiratory care solutions including stationary and portable oxygen concentrators. The company focuses on connected health technologies that enable remote patient monitoring and personalized care management. Philips has recently strengthened its position by integrating artificial intelligence into its sleep and respiratory care devices to enhance diagnostic accuracy and treatment efficacy. The company actively collaborates with healthcare providers to develop integrated care pathways for chronic respiratory diseases. Its commitment to sustainability drives the development of energy efficient devices that reduce environmental impact. Philips leverages its strong brand reputation and extensive distribution network to reach patients globally. These strategic initiatives reinforce its leadership in delivering innovative and patient centric respiratory solutions.
ResMed
ResMed is a prominent player in the oxygen therapy market specializing in medical devices for sleep disordered breathing and chronic respiratory disease management. The company offers a wide range of oxygen concentrators and delivery devices designed for home and clinical use. ResMed has recently expanded its digital health platform AirView which allows clinicians to monitor patient adherence and therapy outcomes remotely. This data driven approach improves patient engagement and clinical decision making. The company invests heavily in research and development to create quieter and more comfortable devices. ResMed strengthens its market presence through strategic partnerships with home healthcare providers and insurance payers. Its focus on innovation and customer support ensures high levels of patient satisfaction and loyalty.
Inogen
Inogen is a key innovator in the oxygen therapy market known for its lightweight and portable oxygen concentrators. The company focuses on enhancing patient mobility and independence through compact and user friendly designs. Inogen has recently introduced new models with extended battery life and improved pulse dose technology to meet the needs of active patients. The company emphasizes direct to consumer sales channels alongside traditional distributor networks to increase market accessibility. Inogen actively engages in educational campaigns to raise awareness about the benefits of portable oxygen therapy. Its agile manufacturing processes allow for rapid adaptation to changing market demands. These efforts position Inogen as a preferred choice for patients seeking lifestyle freedom and reliable oxygen support.
Top Strategies Used by the Key Market Participants
Key players in the oxygen therapy market prioritize product innovation to enhance portability and connectivity. Companies invest in research and development to create lighter and quieter devices with longer battery life. Strategic partnerships with healthcare providers and insurers facilitate broader access and reimbursement coverage. Expansion into emerging markets through local manufacturing and distribution agreements drives global growth. Digital health integration enables remote monitoring and personalized care management improving patient outcomes. Focus on sustainability leads to the development of energy efficient and eco friendly products. Mergers and acquisitions help companies expand their product portfolios and technological capabilities. Customer education and support programs enhance adherence and brand loyalty. Regulatory compliance ensures safety and quality standards are met globally. These strategies collectively strengthen competitive positions and drive sustained market expansion
RECENT MARKET HAPPENINGS
- In January 2024, Sechrist Industries launched two products: the eHEAL software system and the 3300HM Hyperbaric Chamber, which enhance hyperbaric oxygen therapy. The new offerings combine advanced technology with user-friendly features, aiming to improve the efficiency and safety of hyperbaric treatments.
- In July 2023, Emerson launched the ASCO Series 588 Stationary Oxygen Concentrator Manifold, the healthcare industry’s first turnkey manifold solution designed to optimize respiratory therapy device designs, accelerating product adoption in the market.
- In June 2022, Armstrong Medical announced the second-generation FD140i, a superior dual treatment flow driver that facilitates the transition from Continuous Positive Airway Pressure (CPAP) to high-glow oxygen therapy (HFOT).
- In November 2021, the United Nations Children’s Fund (UNICEF) and the UK government joined forces to develop a state-of-the-art oxygen concentrator specifically designed for low-resource environments. The oxygen concentrator is part of UNICEF’s COVID-19 campaign to fulfill the oxygen needs of critical care environments.
MARKET SEGMENTATION
This research report on the global oxygen therapy market has been segmented and sub-segmented based on the product type, application, end-user, and region.
By Product Type
- Oxygen Concentrators
- Portable Oxygen Concentrators
- Oxygen Cylinders
By Application
- Chronic Obstructive Pulmonary Disease
- Asthma
- Obstructive Sleep Apnea
- Respiratory Distress Syndrome
- Cystic Fibrosis
- Pneumonia
By End-user
- Home Healthcare
- Hospitals
By Region
- North America
- Europe
- Asia Pacific
- Latin America
- The Middle East and Africa