- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$3.55 BnMarket Estimate, 2026
$3.83 BnMarket Forecast, 2034
$6.97 BnCAGR, 2026–2034
7.78%Executive Summary: Global Surgical Power Tools Market
- Market Scope: Comprehensive global analysis of the surgical power tools sector, detailing product categories, technologies, device types, applications, distribution channels, and regional insights.
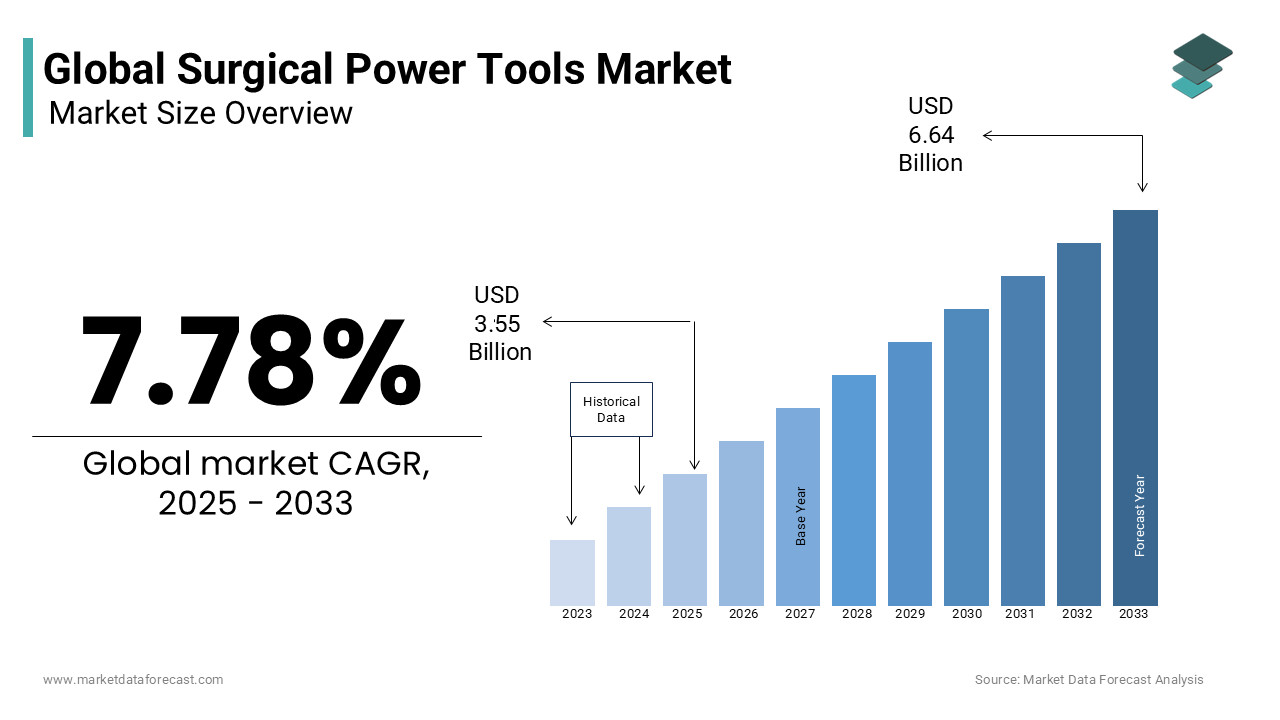
- Market Valuation: Valued at USD 3.55 billion in 2025, reaching USD 3.83 billion in 2026, and projected to expand to USD 6.97 billion by 2034, growing at a robust CAGR of 7.78% from 2026 to 2034.
- Primary Growth Drivers: Increasing prevalence of neurological disorders, aging global population, rising bone procedures like joint arthroplasty, and technological advances in electric-powered surgical instruments.
Key Market Segment Metrics
| Category | Leading Segment (Base Position) | Fastest-Growing / High-Growth Segment |
|---|---|---|
| By Product | Handpiece (dominated in 2025 due to smooth delivery, automatic power optimization, and high compatibility) | Disposables & Accessories (fastest-growing due to safety and high procedure frequencies) |
| By Technology | Electric-operated power tools (held dominant share providing continuous torque under high load) | Battery-driven power tools (high-growth segment driven by mobility and enhanced safety profile) |
| By Device Type | Large Bone Power Tools (captured major market share in 2025, driven by osteoarthritis and hip/knee surgeries) | Small & Medium Bone Power Tools (projected at high CAGR, propelled by specialized extremities procedures) |
| By Application | Orthopedic Surgery (market leader in 2025, backed by rising joint replacements and trauma cases) | Neurology & ENT Surgery (key growth segments driven by minimally invasive precision tool adoption) |
| By End-User | Hospitals (dominated market share backed by high patient volume and surgical investments) | Ambulatory Surgical Centers (ASCs) (projected at highest CAGR due to outpatient shift) |
| By Region | North America (market leader in 2025, backed by advanced medical infrastructure and high healthcare expenditure) | Asia-Pacific (predicted to register the highest CAGR due to urbanizing healthcare, aging demographics, and rising joint procedures) |
Major Market Players & Industry Landscape
Market Structure: Highly competitive landscape driven by strategic partnerships, distribution agreements, collaborations, and advanced product innovations.
Key Companies: Aesculapius Farmaceutici Srl, Anthrax Solution, Aygun Surgical Instrument, B. Braun Melsungen Ag, Ceterix Orthopaedics, De Soutter Medical, Medtronic Plc, Stryker Co, and Zimmer Biomet.
 Download Free Sample Report
Global Surgical Power Tools Market Size
The global surgical power tools size was valued at USD 3.55 billion in 2025 and is anticipated to reach USD 3.83 billion in 2026 from USD 6.97 billion by 2034, growing at a CAGR of 7.78% during the forecast period from 2026 to 2034.
Surgical power tools are powered instruments used in various surgical procedures to cut, fixate, shape, and dissect bone and emulsify, aspirate, and split soft tissue. However, these instruments are generally utilized for various purposes, including surgery on bone or bone fragments. These power tools are also used for screwing, reaming, drilling, and other operations. It includes a handpiece, disposables, and various extras. Sports medicine, reconstructive and extremities surgery, spinal, neurosurgery, and ENT (ear, nose, and throat) operations use surgical power tools. Electric handpieces and air-driven handpieces are the two most common surgical handpieces; however, due to the rapid research and development activities, high-torque electric handpieces have also been developed. Orthopedic surgery, ENT surgery, neurology surgery, dental surgery, and cardiothoracic surgery are a few of the major surgical procedures that can benefit from these technologies. The development of such power instruments has transformed surgical techniques by making the entire procedure more efficient and flawless. Surgical power tools are medical instruments that operate with an additional power source. Surgical power tools let surgeons conduct specific tasks during a surgical procedure, such as changing biological tissue or gaining access to examine an organ.
MARKET DRIVERS
The growing incidence of neurological disorders and the aging population primarily drive the surgical power tools market growth.
The increasing prevalence of neurological disorders is majorly driving the market growth because neurological disorders lead to significant death and disability causes across the globe. Also, due to its beneficial factors, such as improved reliability, high performance, and a longer life cycle, there has been a significant increase in the adoption of surgical power tools over the forecast period. Furthermore, the growing geriatric population across the globe is considered one of the key growth contributors to the market. Because the senior population is more suspectable to various neurological disorders, and in recent years, there has been a significant increase in the number of health disorders such as osteoarthritis, hip fractures, and osteoporosis. As a result of this circumstance, the number of substantial bone procedures such as hip and knee arthroplasty has increased. Therefore, the worldwide surgical power tools market is expected to witness an upward sales curve over the forecast period.
In addition, the advanced technological advancements in the healthcare sectors and the growing adoption of innovative surgical power tools, large bone orthopedic saws, arthroscopic shavers, surgical staplers, powered ENT devices, and surgical robots are accelerating the market growth. Pneumatic surgical drills are frequently replaced with electrically powered neurosurgery drills. This is due to their low cost and self-sufficient power system; electric motors are expected to be in high demand in the following years.
Moreover, increasing investments and funding by the government and private organizations on research and development activities and the advancement of healthcare infrastructure support market growth. Therefore, rising research and development activities are expected to provide lucrative growth opportunities for manufacturers to introduce new products into the market.
MARKET RESTRAINTS
On the other hand, the high cost of surgical devices is the primary concern for market growth. Other constraints limiting market growth include the high cost of power tool repair and replacement parts and changes in raw material costs.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Covered | By Product, Technology, Devices Type, Application, Distribution, End-User & Region |
| Various Analyses Covered | Global, Regional & Country Level Analysis, Segment-Level Analysis; DROC, PESTLE Analysis, Porter's Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Regions Covered | North America, Europe, APAC, Latin America, Middle East & Africa |
| Market Leader Profiled | Aesculapius Farmaceutici Srl, Anthrax Solution, Aygun Surgical Instrument, B. Braun Melsungen Ag, Ceterix Orthopaedics, De Soutter Medical, Medtronic Plc, Stryker Co, and Zimmer Biomet. |
SEGMENTAL ANALYSIS
By Product Insights
Based on the product, the handpiece segment accounted significant share of the global surgical power tools market in 2025 and it is likely to continue its dominance during the forecast period. The handpiece product segment is driven owing to its beneficial factors such as smooth surgical delivery, automatic power optimization, and high compatibility.
By Technology Insights
Based on technology, the electric-powered power tools segment commanded a substantial market share since this instrument provides continuous torque even under high resistance and load. Furthermore, by introducing electrically operated power tools, enhanced safety precautions associated with accidental accidents have been reduced, accelerating the market expansion.
By Device Type Insights
Based on the device type, the large bone power tools held a significant share in 2023 in the global surgical power tools market and are anticipated to continue the dominating trend during the forecast period owing to the increasing prevalence of osteoarthritis, hip fractures, osteoporosis, and other significant bone injuries. In addition, however, the rising number of knee arthroplasty procedures, among others, is creating a lucrative development opportunity for the market.
By Application Insights
Based on the application, orthopedic surgery is projected to record a considerable share in the market during the forecast period in the global surgical power tools market due to the growing adoption of minimally invasive surgical procedures and the growing number of road accidents and sports.
By Distribution Channel Insights
Based on the distribution channel, the direct tender segment is likely to register a healthy share during the forecast period of low-cost device procurement and large dependence of hospitals among other end users on direct tenders.
By End-User Insights
Based on the end-user, the hospital segment dominated most of the market share in the global market due to the increasing patient population, rising number of surgeries, and high healthcare investments.
REGIONAL ANALYSIS
Geographically, the North American market dominated the global surgical power tools market in 2023 and it is anticipated to continue its dominance throughout the forecast period. The regional market growth is driven by the growing healthcare sector, the presence of advanced healthcare infrastructure, and favorable reimbursement policies. In addition, the presence of significant market players and the global level leading countries such as the United States and Canada are expanding the regional market growth. The United States is the primary growth contributor in the region. Technological advancements, high healthcare expenditure, and leading manufacturing companies are fuelling market growth. On the other hand, Canada is estimated to record a promising share in the market during the forecast period.
Europe was the second-largest market in the global surgical power tools market in 2020, and it is estimated to account for a substantial share during the forecast period. The increasing number of Orthopedic surgeries, growing demand for effective surgical power tools, and the evolving healthcare sector. Further, emerging countries such as Germany, the UK, Italy, France, and Spain are the growth contributors in the region. The UK is anticipated to register a prominent share in the European surgical power tools market. The factors such as increasing investments in research and development activities, the growing need for surgical power tools and the geriatric population and neurological disorders are boosting the market growth.
The Asia Pacific is projected to grow significantly during the forecast. Rising urbanization, healthcare sector improvement, and favorable reimbursement policies propel market growth. There has been a significant increase in health disorders such as osteoarthritis, hip fractures, and osteoporosis across the region in recent years. As a result of this scenario, the number of significant bone procedures such as hip and knee arthroplasty has increased. In addition, countries such as China, Japan, and India significantly contribute to the APAC regional market growth.
China accounted for the largest market share in the APAC surgical power tools market, and it is expected to record a substantial share in this region during the forecast period. The growing geriatric population, increasing prevalence of orthopedic disorders and technological advancements in the sector boost the market growth.
Further, the Indian market is projected to grow at a promising rate in the coming period. Increasing government initiatives through medical awareness programs, improving the healthcare sector, and enhancing industrial manufacturing facilities and infrastructure improvement are contributing to the market growth in the country.
KEY MARKET PARTICIPANTS
Some of the companies that are playing a dominating role in the global surgical power tools market include
- Aesculapius Farmaceutici Srl
- Anthrax Solution
- Aygun Surgical Instrument
- B. Braun Melsungen Ag
- Ceterix Orthopaedics
- De Soutter Medical
- Medtronic Plc
- Stryker Co
- Zimmer Biomet
RECENT HAPPENINGS IN THIS MARKET
- In June 2021, Stryker announced a collaboration with Texas Health Hospital Mansfield. The hospital will use the whole Stryker product line to help it on its quest to eradicate harm in the operating room for both healthcare providers and patients and this aids the company's future sales growth.
- Beijing, China, 25 October 2019 - Johnson & Johnson Medical (Shanghai) Ltd. Made an agreement for a co-marketing and distribution deal and an R&D collaboration with TINAVI, the Chinese orthopedic robots industry leader. This collaborative partnership enables DePuy Synthes1, the orthopedics division of Johnson & Johnson Medical Devices Companies*, to deliver TINAVI's robotic spine and trauma surgery solutions to the highly competitive Chinese orthopedics implant market.
MARKET SEGMENTATION
This research report on the surgical power tools market is segmented and sub-segmented into the following categories.
By Product
- Handpiece
- Disposable
- Accessories
By Technology
- Electric-operated power tools
- Battery-driven power tools
- Pneumatic power tools
- Others
By Device Type
- Large Bone Power Tools
- Small Bone Power Tools
- Medium Bone Power Tools
- Others
By Application
- Dental surgery
- Orthopedic surgery
- ENT surgery
- Cardiothoracic
- Surgery
- Neurology surgery
- Others
By Distribution Channel
- Direct Tenders
- Third-Party Distribution
By End-User
- Hospitals
- Ambulatory Surgical Centers (ASC)
- Clinics
- Others
By Region
- North America
- Europe
- Asia-Pacific
- Latin America
- Middle East and Africa