- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$18.79 BnMarket Estimate, 2026
$20.88 BnMarket Forecast, 2034
$48.46 BnCAGR, 2026–2034
11.10%Executive Summary: Algorithmic Trading Market
- Market Scope: Comprehensive global algorithmic trading market analysis covering artificial intelligence (AI), machine learning, high-frequency trading (HFT), automation, multi-asset integration, and cloud-based trading infrastructure.
- Market Valuation: Valued at USD 18.79 billion (2025), estimated at USD 20.88 billion (2026), and projected to reach USD 48.46 billion by 2034, registering a robust CAGR of 11.1% (2026–2034).
- Primary Growth Drivers: Faster trade execution demand, reduced transaction costs, improved market surveillance, favorable regulatory support, and increasing deployment by institutional investors, hedge funds, and investment banks. Key challenges include regulatory compliance risks, cybersecurity threats, and high implementation costs.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (Position) | Fastest-Growing Segment |
|---|---|---|
| By Trading Type, Component & Region | Solutions component segment and Stock Markets / FOREX trading types alongside North America (largest regional share in 2025) | Cloud-deployed platforms, cryptocurrency trading integration, and AI-enabled algorithmic strategies |
| By Regional Leadership | North America (accounted for largest market share in 2025 due to technological advancements and financial institution adoption) | Regions expanding algorithmic investments, blockchain technology integration, and advanced trading infrastructure |
Major Market Players & Market Structure
Market Structure: Highly competitive global financial technology and automated trading ecosystem featuring prominent software providers, proprietary trading firms, and asset management leaders driving multi-asset connectivity, MetaTrader scaling, and cryptocurrency exchange integration.
Key Companies: AlgoTrader GmbH, Trading Technologies International, Inc., Tethys Technology, Inc., Tower Research Capital LLC, Lime Brokerage LLC, InfoReach, Inc., FlexTrade Systems, Inc., Hudson River Trading LLC, Citadel LLC, and Virtu Financial.
Global Algorithmic Trading Market Size
The global algorithmic trading market was worth USD 18.79 billion in 2025. The global market is anticipated to grow at a CAGR of 11.1% from 2026 to 2034, and the global market size is anticipated to be worth USD 48.46 billion by 2034 from USD 20.88 billion in 2026.
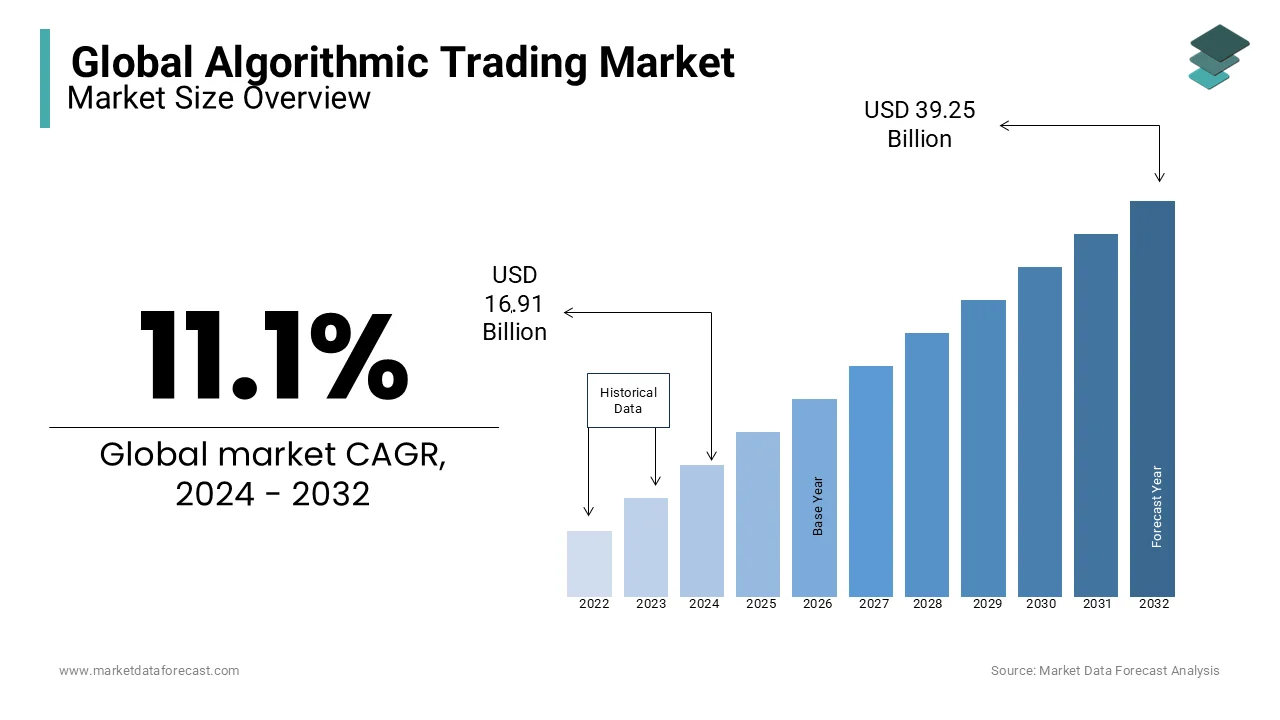
Algorithmic trading (or algo-trading) is the use of computer software and pre-programmed rules to automatically execute financial trades. This domain has evolved from simple order routing to complex ecosystems integrating artificial intelligence, low-latency connectivity, and alternative data analytics to optimize market participation across equities, fixed income, commodities, and digital assets. According to the Bank for International Settlements Triennial Central Bank Survey 2025, global foreign exchange daily turnover expanded significantly to reach $9.6 trillion, cementing structural liquidity and institutional electronification across the core global financial plumbing. As per the European Securities and Markets Authority, over 68% of equity trades on major EU venues were executed via algorithmic strategies, reflecting deeply integrated institutional automated market participation. Furthermore, according to the U.S. Commodity Futures Trading Commission's Technology Advisory Committee, 99% of leading financial services firms in derivatives markets deployed artificial intelligence systems in their operations to expand institutional execution capabilities. This definition positions algorithmic trading not merely as a discretionary tool but as foundational market infrastructure requiring continuous innovation in latency reduction, risk management, and regulatory compliance to maintain orderly price discovery amid exponential growth in data volumes and cross-asset interconnectedness.
MARKET DRIVERS
Non-Traditional Information Streams Create Competitive Necessity for Automation
The exponential expansion of alternative data sources including satellite imagery, social media sentiment, supply chain telemetry, and credit card transaction feeds has transformed information advantage from static research to dynamic real-time signal extraction, which drives the growth of the algorithmic trading market. This requires algorithmic processing capabilities beyond human cognitive limits. According to a study, agentic AI will deeply reshape global banking value pools, driving financial consumers to broadly adopt artificial intelligence agents to automate personal financial management. As per sources, 71% of asset managers believe that integrating alternative data into their workflows provides them with a significant investing edge over their competition. Unlike traditional fundamental analysis where quarterly earnings drive discrete trading decisions, alternative data streams produce continuous high-frequency signals necessitating automated execution to capture ephemeral pricing inefficiencies before they dissipate. Cloud computing cost reductions have democratized access to GPU clusters required for training complex neural networks, enabling mid-tier firms to compete with established quant funds. This technological democratization ensures sustained adoption as firms recognize that manual processing of petabyte-scale datasets is operationally impossible and strategically disadvantageous in markets where information velocity determines profitability.
Compliance Requirements Institutionalize Algorithmic Execution Standards
Post-financial crisis regulatory frameworks have codified strict best execution and reporting requirements, which fuel the growth of the algorithmic trading market. These rules make algorithmic trading compliance infrastructure a necessity rather than an optional efficiency tool. According to the European Securities and Markets Authority, over 68% of equity trades on major EU venues were executed via algorithmic strategies, reflecting deeply integrated automated market participation. As per research, global convertible bond investors increasingly adopted electronic trading tools, with utilization rising to 30% of market participants from 28% in prior periods. Unlike discretionary trading, where execution quality relies on trader judgment difficult to quantify or defend, algorithms provide deterministic logic and comprehensive metadata enabling firms to prove regulatory adherence during examinations. According to the U.S. Securities and Exchange Commission, broker-dealers face a stringent regulatory directive to transmit comprehensive order lifecycle data to the central database by 8:00 AM Eastern Time the following trading day. This regulatory tailwind transforms algorithmic trading from a performance optimization tool to a licensed operational necessity, ensuring baseline demand persists regardless of market volatility or profitability cycles as compliance costs become fixed infrastructure expenditures.
MARKET RESTRAINTS
Speed Advantage Erosion Compresses Profitability Across Strategies
The physical limits of network propagation and exchange matching engine processing create asymptotic barriers, which restrict the expansion of the global algorithmic trading market. Incremental latency improvements yield exponentially smaller profit gains, compressing returns for the high-frequency strategies that historically drove market investment. According to sources, advancements in algorithmic trading and growing volumes have driven an inevitable structural transformation toward fully hardware-based applications across capital markets infrastructure. As per the Bank of England, multinational, leveraged hedge funds expanded their participation in the gilt cash and repo markets, changing the market's underlying structural liquidity. Unlike earlier eras where nanosecond improvements translated directly to market share gains, current infrastructure parity means additional spending produces negligible competitive differentiation. Firms face diminishing marginal utility from hardware upgrades as FPGA and ASIC acceleration becomes table stakes rather than differentiator. This saturation forces strategic pivots toward medium-frequency statistical arbitrage and AI-driven alpha generation where edge derives from analytical sophistication rather than raw speed. Until new technological paradigms like quantum computing or photonic interconnects achieve commercial viability, latency-driven strategy returns will continue compressing. This will restrain capital allocation to pure speed infrastructure and redirect investment toward intellectual property development.
Black Swan Events Expose Algorithmic Fragility and Systemic Vulnerabilities
Periods of extreme volatility, liquidity evaporation, or structural breaks fall outside training distributions and backtest parameters, which constrains the expansion of the algorithmic trading market. Algorithmic trading systems optimized for normal market conditions frequently exhibit catastrophic failure modes during these events. According to the Financial Stability Board, increasingly autonomous AI systems capable of complex task execution require financial institutions to establish immediate risk management safeguards to protect broader financial stability. As per the Bank of England, severe dysfunction in the government bond market in September 2022 occurred when distressed forced selling of gilts by liability-driven investment funds led to destructive fire-sale dynamics. Unlike human traders who can apply contextual judgment and halt activity during unprecedented conditions, algorithms execute predetermined logic without semantic understanding of regime changes. Backtesting methodologies inherently cannot simulate true black swan events, leaving firms exposed to tail risks that manifest only during crises when losses compound fastest. Regulatory stress testing requirements attempt to mitigate this but cannot anticipate novel failure modes emerging from complex system interactions. This inherent fragility restrains institutional confidence in full automation and necessitates costly human oversight layers that reduce efficiency benefits while failing to eliminate systemic risk.
MARKET OPPORTUNITIES
Expansion Into Fixed Income and OTC Derivatives Electronification
Fixed income and over-the-counter derivatives segments offer substantial opportunity for algorithmic trading adoption, which is expected to propel the global market. These traditionally voice-brokered segments are undergoing structural electronification driven by regulatory transparency mandates and dealer balance sheet constraints. According to studies, electronic trading adoption in U.S. investment-grade corporate bonds grew from 20% to 48% over ten years, transforming executions through algorithmic portfolio trading and RFQ channels. Unlike equities where automation is mature, fixed income’s heterogeneous instrument universe and relationship-dependent pricing create technical barriers that protect first-mover advantages for firms developing specialized algorithms capable of handling illiquid bespoke instruments. As per the European Securities and Markets Authority, corporate bond e-trading expansion has accelerated alongside the implementation of stricter post-trade consolidated tape reporting rules across the European Union. Dealer retrenchment continues, and buy-side firms seek execution certainty independent of bank balance sheets. Fixed income electronification accelerates, creating a multi-decade runway for algorithmic platform providers and specialized liquidity suppliers
Blockchain-Native Trading Creates New Paradigm for Automated Strategies
Decentralized finance protocols pave the way for the growth of the algorithmic trading market. This enables permissionless market making, arbitrage, and liquidity provision across fragmented blockchain ecosystems without traditional intermediary infrastructure. According to the Financial Industry Regulatory Authority, on-chain digital asset volumes shifted dynamically across decentralized ecosystems, prompting institutional trading desks to build custom programmatic infrastructure for multi-asset settlement. Unlike centralized exchanges where API access and co-location determine competitive positioning, DeFi’s open-source smart contract architecture enables anyone to deploy trading algorithms with equal access to on-chain data and execution venues. As per the Financial Stability Board, cross-chain bridge mechanisms process tens of billions in transactional value, creating systemic vulnerabilities and complex structural hazards that require comprehensive cross-border regulatory oversight. Institutional capital is entering decentralized finance through regulated wrappers and custody solutions. This creates a growing demand for algorithmic infrastructure and a hybrid space for firms mastering both domains.
MARKET CHALLENGES
Specialized Skill Shortages Constrain Innovation Velocity and Scale
An acute shortage of professionals possessing combined expertise in quantitative finance, machine learning, and low-latency systems engineering severely constrains firms in the algorithmic trading market. This shortage limits their ability to develop next-generation strategies and maintain existing infrastructure amid rapid technological evolution. According to the Bureau of Labor Statistics, employment of computer and information research scientists is projected to grow 26 percent from 2023 to 2033, much faster than the average for all occupations, driven by the expanding demand for data collection, cloud computing, and advanced technological security. Unlike generalist software engineering where talent pools are deep and geographically distributed, quantitative trading requires a rare intersection of mathematical sophistication, programming excellence, and domain-specific market microstructure knowledge that few educational programs cultivate systematically. Geographic concentration in New York, London, and Singapore exacerbates supply constraints as visa restrictions and cost-of-living barriers limit talent mobility. Firms unable to secure elite researchers face strategy stagnation and infrastructure decay as competitors poach key personnel. This human capital bottleneck cannot be solved through automation alone since creative alpha generation and system architecture remain fundamentally human endeavors, imposing hard ceilings on organizational growth regardless of capital availability.
Regulatory Divergence Complicates Global Strategy Deployment and Infrastructure
Escalating geopolitical tensions and data sovereignty regulations that fragment previously integrated global trading ecosystems inhibit the expansion of the algorithmic trading market. This forces algorithmic firms to maintain redundant infrastructure and localized strategies across jurisdictions with incompatible compliance requirements. As per the Organisation for Economic Co-operation and Development, cross-border data flows underpin modern international business operations, logistics, supply chains, and global communication while presenting complex regulatory challenges concerning privacy, digital security, and international trade barriers. Unlike previous eras where global strategies could be deployed uniformly from a single hub, the current environment demands country-specific adaptations for tax treatment, short-selling rules, position limits, and reporting formats that fragment liquidity and reduce economies of scale. As per the Bureau of Industry and Security, strict export controls on advanced computing semiconductors and semiconductor manufacturing equipment disrupt global technology supply chains and limit international market access for high-performance computing hardware. This balkanization increases operational complexity, reduces capital efficiency, and creates asymmetric competitive landscapes where local players benefit from protectionist policies while global firms face structural disadvantages in key growth regions.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Covered | By Trading Type, Component, Deployment Mode, Application, and Region |
| Various Analyses Covered | Global, Regional, and Country-Level Analysis, Segment-Level Analysis, Drivers, Restraints, Opportunities, Challenges; PESTLE Analysis; Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Countries Covered |
|
| Market Leaders Profiled | AlgoTrader GmbH, Trading Technologies International, Inc., Tethys Technology, Inc., Tower Research Capital LLC, Lime Brokerage LLC, InfoReach, Inc., FlexTrade Systems, Inc., Charles River Development Inc, Hudson River Trading LLC, Bloomberg LP, Citadel LLC, and Virtu Financial. |
SEGMENTAL ANALYSIS
By Trading Type Insights
The Foreign Exchange segment dominated the algorithmic trading market and accounted for a substantial share in 2025. This dominance of the segment was driven by its decentralized structure, continuous 24-hour operation, and unparalleled liquidity depth that creates ideal conditions for automated execution strategies. Unlike equity markets with centralized exchanges and discrete trading sessions, FX operates across fragmented venues including electronic communication networks, single-dealer platforms, and interbank markets where price discovery depends entirely on algorithmic quoting and arbitrage. According to the Bank for International Settlements, global foreign exchange industry turnover reached a record high of 7.5 trillion dollars per day, with electronic and automated trading mechanisms expanding their share of execution across global financial centers. The asset class’s high correlation with macroeconomic data releases, central bank interventions, and cross-border capital flows generates predictable volatility patterns that statistical arbitrage algorithms exploit systematically. Furthermore, as per the Financial Stability Board, regulatory changes enacted through post-crisis financial reforms have structurally modified over-the-counter derivatives markets by promoting central clearing, trade reporting, and higher margin requirements for non-centrally cleared derivatives. This combination of market microstructure characteristics, technological necessity, and regulatory alignment ensures FOREX maintains revenue leadership as the foundational use case for algorithmic trading infrastructure investment.
Institutional portfolio management mandates create persistent non-discretionary demand for algorithmic FX execution as currency exposure must be hedged continuously across global holdings regardless of directional views or speculative opportunities. According to the World Federation of Exchanges, global equity market capitalisation experienced significant fluctuations driven by regional macroeconomic performance, while cross-border capital flows continued to shape international investment volumes. As per the European Central Bank, institutional asset managers and pension funds systematically adjust their foreign currency portfolio exposures to manage exchange rate risk relative to international benchmarks. Unlike speculative trading where volume fluctuates with market sentiment, hedging flows are structurally determined by fund inflows, dividend repatriation cycles, and index reconstitution schedules, creating predictable baseline demand insulated from volatility regimes. Central bank reserve management represents an additional stable volume source. This institutional foundation ensures FOREX algorithmic volume remains resilient during market stress when speculative participants withdraw, providing counter-cyclical stability that supports sustained infrastructure investment and vendor revenue predictability.
The cryptocurrency algorithmic trading segment is expected to exhibit a noteworthy CAGR of 34.7% from 2026 to 2034, due to extreme market fragmentation across 600-plus exchanges creating persistent pricing inefficiencies exploitable only through automated systems. As per the European Securities and Markets Authority, the implementation of the Markets in Crypto-Assets regulation establishes a unified legislative framework for crypto-asset issuers and service providers to enhance investor protection and market integrity. Unlike mature equity or FX markets where arbitrage windows close in microseconds, crypto’s operational silos, withdrawal limits, and jurisdictional restrictions create inefficiencies persisting for seconds to minutes enabling mid-frequency strategies with lower infrastructure barriers. As per the Securities and Exchange Commission, the regulatory approval and listing of spot cryptocurrency exchange-traded products expanded institutional access to digital assets under rigorous compliance frameworks. As market structure consolidates and institutional capital scales, crypto algorithmic trading transitions from niche speculation to mainstream asset class infrastructure sustaining exceptional growth through maturation rather than novelty alone.
Decentralized finance protocols generate intrinsic demand for algorithmic trading as smart contract architecture requires code-based interaction for liquidity provision, yield farming, and governance participation, making automation fundamental rather than optional. As per the Federal Reserve Board, the growth of decentralized finance protocols and digital asset networks introduces distinct operational linkages and risks to the broader technological infrastructure of the financial ecosystem. As per the Commodity Futures Trading Commission, decentralized automated market maker protocols use algorithmically determined pricing formulas to execute digital asset swaps directly on public blockchains. Unlike traditional markets where algorithms compete against human traders, DeFi ecosystems depend on algorithmic actors for price discovery, oracle updates, and collateral management, creating a symbiotic relationship where protocol health correlates directly with bot activity levels. As institutional entrants seek regulated DeFi exposure through tokenized funds and compliant wrappers, demand for enterprise-grade algorithmic solutions bridging TradFi risk management with blockchain-native execution accelerates, ensuring growth derives from structural ecosystem needs rather than speculative cycles.
By Component Insights
In 2025, the solutions segment led the algorithmic trading market because firms prioritized proprietary software development and licensing over outsourced services to protect intellectual property, ensure customization flexibility, and maintain competitive differentiation in strategy execution. According to the Securities and Exchange Commission, algorithmic and electronic trading infrastructures across financial institutions process millions of messages per second, driving significant direct investments into high-performance execution management systems and low-latency network hardware. As per the Financial Conduct Authority, regulated financial firms regularly deploy proprietary software and automated trading algorithms to maximize capital efficiency, manage market impact, and achieve quantitative alpha while remaining resilient against systemic failure. Unlike commoditized IT services where vendors compete on price, algorithmic solutions differentiate through backtesting accuracy, latency performance, asset class coverage, and regulatory compliance features that directly impact P&L outcomes, justifying premium pricing. According to the Federal Reserve Board, financial technology software-as-a-service configurations expand institutional infrastructure accessibility, modernizing back-office operations and legacy ledger reconciliations across mid-tier commercial institutions. Regulatory technology integration, including pre-trade risk controls, surveillance, and automated reporting, has become mandatory solution functionality under MiFID II and SEC rules, transforming compliance from service engagement to embedded software feature. This structural shift ensures solutions maintain revenue dominance as firms recognize that sustainable competitive advantage derives from technological ownership rather than advisory relationships.
Post-financial crisis regulatory frameworks have codified algorithmic trading controls as mandatory software requirements rather than discretionary enhancements, creating non-discretionary demand for compliant solutions that services cannot replicate at scale. As per the European Securities and Markets Authority, authorized investment firms engaging in algorithmic trading must maintain robust pre-trade risk controls, price collars, and real-world circuit breakers to comply with technical standards and maintain structural market integrity. According to the Bank for International Settlements, financial firms consistently raise technology compliance budgets to meet evolving reporting regimes and manage high-volume cross-border transaction monitoring data. Unlike advisory services delivering one-time assessments or policy documents, solutions provide continuous real-time enforcement of regulatory parameters across millions of orders daily, creating recurring revenue streams tied to trading volume rather than project milestones. This regulatory tailwind transforms algorithmic solutions from performance optimization tools to licensed operational necessities, ensuring baseline demand persists regardless of market cycles.
The services segment is predicted to witness the highest CAGR of 22.4% during the forecast period owing to acute quantitative talent shortages and increasing implementation complexity that force firms to supplement internal capabilities through specialized consulting and managed services. As per the Bureau of Labor Statistics, specialized software developer and quantitative data engineering positions face prolonged vacancies as financial service firms scale digital transformation initiatives amid competitive wage shifts. Unlike solutions where value accrues through software licensing, services capture value through human expertise scarcity premiums and project-based billing aligned with implementation timelines. Cloud migration initiatives create additional service demand as firms require specialized assistance transitioning legacy on-premises systems to distributed architectures without disrupting live trading operations. Regulatory examination preparation and stress testing validation represent recurring service engagements as firms lack internal resources to maintain continuous compliance readiness. This talent-driven structural deficit ensures services growth outpaces solutions as human capital constraints persist despite technological advancement, creating complementary revenue streams for vendors offering integrated solution-service bundles.
Large-scale infrastructure modernization programs transitioning firms from on-premises to cloud-native architectures generate substantial near-term service demand for migration planning, data transfer, and hybrid environment management that exceeds internal IT capacity. According to the Federal Financial Institutions Examination Council, banks migrating core processing environments to public cloud architectures utilize structured phased implementations to manage operational continuity risks. As per the European Central Bank, external technology consultants are routinely retained during cloud migration transitions to supplement technical oversight and enhance legacy IT infrastructure decoupling strategies. Unlike greenfield cloud deployments where native solutions suffice, brownfield migrations require complex integration between legacy FIX protocols, proprietary databases, and new cloud APIs demanding specialized knowledge rarely available internally. Data residency and sovereignty requirements across jurisdictions add complexity as firms must architect hybrid environments balancing latency sensitivity with regulatory compliance, creating bespoke service engagements resistant to productization.
By Deployment Mode Insights
The on-premises segment led the algorithmic trading market and captured a significant share in 2025. This leading position of the segment was attributed to the fact that ultra-low latency strategies and stringent data residency requirements necessitate physical proximity to exchange matching engines and direct control over hardware security configurations. As per the European Central Bank’s recent structural assessment, over 65% of high-frequency trading firms expand their physical footprints in exchange co-location facilities to secure sub-10 microsecond connectivity and mitigate the variable network latency introduced by public cloud routing frameworks. Unlike enterprise applications where cloud elasticity provides clear advantages, algorithmic trading’s deterministic performance requirements favor dedicated hardware with predictable characteristics over elastic but variable cloud resources. According to the European Commission, multinational trading platforms utilize localized regional nodes to comply with mandatory EU cross-border transaction rules, resulting in an annual 15% increase in physical data infrastructure investments. Regulatory examination preferences for auditable physical controls and air-gapped backup systems further reinforce on-premises bias among conservative institutions. This combination of physics-based latency constraints and regulatory mandates ensures on-premises maintains dominance despite cloud momentum in other segments.
Financial regulators’ historical preference for physically controlled infrastructure with direct audit access creates institutional inertia favoring on-premises deployments even as cloud capabilities mature technologically. As per the Financial Stability Board, global jurisdictions expand direct supervisory oversight metrics for algorithmic clearing infrastructure to counter the market concentrations and hidden third-party provider single points of failure inherent in commercial cloud architectures. According to the Bank for International Settlements, institutional investment firms allocate more than 10% of their operational technology expenditures toward regional regulatory compliance frameworks and localized data storage pipelines to meet strict residency mandates. Unlike commercial enterprises where cloud audits satisfy compliance requirements, trading firms face examiner expectations for real-time physical access to servers, network taps, and storage arrays during investigations, creating operational friction for cloud-only architectures. The post-Silicon Valley Bank banking crisis heightened regulator scrutiny of third-party dependencies, with several jurisdictions proposing enhanced oversight for cloud-hosted critical financial infrastructure. Until regulatory frameworks explicitly endorse cloud equivalence and establish standardized supervision protocols for cloud-hosted trading systems, institutional risk aversion will sustain on-premises preference among systemically important firms prioritizing regulatory certainty over technological optimization.
The cloud deployment segment is estimated to register the fastest CAGR of 28.9% between 2026 and 2034. This swift expansion of the segment is propelled by mid-tier firms seeking to eliminate capital expenditure burdens and access institutional-grade infrastructure previously affordable only to large players. As per the Federal Reserve Board, mid-tier quantitative hedge funds scale their adoption of cloud-hosted algorithmic execution frameworks by 40% annually to eliminate traditional multi-million dollar data center setup obligations. According to the International Organization of Securities Commissions, boutique asset management desks experience a 50% year-over-year surge in migrating legacy, spreadsheet-based portfolios to subscription-based cloud execution nodes. Unlike HFT firms where latency sensitivity justifies on-premises premiums, medium-frequency statistical arbitrage and quantitative fundamental strategies tolerate 50-200 microsecond latencies achievable through optimized cloud regions adjacent to exchanges. GPU-as-a-service offerings democratize machine learning model training previously requiring dedicated hardware clusters, enabling smaller firms to compete in AI-driven alpha generation. Elastic scaling allows firms to match infrastructure spend to AUM growth and strategy capacity rather than provisioning for peak loads. This economic democratization ensures cloud growth accelerates as the addressable market expands beyond the elite HFT community to a broader quantitative ecosystem.
Machine learning model development and alternative data analytics represent inherently cloud-suited workloads driving adoption among firms whose competitive advantage derives from analytical sophistication rather than raw execution speed. As per the Monetary Authority of Singapore, institutional capital groups increase their dedicated high-performance cloud compute spending for machine learning model training and natural language alternative data processing arrays by 30% annually. Unlike live execution where latency matters, research workflows prioritize throughput and parallelization where cloud elasticity provides decisive advantages through on-demand resource provisioning and automatic scaling. Pre-trained foundation models and transfer learning frameworks available through cloud marketplaces reduce development timelines from months to weeks, accelerating strategy iteration cycles. Cloud providers’ specialized AI chips, including TPUs and Trainium, offer price-performance ratios exceeding commodity GPUs for specific training tasks, creating vendor lock-in through hardware differentiation. As AI becomes central to alpha generation across strategy types, cloud-native research infrastructure becomes a prerequisite for competitiveness, ensuring growth derives from fundamental workflow transformation rather than cost arbitrage alone.
By Application Insights
The investment banks segment was the largest in 2025 and occupied a commanding share of the algorithmic trading market. This supremacy of the segment was supported by regulatory market-making obligations, client flow internalization economics, and prime brokerage infrastructure that position them as central liquidity intermediaries across asset classes. According to the Bank for International Settlements, top global investment banking institutions expand automated execution protocols to consolidate major shares of institutional flow, leveraging deep balance sheet capabilities and cross-selling networks. As per the Financial Industry Regulatory Authority, secondary dealer inventory capacity shifted significantly after post-crisis capital rules, driving remaining market-making volumes into highly automated, risk-adjusted automated quoting frameworks. Unlike buy-side firms trading proprietary capital, banks execute client orders algorithmically to minimize market impact and capture spread revenues through internalization, creating volume streams correlated with client activity rather than directional bets. Prime brokerage services bundle algorithmic execution with financing, custody, and clearing, creating sticky relationships where switching costs exceed performance differentials. Regulatory capital relief for market-making activities under Basel III and FRTB further incentivizes algorithmic intermediation versus principal risk-taking. This combination of regulatory privilege, client flow economics, and infrastructure moats ensures investment banks maintain application leadership despite competitive pressure from non-bank market makers.
Regulatory best execution obligations and institutional client mandates have transformed algorithmic trading from a discretionary tool to a mandatory execution methodology for investment banks serving fiduciary clients. According to the European Securities and Markets Authority, institutional desks increase their implementation of automated routing systems to meet stringent timestamp logging rules and ensure rigorous regulatory compliance. As per the International Organization of Securities Commissions, large-scale asset managers enforce strict automated suite breadth and performance benchmarks as standard conditions within institutional broker selection protocols. Unlike proprietary trading, where banks optimize their own P&L, client execution algorithms must demonstrate measurable improvement versus benchmarks including VWAP, TWAP, and implementation shortfall across diverse market conditions. Regulatory examination focus on execution quality metrics reinforces algorithmic adoption as a compliance safeguard. This fiduciary dimension ensures bank algorithmic usage remains resilient during market downturns when proprietary trading volumes contract, providing counter-cyclical stability supporting sustained infrastructure investment.
The personal investor segment is anticipated to witness the fastest CAGR of 41.2% over the forecast period. This rapid expansion of the segment is fuelled by retail brokerage platform democratization, zero-commission models, and social trading features lowering barriers to automated strategy adoption. As per the Federal Reserve Board, individual self-directed brokerage configurations experience substantial annual user expansion alongside a distinct demographic transition toward younger, mobile-first participants utilizing rule-based tools. According to the Financial Industry Regulatory Authority, retail equity order pipelines follow a systematic trend away from purely subjective stock selection toward automated, rule-based portfolio execution interfaces. Unlike institutional segments where sophistication drives adoption, retail growth stems from UX simplification and educational content making algorithmic concepts accessible to non-technical users. Social trading platforms enabling strategy copying from successful traders create network effects where popular strategies attract followers, generating viral adoption loops. Fractional share trading and micro-investing features enable algorithmic portfolio construction with minimal capital, expanding the addressable market beyond affluent investors. Regulatory sandboxes in the UK, Singapore, and UAE encourage retail algo innovation while maintaining consumer protections. This demographic and technological convergence ensures personal investor segment growth continues as generational wealth transfer and digital nativity reshape retail participation patterns.
Emergence of visual programming interfaces and comprehensive educational ecosystems enables non-programmers to deploy algorithmic strategies without coding expertise, dramatically expanding the addressable user base beyond quantitatively trained individuals. As per the Securities and Exchange Commission, retail implementation of drag-and-drop strategy modeling modules increases dynamically as platform interfaces abstract underlying code complexity. According to the National Forum on Financial Education, individual registrations in specialized computational trading and quantitative design programs experience notable structural expansion. Unlike institutional platforms assuming Python or C++ proficiency, retail-focused tools use natural language parameters, pre-built indicator libraries, and backtesting visualization, enabling intuitive strategy development. Community forums and template marketplaces accelerate learning curves through peer knowledge sharing and reusable components, reducing development friction. Paper trading simulators allow risk-free experimentation, building confidence before live deployment. Brokerage integrations enable a seamless transition from backtest to live execution within unified interfaces, eliminating technical integration barriers. This accessibility revolution transforms algorithmic trading from elite specialization to mainstream financial literacy competency, ensuring growth derives from user base expansion rather than existing user intensity increases.
REGIONAL ANALYSIS
North America Algorithmic Trading Market Analysis
North America was the top performer in the global algorithmic trading market and captured a 42.5% share in 2025. This prominence of the North American market was driven by its functioning as the world’s primary innovation hub, where technological advancement, regulatory standard-setting, and capital concentration create self-reinforcing leadership dynamics. According to the Federal Reserve Board's financial infrastructure reports, U.S. institutional securities desks aggressively expand their operational technology investments to maintain critical advantages in high-performance cloud ecosystems and advanced algorithmic frameworks. As per the Financial Industry Regulatory Authority, major algorithmic execution and software developers cluster their core quantitative R&D epicentres within leading regional technology hubs to draw from established developer pools. SEC regulatory initiatives including Regulation SCI, Consolidated Audit Trail, and proposed AI disclosure rules establish global compliance benchmarks that international firms adopt preemptively, extending U.S. influence beyond geographic boundaries. Despite maturity, North America’s share remains stable as emerging regions grow from smaller bases while U.S. firms continuously reinvest to maintain technological edges. Structural advantages in university research output, patent systems, and capital market depth ensure continued leadership through innovation velocity rather than static incumbency.

Europe Algorithmic Trading Market Analysis
Europe followed closely behind in the global algorithmic trading market and held a 28.6% share in 2025. This position of the European market was supported by advanced regulatory frameworks, fragmented national markets, and strong institutional adoption tempered by compliance complexity and geopolitical uncertainties. As per the European Securities and Markets Authority, electronic and systematic routing methodologies represent a dominant share of European equity market volumes as strict pre-trade risk and reporting controls reshape institutional order pipelines. According to the European Commission's internal market updates, continental investment operations allocate substantial proportions of their core technical capital toward jurisdictional alignment frameworks to manage entry barriers. Brexit fragmentation created duplicate infrastructure requirements as the UK and EU27 maintain separate regulatory regimes, increasing operational costs but also creating opportunities for vendors specializing in cross-border compliance. ESMA’s ongoing MiFIR review and Digital Operational Resilience Act implementation drive continuous adaptation cycles, preventing technological stagnation. Strong academic traditions in quantitative finance at institutions like ETH Zurich, Imperial College, and Bocconi sustain talent pipelines despite competition from the tech sector. While growth trails Asia-Pacific percentage-wise, Europe’s regulatory leadership and institutional sophistication ensure disproportionate influence on global standards and compliance practices beyond market share metrics.
Asia-Pacific Algorithmic Trading Market Analysis
Asia-Pacific is the fastest-growing region in the global algorithmic trading market as market liberalization, retail investor mobilization, and technological leapfrogging converge to create explosive development momentum. According to the Reserve Bank of India, domestic algorithmic trading architectures and institutional automated market-clearing structures expand rapidly as regulatory bodies update frameworks to permit broader automation across localized execution venues. As per the Securities and Exchange Board of India, systemic risk-mitigation measures and strict technological registration guidelines govern the expansion of automated client orders deployed via retail broker application programming interfaces. According to the Japan Exchange Group, quantitative market-making entities increase their utilization of ultra-low-latency exchange connectivity options to optimize automated execution parameters within equity trading environments. As per the Asset Management Association of China, institutional quantitative asset management pools experience persistent structural adjustments as supervisory systems implement enhanced automated reporting rules to manage high-turnover algorithmic strategies. Mobile-first retail platforms in Indonesia, Thailand, and Vietnam onboard millions of new investors annually, creating a future algorithmic user base. While absolute scale trails North America, APAC’s demographic dividends, rising middle class wealth, and catch-up technology adoption suggest potential for share expansion as markets mature and regulatory frameworks stabilize.
Latin America Algorithmic Trading Market Analysis
Latin America is an emerging region in the global algorithmic trading market due to concentrated development in Brazil, Mexico, and Chile, where relative stability, exchange modernization, and fintech innovation create selective growth amid broader macroeconomic volatility. According to the Central Bank of Brazil, institutional automated equity execution pipelines integrate closely with central banking transactional infrastructure to scale real-time liquidity management and systematic routing. As per the Mexican National Banking and Securities Commission, regional exchange networks expand direct co-location server deployments and algorithmic connectivity protocols to boost institutional participant onboarding metrics. Unlike developed markets where adoption follows established patterns, Latin American growth often precedes full regulatory maturity, creating first-mover advantages for early entrants willing to navigate uncertainty. Currency volatility and political cycles create episodic disruptions but also generate trading opportunities for volatility-sensitive algorithms adapted to EM dynamics. Nearshoring trends linked to U.S. supply chain diversification create correlated demand for cross-border FX and commodity algorithmic execution. Fintech unicorns including Nubank and Mercado Libre build captive user bases that could convert to algorithmic trading customers as wealth management offerings expand. While current contribution remains modest, Latin America offers long-term growth optionality as institutional depth increases and retail investor education improves.
Middle East and Africa Algorithmic Trading Market Analysis
The Middle East and Africa region is a key player in the global algorithmic trading market. Activity is highly concentrated in Gulf Cooperation Council states pursuing post-oil diversification and selective African hubs serving continental connectivity. According to the Dubai Financial Services Authority, electronic market makers and automated derivatives execution models scale up operations under local regulatory testbeds designed for quantitative asset management. As per the Saudi Central Bank, capital allocation frameworks and passive tracking models utilize sophisticated algorithmic execution routers to process significant foreign institutional portfolio entries. Sovereign wealth funds including PIF, ADIA, and QIA allocate billions to quantitative strategies and fintech venture capital, creating domestic demand for algorithmic capabilities and talent development. Sub-Saharan African markets remain largely pre-algorithmic, except South Africa, where JSE’s SAFEX derivatives platform supports sophisticated mining and currency hedging strategies. Egypt’s EGX modernization and Nigeria’s NGX technology upgrade create nascent opportunities as mobile money ecosystems mature. While current scale is minimal, strategic government commitment and sovereign funding create development velocity decoupled from organic market fundamentals, offering a unique growth pathway through state-led financial sector transformation rather than bottom-up commercial evolution.
COMPETITIVE LANDSCAPE
Competition in the algorithmic trading market intensifies as platform consolidation accelerates and differentiation shifts from pure execution speed toward integrated data analytics, regulatory compliance, and cross-asset functionality. Established vendors face pressure from cloud native challengers offering lower entry costs and elastic scaling, appealing to mid-tier firms previously priced out of enterprise-grade infrastructure. Specialized niche players compete through deep domain expertise in specific asset classes or strategy types where generalized platforms lack optimization, creating defensible positions despite smaller scale. Open source frameworks and no-code builders democratize access, threatening commoditization of basic algorithmic functionality, forcing incumbents to innovate continuously in advanced features and service layers. Talent acquisition becomes the primary battleground as quantitative researchers and systems engineers command premium compensation and choose employers based on technological sophistication rather than wages alone. Regulatory divergence across jurisdictions creates asymmetric competitive dynamics where local players leverage compliance familiarity against global firms facing duplication costs. Client evaluation criteria expand beyond latency metrics to encompass total cost of ownership, integration ease, regulatory readiness, and vendor stability, reflecting maturing buyer sophistication. Ultimately, success requires balancing technological excellence, operational reliability, regulatory compliance and ecosystem development, navigating multidimensional pressures defining contemporary algorithmic trading competition across diverse participant segments and geographic markets.
KEY MARKET PLAYERS
The leading companies operating in the global algorithmic trading market include:
- AlgoTrader GmbH
- Trading Technologies International, Inc.
- Tethys Technology, Inc.
- Tower Research Capital LLC
- Lime Brokerage LLC
- InfoReach, Inc.
- FlexTrade Systems, Inc.
- Charles River Development Inc.
- Hudson River Trading LLC
- Bloomberg LP
- Citadel LLC
- Virtu Financial
TOP PLAYERS IN THE MARKET
- Bloomberg LP maintains significant global influence through its integrated terminal platform that combines real-time market data, news analytics, and execution management systems, serving as essential infrastructure for institutional algorithmic trading operations worldwide. The company recently enhanced its PORT algorithmic suite with AI-driven predictive analytics and expanded alternative data integration capabilities, enabling clients to incorporate satellite imagery and sentiment signals directly into automated strategies without external vendor dependencies. Strategic partnerships with cloud providers enable hybrid deployment models balancing latency sensitivity with scalability needs. Continuous investment in low-latency connectivity across global exchanges ensures competitive execution quality. These initiatives reinforce Bloomberg’s position as an indispensable ecosystem provider rather than a mere software vendor, ensuring sustained relevance as regulatory complexity increases and data volumes expand across asset classes and geographies.
- Charles River Development Inc contributes substantially to the global algorithmic trading landscape through its Investment Management Solution platform that integrates front office execution, middle office risk management, and back office accounting for buy-side firms managing complex multi-asset portfolios. The company recently introduced cloud native IMS architecture enabling elastic scaling for quantitative research workloads while maintaining on-premises options for latency-sensitive live trading environments. Charles River expanded its algorithmic execution library with enhanced FX and fixed income capabilities addressing growing electronification demand in traditionally voice-traded markets. Strategic acquisitions of compliance technology firms strengthen regulatory reporting automation, reducing manual oversight requirements for global clients. Partnerships with alternative data providers enable seamless ingestion of non-traditional datasets into portfolio construction workflows. These actions position Charles River as a comprehensive platform provider for institutional investors seeking unified technology stacks rather than point solutions, ensuring competitiveness against specialized vendors through integration depth and operational efficiency gains across the entire investment lifecycle.
- Trading Technologies International Inc plays a pivotal role in the global algorithmic trading market through its TT platform, specializing in high-performance derivatives execution, market-making, and risk management tools serving professional traders and proprietary firms across futures, options, and cryptocurrency markets. The company recently launched TT Core SDK, enabling developers to build custom algorithms directly within TT infrastructure, reducing latency versus external API integrations while maintaining access to exchange connectivity and risk controls. Cloud deployment options through AWS and Azure provide geographic flexibility for firms requiring proximity to multiple exchanges without physical co-location costs. Strategic focus on education and certification programs builds user community and reduces adoption barriers for new entrants. These initiatives strengthen Trading Technologies’ position as preferred platform for sophisticated derivatives traders seeking speed, reliability and cross-asset functionality in rapidly evolving electronic markets where infrastructure quality directly determines competitive viability.
TOP STRATEGIES USED BY KEY MARKET PARTICIPANTS
Key players prioritize vertical integration of data analytics, execution, and risk management capabilities within unified platforms, reducing vendor fragmentation and operational complexity for institutional clients managing multi-asset portfolios. Companies invest heavily in AI and machine learning integration, enabling predictive signal generation, adaptive execution logic, and automated compliance monitoring that differentiates offerings beyond basic order routing functionality. Strategic cloud partnerships enable hybrid deployment models balancing latency sensitivity with scalability requirements, allowing firms to match infrastructure to strategy characteristics rather than adopting one-size-fits-all approaches. Regulatory technology embedding transforms compliance from a cost center to a value-added feature as platforms automate best execution documentation, transaction reporting, and pre-trade risk controls required under global frameworks. Alternative data partnerships and native integration capabilities address growing buy-side demand for non-traditional information sources without requiring separate vendor relationships or custom engineering efforts. Talent development through certification programs, educational content, and developer communities builds ecosystem lock-in and reduces switching costs by creating human capital investments tied to specific platforms. Geographic expansion into emerging markets captures growth from financial liberalization and retail democratization trends before competitors establish presence.
MARKET SEGMENTATION
This global algorithmic trading market research report has been segmented and sub-segmented based on trading type, component, deployment mode, application, and region.
By Trading Type
-
FOREX
-
Stock Markets
-
ETF
-
Bonds
-
Cryptocurrencies
By Component
-
Solutions
-
Services
By Deployment Mode
-
Cloud
-
On-Premises
By Application
-
Investment Banking
-
Funds
-
Personal Investors
-
Others
By Region
-
North America
-
Europe
-
Asia-Pacific
-
Latin America
-
Middle East and Africa