- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$284.1 BnMarket Estimate, 2026
$304.2 BnMarket Forecast, 2034
$525.4 BnCAGR, 2026–2034
7.07%Executive Summary: Global Cell Sorting Market
- Market Scope: Comprehensive global analysis of the cell sorting industry, covering technologies (FACS, MACS, microfluidics), products (cell sorters, reagents, consumables), applications (research, clinical), end-users (research institutes, biopharma companies, medical schools), and regional markets.
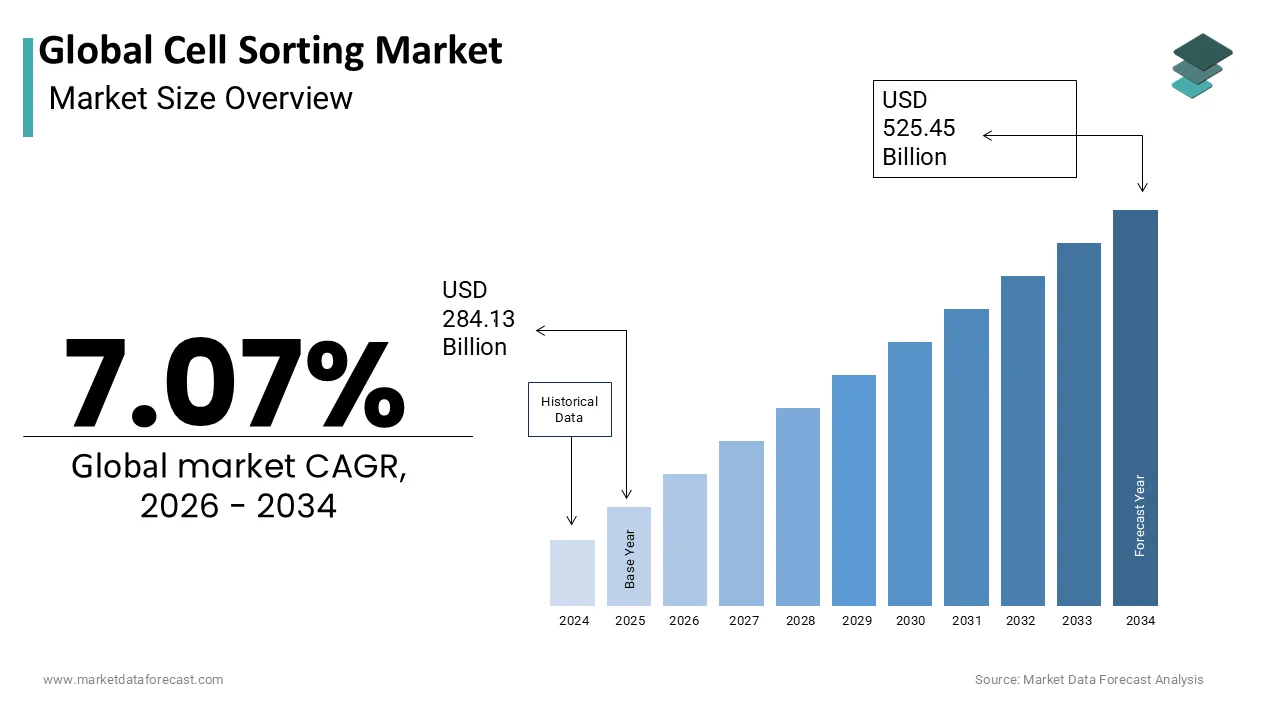
- Market Valuation: Valued at USD 284.13 billion in 2025, estimated at USD 304.22 billion in 2026, and projected to reach USD 525.45 billion by 2034, registering a compound annual growth rate (CAGR) of 7.07% from 2026 to 2034.
- Primary Growth Drivers: Escalating development and demand for personalized medicine, rising prevalence of chronic conditions like cancer and infectious diseases, technological breakthroughs in high-throughput cell sorting systems, and increasing R&D funding in the life sciences sector.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment Position | Fastest-Growing / Key Growth Segment |
|---|---|---|
| By Technology | Fluorescence-Activated Cell Sorting (FACS) / Droplet Sorting (dominates market share due to precise, high-speed, quantitative particle separation and versatile multi-application use) | Microfluidics (projected as the fastest-growing technology segment driven by innovative product designs, higher precision, and cost-effectiveness) |
| By Product & Application | Cell Sorters & Research Institutes (cell sorters command primary instrument revenues while research institutes capture the largest end-user share) | Reagents & Consumables / Clinical Applications (experiencing continuous repeat-purchase demand and rapid growth due to expanding diagnostic and therapeutic workflows) |
| By Region / Country | North America (leads global market share backed by massive biopharma investments, high chronic disease incidence, and advanced R&D infrastructure) | Asia-Pacific (exhibiting the highest growth potential driven by expanding government biotech initiatives, rising disposable incomes, and increased cancer research funding in China and India) |
Major Market Players & Market Structure
Market Structure: Highly competitive landscape featuring established global medical technology leaders focusing on software-driven single-cell analytics, automated cellular processing, and advanced microfluidic platform integrations.
Key Companies: Becton, Dickinson, and Company, Bio-Rad Laboratories, Inc., Beckman Coulter, Inc., Miltenyi Biotec GmbH, Affymetrix Inc., Sony Biotechnology, Inc., Sysmex Partec GmbH, Cytonome/ST, LLC, On-Chip Biotechnologies Co., Ltd., Union Biometrica, Inc., and Others.
 Download Free Sample Report
Global Cell Sorting Market Size
The Global Cell Sorting Market is projected to grow from USD 284.13 billion in 2025 to USD 304.22 billion in 2026 and reach USD 525.45 billion by 2034, registering a CAGR of 7.07% during the forecast period from 2026 to 2034.
Cell sorting is a laboratory process used to isolate specific types of cells from a mixed, heterogeneous population based on physical or chemical characteristics. The market comprises advanced laboratory instruments and technologies designed to isolate specific cell populations from heterogeneous mixtures based on physical or biological characteristics. These systems, including flow cytometers and magnetic activated cell sorters, are indispensable for immunology, oncology, and stem cell research. The critical nature of these tools is underscored by the rising global burden of complex diseases requiring precise cellular analysis. According to the World Health Organisation, cancer accounts for nearly 10 million deaths annually, driving the need for high-purity cell isolation for diagnostic and therapeutic development. Furthermore, as per sources, numerous clinical trials involving cell therapies are active globally, with researchers utilising advanced technologies to ensure product consistency and safety. This clinical imperative ensures that cell sorting remains a cornerstone of modern biomedical research and regenerative medicine. The ability to isolate rare cell types with high viability enables researchers to uncover disease mechanisms and develop personalised treatments. Consequently, the demand for sophisticated sorting platforms continues to grow across academic institutions, pharmaceutical companies, and clinical laboratories, forming a vital segment of the life sciences industry.
MARKET DRIVERS
Surging Demand for Personalised Medicine and Cell Therapies
The escalating adoption of personalised medicine and advanced cell therapies is among the major factors behind the expansion of the cell sorting market. Precision oncology and regenerative medicine require the isolation of specific patient-derived cells to create tailored treatments such as Chimeric Antigen Receptor T cell therapy. According to the Alliance for Regenerative Medicine, there were over 1,300 clinical trials involving cell and gene therapies underway globally in 2023. This widespread clinical activity directly translates to increased procurement of high-throughput and high-precision sorting instruments. The Food and Drug Administration has approved multiple cell-based products, setting a precedent that encourages further investment in this sector. Additionally, as per sources, the clinical pipeline for advanced therapies is continuously expanding with billions of dollars in investments, necessitating scalable manufacturing solutions. The complexity of these therapies demands strict quality control, which is achieved through accurate cell sorting. As healthcare systems shift toward value-based care models that prioritise effective targeted treatments, the reliance on cell sorting technologies intensifies. This trend ensures sustained market growth as pharmaceutical and biotechnology companies expand their cell therapy pipelines.
Advancements in Single-Cell Analysis Technologies
Rapid technological advancements in single-cell analysis significantly propel the demand for sophisticated cell sorting devices in the global market. These instruments must be capable of handling minute sample volumes with high precision. Researchers increasingly require tools that can isolate individual cells for genomic and proteomic profiling to understand cellular heterogeneity. According to studies, single-cell RNA sequencing adoption has grown rapidly as a key technology for biological research, increasing the demand for compatible workflow platforms. These studies often rely on droplet-based sorting technologies that maintain cell viability while enabling downstream molecular analysis. The Human Cell Atlas initiative, supported by the Chan Zuckerberg Initiative, aims to map every cell type in the human body, generating massive demand for high-resolution sorting instruments. Furthermore, the integration of microfluidics into sorting devices has reduced reagent consumption and improved throughput, making them attractive to cost-conscious laboratories. The Journal of Immunological Methods notes that modern sorters can process thousands of cells per second with minimal stress, preserving functional integrity for sensitive assays. This technological evolution allows scientists to explore previously inaccessible biological questions, driving adoption across academic and commercial sectors. Single-cell omics are rapidly becoming standard practice. Consequently, the market for advanced cell sorters continues to expand.
MARKET RESTRAINTS
High Operational Costs and Maintenance Requirements
The substantial financial burden associated with the operation and maintenance of cell sorting instruments is a significant limitation to market expansion. This restraint is particularly true for smaller laboratories. These complex systems require specialised reagents, fluorescent dyes, and regular calibration by trained technicians, leading to high recurring expenses. According to a survey, the average annual maintenance cost for a flow sorter can exceed 25,000 dollars, posing a challenge for institutions with limited budgets. This ongoing cost discourages smaller research groups from investing in advanced sorting capabilities, limiting their access to cutting-edge technologies. Additionally, the need for sterile conditions and expensive consumables such as nozzles and tubing adds to the operational expenditure. As per studies, equipment downtime due to technical issues can delay critical scientific experiments, resulting in lost productivity and additional repair costs. These financial constraints strain research budgets, especially in developing regions where funding is scarce. Consequently, many institutions opt for older models or outsource sorting services, limiting direct market growth for new instruments. The economic pressure forces administrators to carefully evaluate the return on investment, often prioritising other essential laboratory equipment. This cost barrier hampers the widespread adoption of next-generation sorting technologies, restricting market penetration in key segments.
Shortage of Skilled Technical Personnel
There is a global shortage of trained professionals capable of operating and maintaining complex systems in the cell sorting market. This scarcity presents a formidable barrier to market utilisation. Effective use of these instruments requires deep knowledge of fluidics, optics, and data analysis, skills that are not widely available in the general workforce. According to research, there is a gap between the number of available positions for specialised laboratory personnel and qualified candidates, leading to operational bottlenecks in many facilities. This staffing deficit means that expensive instruments may sit idle or be used suboptimally, reducing their value proposition. The International Society for Advancement of Cytometry states that improper operation can lead to data inaccuracies and instrument damage, further increasing costs. Universities and training programs struggle to keep pace with the rapid evolution of sorting technologies, exacerbating the skills gap. Consequently, laboratories face delays in research projects and increased reliance on external core facilities. This lack of expertise hinders the adoption of sophisticated multi-parameter sorting applications that require advanced troubleshooting skills. Hospitals and research centres may hesitate to purchase new systems if they cannot guarantee adequate staffing. This human resource challenge restricts the full potential of cell sorting technologies, slowing overall market growth despite technological advancements.
MARKET OPPORTUNITIES
Integration of Artificial Intelligence and Automation
The incorporation of artificial intelligence and automation into cell sorting workflows offers a lucrative opportunity for market expansion. This enhances efficiency and data accuracy. Modern systems are increasingly equipped with machine learning algorithms that optimise sorting parameters in real time and automate data interpretation. According to reports, integrating artificial intelligence and robotic automation into laboratory workflows can improve process consistency, confluency tracking, and throughput while minimising operator error. This technological evolution allows for unattended operation, freeing up skilled personnel for other tasks. Furthermore, the ability to integrate sorting data with electronic laboratory notebooks facilitates better reproducibility and compliance with regulatory standards. The National Institute of Standards and Technology emphasises that automated quality control features improve consistency across different batches, which is crucial for clinical applications. As laboratories prioritise operational efficiency, the demand for smart sorting platforms grows. Manufacturers who invest in developing AI-enabled software can differentiate their offerings and capture premium market segments. The trend toward digital laboratories also opens avenues for cloud-based data management and remote monitoring. This convergence of technology and biology creates new revenue streams and strengthens the competitive position of innovators in the market.
Expansion into Point-of-Care Diagnostics
The growing interest in point-of-care diagnostics provides a significant prospect for the cell sorting market. This opportunity is driven by miniaturised sorting technologies that enable rapid bedside analysis. Portable and handheld cell sorters are being developed for immediate identification of pathogens or immune cells in clinical settings. According to studies, rapid diagnostic tools play a crucial role in clinical settings by shortening detection times for infectious pathogens, which can help reduce the length of hospital stays. This transition drives demand for compact, user-friendly devices that do not require extensive laboratory infrastructure. The World Health Organisation supports the deployment of decentralised diagnostic tools in resource-limited settings to improve access to healthcare. Manufacturers can capitalise on this trend by designing robust, battery-operated sorters suitable for field use. Additionally, the rise of telemedicine creates opportunities for connected sorting devices that transmit data to central laboratories for expert analysis. The ageing population further fuels this segment, as elderly patients benefit from quicker diagnostic turnaround times. By focusing on portability and ease of use, companies can tap into this expanding market. The shift toward decentralised care thus transforms the distribution landscape, offering manufacturers new channels to reach end users.
MARKET CHALLENGES
Complexity of Data Analysis and Interpretation
Advanced sorters generate multiparameter data with inherent analytical complexity, which holds back the growth of the cell sorting market. This characteristic remains a persistent challenge that directly limits user adoption and efficiency. Modern instruments can measure dozens of parameters simultaneously, producing vast datasets that require sophisticated bioinformatics tools for interpretation. According to sources, the volume of data generated by single-cell sorting experiments has increased significantly, overwhelming traditional analysis methods and requiring specialised computational resources. This data deluge necessitates hiring bioinformaticians or investing in expensive software licenses, adding to the overall cost of ownership. As per studies, inconsistent data processing pipelines can lead to irreproducible results, undermining scientific validity. Consequently, researchers face steep learning curves and potential delays in publishing findings. Failure to manage these data challenges can result in misinterpretation of biological signals and flawed conclusions. Manufacturers must therefore provide robust software support and training, which strains their resources. Despite these efforts, the challenge of making complex data accessible to non-expert users remains a critical issue. This analytical bottleneck influences purchasing decisions, as some laboratories prefer simpler systems with lower data output. Limiting the usability of advanced features restricts the broader adoption of high-end sorting technologies.
Regulatory Hurdles for Clinical Applications
Stringent regulatory requirements for using these sorting devices in clinical diagnostics are also a significant impediment to cell sorting market expansion. This barrier primarily limits growth within the healthcare sector. Obtaining approval from bodies such as the Food and Drug Administration or the European Medicines Agency requires extensive validation and clinical trial data. According to research, the clearance process for complex in vitro diagnostic devices can take several years and cost millions of dollars, delaying market entry for innovative technologies. This prolonged timeline stifles innovation, as companies hesitate to invest in clinical-grade developments due to regulatory uncertainty. Furthermore, as per reports, harmonisation of standards across different regions remains incomplete, forcing manufacturers to undergo multiple separate approval processes. This fragmentation increases the administrative burden and financial risk for developers. The strict adherence to Good Manufacturing Practice standards also requires significant infrastructure investment. As a result, many advanced sorting features remain restricted to research use only, limiting their clinical impact. The regulatory hurdle thus limits the diversity of clinically approved products available to healthcare providers. This environment favours large established players with robust regulatory affairs departments, while smaller innovators struggle to gain a foothold, ultimately restraining market dynamism in the clinical segment.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Covered | By Technology, Product, Application, End-User, and Region |
| Various Analyses Covered | Global, Regional & Country Level Analysis, Segment-Level Analysis, Drivers, Restraints, Opportunities, Challenges; PESTLE Analysis; Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Regions Covered | North America, Europe, Asia Pacific, Latin America, the Middle East, and Africa |
| Market Leader Profiled | Becton, Dickinson, and Company (U.S.), Bio-Rad Laboratories, Inc. (U.S.), Beckman Coulter |
SEGMENTAL ANALYSIS
By Technology Insights
The FACS-based droplet cell sorting segment led the cell sorting market and captured a significant share in 2025. This leading position of the segment was attributed to its superior ability to isolate rare cell populations with high purity and viability, which is critical for advanced immunological research. According to the Journal of Immunological Methods, modern flow cytometry instrumentation allows for the measurement of up to 30 parameters per cell. This multi-parameter capability is essential for characterising diverse immune cell subsets in cancer and autoimmune disease studies. As per sources, high-purity cell sorting is vital for downstream single-cell analysis, which has been widely adopted across academic and clinical research platforms. Furthermore, the ability to sort cells at high speeds, often exceeding 70000 events per second, allows for the efficient processing of large sample volumes required in clinical trials. According to studies, cell sorting techniques are standard methods for isolating specific cell subsets to support therapeutic development and immunological research. This established reliability and versatility ensure that laboratories continue to prioritise FACS instruments despite the emergence of alternative technologies. The extensive library of validated protocols and reagents compatible with droplet sorters further cements their position as the preferred choice for complex experimental designs, driving consistent demand and market leadership.
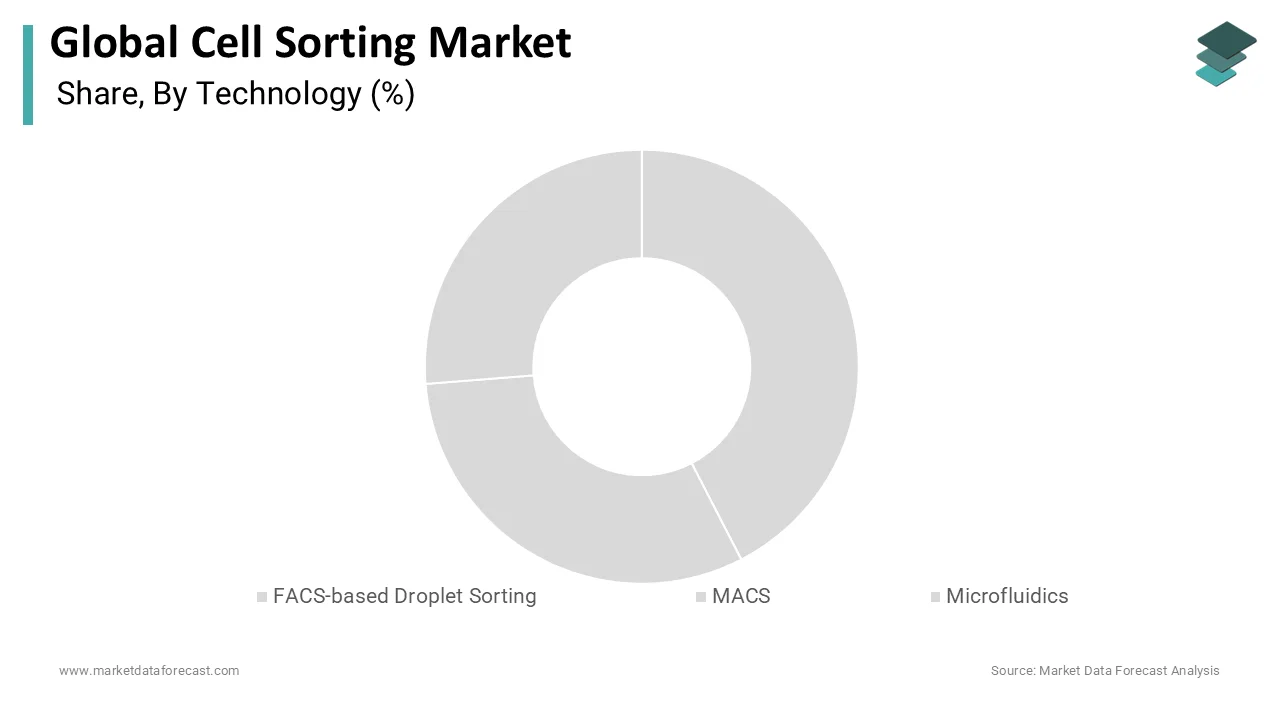
The widespread installation base and standardisation of FACS-based droplet sorting systems in major research facilities significantly contribute to their market dominance. According to research, shared flow cytometry core facilities widely provide droplet-based sorting technologies to support a diverse range of research and clinical applications. This ubiquity ensures that new researchers are trained on these platforms, perpetuating their use in future projects. As per sources, standardised data reporting and quality control guidelines are widely promoted in flow cytometry to improve reproducibility and data comparability across research studies. Additionally, the robust service networks provided by major manufacturers ensure minimal downtime and reliable performance, which is crucial for time-sensitive experiments. According to studies, data from validated flow cytometry workflows can be included in regulatory submissions for cell therapy products. This regulatory acceptance reduces the risk associated with technology selection for drug developers. The combination of technical superiority, regulatory validation, and established user familiarity creates high switching costs, preventing competitors from easily displacing FACS technology. Consequently, the segment maintains its leading position through continuous upgrades and integration with existing laboratory workflows.
The microfluidic cell sorting segment is on the rise and is expected to be the fastest-growing segment in the market, witnessing a CAGR of 12.5% from 2026 to 2034. This rapid expansion is propelled by the increasing demand for miniaturised devices that require minimal sample volumes and reagents. According to the Lab on a Chip journal, microfluidic systems can reduce reagent consumption by up to 90% compared to traditional flow cytometers, making them highly cost-effective for precious samples such as biopsies or pediatric blood draws. This efficiency is particularly valuable in clinical settings where sample availability is limited. The World Health Organisation supports the development of point-of-care diagnostic tools that are portable and easy to use, characteristics inherent to microfluidic platforms. Furthermore, the integration of microfluidics with downstream analysis techniques such as polymerase chain reaction allows for seamless workflow automation. According to sources, research interest in micro-total analysis systems (μTAS) and lab-on-a-chip technologies remains high across engineering and medical disciplines. These devices offer gentle handling of cells, preserving viability for sensitive applications such as stem cell culture. As research shifts toward personalised medicine requiring frequent monitoring, the need for low-volume, high-throughput sorting intensifies. Manufacturers are responding by developing chip-based sorters that are disposable and sterile, reducing cross-contamination risks. This technological shift toward miniaturisation and efficiency ensures rapid adoption and sustained growth for the microfluidics segment.
The seamless integration of microfluidic sorting with single-cell omics technologies is a key driver accelerating its growth in the Cell Sorting Market. According to studies, droplet-based microfluidics is a widespread method for cell encapsulation in single-cell sequencing workflows to achieve high-throughput genetic analysis. This automation reduces human error and increases reproducibility, which are critical for large-scale studies. As per research, high-throughput cell processing and barcoding technologies are critical components for constructing comprehensive cellular maps of complex biological tissues. Additionally, the ability to couple sorting with real-time imaging provides morphological context to genomic data, enhancing biological insights. According to sources, open-source instrumentation and design sharing lower the barriers to entry and accelerate innovation in laboratory microfluidics. This collaborative environment accelerates the development of novel sorting mechanisms such as acoustic and dielectrophoretic methods. As single-cell analysis becomes routine in drug discovery, the demand for integrated microfluidic solutions grows. Pharmaceutical companies are adopting these platforms to streamline their screening pipelines, reducing time to market for new therapies. The versatility and scalability of microfluidic systems make them ideal for next-generation biological research, driving their rapid expansion in the market.
By Product Type Insights
The reagents and consumables segment dominated the cell sorting market and accounted for a substantial share in 2025. This dominance was driven by its recurring nature and essential role in every cell sorting experiment. According to sources, reagents and consumables such as antibodies and fluorochromes constitute a major portion of the operational expenditure for a shared flow cytometry resource laboratory. Each sorting run requires fresh reagents to ensure accurate labelling and optimal instrument performance, creating a steady stream of revenue for manufacturers. As per studies, the complexity of multicolour flow cytometry panels has significantly increased over time, leading to higher reagent utilisation across high-dimensional cellular experiments. Additionally, the need for sterile disposables such as collection tubes and nozzles prevents cross-contamination, further boosting consumption. The Journal of Immunological Methods notes that the stability of fluorescent dyes is critical for data quality, prompting laboratories to purchase premium-quality reagents from trusted suppliers. This reliance on high-quality consumables ensures customer loyalty and repeat purchases. Unlike instruments, which are capital expenditures with long replacement cycles, reagents represent operational expenses that are less susceptible to budget cuts. The continuous expansion of research projects and clinical trials sustains high usage rates, solidifying the dominance of this segment in the overall market.
The growing trend toward multiplexing and customised reagent panels significantly drives the dominance of the reagents and consumables segment. According to research, the commercial expansion of specialised fluorochrome-conjugated antibodies allows researchers to build increasingly complex panel configurations for cellular characterisation. This expansion enables the simultaneous identification of rare cell subsets, increasing the value proposition of advanced reagents. Pharmaceutical companies frequently require custom conjugates for proprietary biomarkers, creating a lucrative niche for specialised manufacturers. The Food and Drug Administration encourages the use of standardised reagents in clinical trials to ensure data consistency, driving demand for certified products. Additionally, the development of novel fluorophores with minimal spectral overlap allows for higher parameter sorting, further stimulating reagent sales. As per the American Association of Immunologists, training workshops on panel design have increased awareness of optimal reagent combinations, leading to more sophisticated purchasing behaviours. Laboratories are willing to pay a premium for validated kits that simplify experimental setup and reduce troubleshooting time. This shift toward convenience and performance ensures that reagents remain a critical and high-value component of the cell sorting workflow, maintaining their market leadership.
The cell sorters segment is likely to experience the fastest CAGR of 9.8% between 2026 and 2034 due to the rapid pace of technological innovation and the need to replace ageing instruments. According to the Association of Biomolecular Resource Facilities, a surveyed cohort of flow cytometers and sorters in shared resource laboratories demonstrated an average instrument age of 8.5 years. Newer models offer improved sensitivity, speed, and ease of use, enticing laboratories to upgrade. The National Science Foundation notes that increased federal funding for biomedical research has enabled institutions to invest in state-of-the-art equipment, boosting sales. Additionally, the introduction of benchtop sorters has made cell sorting accessible to smaller laboratories that previously lacked space or resources for large floor-standing units. These compact instruments offer similar performance to larger systems but with a smaller footprint and lower cost. As per the Journal of Laboratory Automation, automated sorting features reduce the need for specialised operators, broadening the user base. As research questions become more complex, the demand for high-performance instruments capable of handling multi-parameter assays grows. This combination of replacement demand and accessibility improvements drives robust growth in the cell sorters segment.
The expanding adoption of cell sorters in clinical diagnostics and industrial biomanufacturing is accelerating growth in this segment. According to sources, clinical developers are expanding cell and gene therapy manufacturing pipelines globally, driving structural deployment of qualified instrumentation for production and regulatory compliance. These industrial applications demand robust and scalable sorters that can operate continuously under Good Manufacturing Practice conditions. The Food and Drug Administration mandates strict process validation for cell therapies, driving investment in compliant sorting equipment. Additionally, hospitals are beginning to integrate sorters into diagnostic workflows for rare disease detection, such as circulating tumour cell analysis. The Centers for Disease Control and Prevention supports the use of advanced cytometry for infectious disease monitoring, further expanding the clinical market. Manufacturers are developing closed-system sorters to meet sterility requirements for clinical use, opening new revenue streams. The transition from research-only to clinical-grade applications signifies a maturation of the market, with higher-value transactions. As personalised medicine becomes mainstream, the need for precise and reliable cell isolation in clinical settings will continue to drive strong demand for new sorting instruments.
By End User Insights
The research institutes segment was the largest in 2025 and occupied a commanding share of the cell sorting market. This prominence was supported by its central role in basic biological discovery and substantial government funding. According to the National Institutes of Health, federal spending on biomedical research exceeds 45 billion dollars annually, a significant portion of which is allocated to equipment procurement, including cell sorters. Academic and government laboratories conduct the majority of fundamental immunology and stem cell research, which relies heavily on cell sorting for hypothesis testing. As per the National Science Foundation, universities are expanding their core facilities to support interdisciplinary research, driving bulk purchases of high-end instruments. Furthermore, research institutes serve as training grounds for future scientists, ensuring long-term familiarity with specific brands and technologies. According to the International Society for Advancement of Cytometry, academic conferences and workshops are primarily attended by researchers who influence purchasing decisions in their respective institutions. This ecosystem of education and discovery creates a stable and large customer base. The diversity of research topics, from neuroscience to oncology, ensures broad application of cell sorting technologies. As scientific inquiry deepens, the need for precise cell isolation remains paramount, securing the dominant position of research institutes in the market.
The prevalence of shared core facilities within research institutes significantly contributes to their market leadership in cell sorting. According to the Association of Biomolecular Resource Facilities, most major universities operate centralised flow cytometry cores that serve hundreds of investigators, maximising instrument utilisation and justifying high-cost acquisitions. These cores often purchase the latest technology to remain competitive and attract external collaborations, driving early adoption of new products. The Cancer Prevention & Research Institute of Texas encourages resource sharing through its Core Facility Support awards, providing financial incentives for maintaining advanced equipment. Additionally, collaborative grants often require access to specialised sorting capabilities, further reinforcing the importance of these central resources. According to the Journal of Immunological Methods, core facilities provide expert consultation and training, lowering the barrier to entry for novice users. This support structure increases the overall volume of sorting experiments conducted within academic settings. The concentration of expertise and equipment in research institutes creates a hub of activity that drives consistent demand for instruments, reagents, and services. As collaborative science becomes more common, the role of these shared resources will continue to expand, sustaining their market dominance.
The biopharma companies segment is predicted to witness the highest CAGR of 11.2% during the forecast period, owing to the explosive growth in cell and gene therapy development. According to the Alliance for Regenerative Medicine, global investment in cell therapy companies reached record levels, with over 1000 active clinical trials requiring industrial-scale cell sorting for manufacturing. These companies need robust and compliant sorting systems to isolate therapeutic cells such as T cells and stem cells with high purity and yield. The Food and Drug Administration has approved several cell therapies, validating the commercial viability of this sector and encouraging further investment. Additionally, the need for process optimisation and scale-up drives demand for automated and high-throughput sorters. As per the Journal of Clinical Investigation, biopharma companies are increasingly integrating sorting into their early discovery pipelines to identify novel biomarkers and targets. This vertical integration expands their equipment needs beyond manufacturing. The competitive landscape in oncology and autoimmune diseases pushes companies to accelerate their timelines, favoring efficient and reliable sorting technologies. As more therapies move from bench to bedside, the reliance on biopharma companies as key customers for cell sorting vendors will continue to grow rapidly.
Strict regulatory requirements for quality control in biopharmaceutical manufacturing are propelling the growth of this end user segment. According to the International Council for Harmonisation, biopharma companies must adhere to rigorous standards for product consistency and safety, necessitating precise and validated cell sorting processes. This regulatory pressure drives the adoption of advanced sorters with detailed data logging and audit trail capabilities. The Food and Drug Administration inspects manufacturing facilities regularly, ensuring compliance with Good Manufacturing Practice guidelines, which influences equipment selection. Additionally, the need for lot release testing requires high-precision sorting to verify product identity and potency. As per the Alliance for Regenerative Medicine, quality by design principles are being adopted, integrating sorting parameters into the overall process control strategy. This approach requires sophisticated instruments that can provide real-time feedback and adjustment. Biopharma companies are willing to invest in premium equipment to mitigate regulatory risks and ensure product approval. The increasing complexity of biologics and combination products further elevates the importance of precise cell isolation. As regulatory scrutiny intensifies, biopharma companies will continue to drive demand for high-quality and compliant cell sorting solutions.
COUNTRY LEVEL ANALYSIS
North America Cell Sorting Market Analysis
North America was the top performer in the cell sorting market and held a dominant share in 2025. This top position was driven by its robust biomedical research infrastructure and high healthcare expenditure. According to the National Institutes of Health, the United States accounts for nearly half of global biomedical research funding, supporting extensive use of advanced cell sorting technologies in academic and commercial settings. The presence of major market players such as BD and Thermo Fisher Scientific facilitates rapid adoption of innovations and provides strong local support. The Food and Drug Administration’s progressive regulatory framework for cell therapies encourages pharmaceutical companies to invest in manufacturing capabilities, boosting demand for industrial sorters. Additionally, the high prevalence of chronic diseases such as cancer and diabetes drives research into personalised medicine, further fueling market growth. As per sources, North America represents a substantial share of the global flow cytometry core facility infrastructure, providing researchers with broad access to cell isolation instruments. Strong intellectual property protection and venture capital availability also foster innovation in the life sciences sector. These factors combine to maintain North America as the dominant region, characterised by high technology adoption rates and significant research output.
Europe Cell Sorting Market Analysis
Europe followed closely behind in the cell sorting market in 2025. This standing of the regional market was propelled by strong government support for collaborative research and stringent quality standards. According to the European Commission, Horizon Europe programs allocate billions of euros to health research, promoting cross-border collaborations that often involve shared access to advanced sorting facilities. The European Medicines Agency has established clear guidelines for advanced therapy medicinal products, driving demand for compliant sorting equipment in the biopharma sector. Countries such as Germany, the United Kingdom, and France have well-established pharmaceutical industries that are increasingly focusing on cell therapy development. The International Society for Advancement of Cytometry has a strong presence in Europe, organising regular training and conferences that enhance user expertise. Additionally, the region’s emphasis on data privacy and ethical research practices influences the development of secure and transparent sorting software. The ageing population in Europe increases the burden of age-related diseases, spurring research into regenerative medicine. These demographic and policy factors sustain steady market growth, with a focus on high-quality and ethically sourced technologies.
Asia-Pacific Cell Sorting Market Analysis
The Asia-Pacific region experienced rapid growth in the cell-sorting market, fueled by increasing government investment in life sciences and expanding pharmaceutical industries. According to the Chinese Academy of Sciences, China has significantly increased its R&D spending in biotechnology, leading to a surge in the establishment of new research institutes and core facilities. India and South Korea are also emerging as hubs for generic and biosimilar manufacturing, driving demand for quality control sorting instruments. The World Health Organisation notes that the rising burden of non-communicable diseases in the region is prompting governments to prioritise healthcare innovation and diagnostics. Additionally, the growing middle class is increasing demand for advanced medical treatments, encouraging local pharmaceutical companies to invest in cell therapy capabilities. The presence of low-cost manufacturing bases for consumables also supports market expansion by reducing operational costs for laboratories. International collaborations between Asian and Western institutions are facilitating technology transfer and skill development. These economic and scientific developments position Asia Pacific as a high-growth market with significant potential for future expansion.
Latin America Cell Sorting Market Analysis
Latin America showed moderate growth in the Cell Sorting Market, due to gradual improvements in healthcare infrastructure and increasing awareness of advanced diagnostic techniques. According to the Pan American Health Organisation, countries such as Brazil and Mexico are investing in public health research to address regional health challenges such as infectious diseases and cancer. Local universities are expanding their biomedical programs, creating demand for educational and research instruments. The Inter-American Development Bank supports healthcare modernisation projects, which include upgrading laboratory equipment in public hospitals and research centres. However, economic volatility and currency fluctuations can hinder large capital investments, leading to a preference for cost-effective solutions. The rise of private healthcare providers in urban areas is also contributing to market growth, as these facilities seek to offer competitive diagnostic services. International aid and partnerships with global manufacturers help improve access to technology in underserved areas. Despite challenges, the underlying need for better healthcare outcomes ensures steady, albeit slower, growth in the region.
The Middle East and Africa Cell Sorting Market Analysis
The Middle East and Africa region provided emerging opportunities in the cell sorting market, supported by government initiatives to diversify economies and improve healthcare systems. According to the World Bank, Gulf Cooperation Council countries are investing heavily in healthcare infrastructure as part of their vision plans, including the construction of advanced research hospitals. Saudi Arabia and the United Arab Emirates are establishing biotechnology parks to foster local innovation and attract international partnerships. In Africa, research institutes in South Africa and Kenya are collaborating with global organisations to study infectious diseases such as HIV and malaria, driving demand for basic sorting capabilities. The African Union supports capacity-building initiatives that include training scientists in advanced laboratory techniques. Limited local manufacturing means the region relies on imports, but growing economic stability is improving purchasing power. International NGOs play a crucial role in supplying equipment for public health programs. As these nations develop their scientific capabilities, the demand for cell sorting technologies is expected to grow, driven by both research and clinical needs.
COMPETITIVE LANDSCAPE
The competition in the Cell sorting market is characterized by the presence of established multinational corporations and specialized technology innovators who strive to differentiate through performance and service quality. Leading companies compete primarily on instrument sensitivity, throughput, and ease of use, as these factors directly impact research efficiency and data quality. The market sees intense rivalry in the development of single-cell sorting technologies, which are becoming essential for genomic and proteomic studies. Price competition is moderate as researchers prioritize reliability and technical support over cost alone. However, emerging manufacturers from Asia Pacific regions are gaining traction by offering cost-effective alternatives for routine applications. Strategic collaborations with key opinion leaders and research institutions help key players validate clinical efficacy and accelerate product adoption. Intellectual property protection plays a crucial role, with firms securing patents for novel fluidics and optical designs. The competitive landscape is further shaped by regulatory hurdles that favor experienced players with robust compliance frameworks. Continuous investment in customer training and application support serves as a key differentiator, ensuring long-term loyalty among academic and industrial users.
KEY MARKET PLAYERS
Some of the notable participants leading the global cell sorting market covered in this report are
- Becton Dickinson and Company (U.S.)
- Bio-Rad Laboratories, Inc. (U.S.)
- Beckman Coulter, Inc. (U.S.)
- Miltenyi Biotec GmbH (Germany)
- Affymetrix Inc. (U.S.)
- Sony Biotechnology, Inc. (U.S.)
- Sysmex Partec GmbH (Japan)
- Cytonome/ST, LLC (U.S.)
- On-Chip Biotechnologies Co., Ltd. (Japan)
- and Union Biometrica, Inc. (U.S.)
TOP LEADING PLAYERS IN THE MARKET
- BD remains a dominant force in the cell sorting market through its comprehensive portfolio of flow cytometers and reagents. The company actively invests in developing high parameter sorting systems that cater to complex immunophenotyping needs in research and clinical settings. Recent initiatives include the launch of advanced software platforms that simplify data analysis and instrument operation for users with varying levels of expertise. BD collaborates extensively with academic institutions to establish best practices and training programs, fostering long-term customer loyalty. The company also focuses on expanding its global service network to ensure minimal downtime for critical laboratory equipment. By integrating hardware innovation with robust support services, BD strengthens its position as a trusted partner for life science researchers. Their commitment to quality and reliability ensures consistent adoption of their sorting technologies across diverse scientific disciplines and geographical regions.
- Thermo Fisher Scientific leverages its vast resources to offer integrated cell sorting solutions that combine instruments with specialized consumables and antibodies. The company emphasizes workflow efficiency by providing end-to-end systems that streamline sample preparation and data acquisition. Recent actions include the introduction of benchtop sorters designed for smaller laboratories seeking high performance without large footprints. Thermo Fisher actively engages in strategic partnerships with biotechnology firms to develop custom reagents tailored for specific therapeutic applications. The company also enhances its digital capabilities by offering cloud-based data management tools that facilitate collaboration and reproducibility. By focusing on user-friendly designs and comprehensive product ecosystems, Thermo Fisher addresses the evolving needs of modern laboratories. Their global distribution network and strong brand reputation enable them to maintain a competitive edge in the rapidly advancing cell sorting sector.
- Bio-Rad Laboratories contributes significantly to the market by offering innovative cell sorting technologies focused on single-cell genomics and proteomics. The company has gained prominence with its droplet-based microfluidic systems that enable high-throughput single-cell isolation for sequencing applications. Recent developments include the expansion of its single-cell multi-omics portfolio, allowing researchers to analyze gene expression and protein levels simultaneously. Bio-Rad invests heavily in research and development to improve the sensitivity and accuracy of its sorting platforms. The company also provides extensive technical support and application resources to help scientists optimize their experimental designs. By targeting the growing demand for single-cell analysis, Bio-Rad differentiates itself from traditional flow cytometry providers. Their focus on cutting-edge technology and scientific collaboration strengthens their position in the niche but rapidly expanding segment of single-cell research.
TOP MAJOR STRATEGIES USED BY KEY PLAYERS
Key players in the Cell sorting market employ several strategic initiatives to maintain competitiveness and drive growth. Product innovation remains a primary strategy, with companies investing heavily in research and development to create higher-parameter and more automated systems. Manufacturers focus on integrating artificial intelligence and machine learning to enhance data analysis and instrument usability. Strategic acquisitions and partnerships are common, allowing firms to expand their product portfolios and enter new application areas such as single-cell genomics. Companies frequently collaborate with academic and clinical institutions to validate new technologies and gather user feedback. Regulatory compliance and quality assurance are prioritized to meet stringent standards for clinical applications. Additionally, manufacturers emphasize sustainability by developing eco-friendly consumables and energy-efficient instruments. Marketing efforts target both research and industrial segments, highlighting ease of use and reproducibility. These multifaceted strategies help companies adapt to evolving scientific demands and secure long-term success in the dynamic life sciences landscape.
GLOBAL CELL SORTING MARKET NEWS
-
In April 2019, Miltenyi Biotec introduced a new platform for fully automated and high-content imaging at the AACR ANNUAL MEETING 2019 in ATLANTA, the MACSima Imaging Platform.
-
In June 2019, Beckman Coulter Life Sciences announced its acquisition of Cytobank, a software platform for multi-parametric single-cell data analysis, a software-as-a-service company based in Santa Clara, California.
- In March 2019, researchers reconstructed kidney tubules derived from human kidney adult stem cells in microfluidic chips. The tubules show cilia at the luminal side and ion transporters at the blood side.
- In January 2019, STEMCELL Technologies launched mTeSR Plus, an enhanced version of mTeSR 1, a widely accepted feeder-free human pluripotent stem cell maintenance medium. It has undergone beta testing with several Stem Cell Coredinates group members.
- In March 2018, Terumo BCT, a U.S.-based global leader in blood component and cellular technologies, selected services and consulting firm Capgemini to set up two global innovation and development (I&D) centers in India.
- In October 2018, UniCAR- Therapy Bio-Medicine Technology chose Terumo BCT and its cell expansion devices to implement automation in its cell therapy manufacturing process for chimeric antigen receptor CAR T-cell therapies.
MARKET SEGMENTATION
This research report on the global cell sorting market has been segmented and sub-segmented based on the technology, product, application, end-user, and region.
By Technology
- FACS-based Droplet Sorting
- MACS
- Microfluidics
By Product
- Cell Sorters
- Reagents
- Consumables
By Application
- Research
- Clinical
By End-User
- Research Institutes
- Biopharma Companies
- Medical Schools
By Region
- North America
- Europe
- Asia Pacific
- Latin America
- The Middle East and Africa