- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$219.2 MnMarket Estimate, 2026
$233.6 MnMarket Forecast, 2034
$388.7 MnCAGR, 2026–2034
6.57%Executive Summary: Europe Synbiotic Products Market
- Market Scope: Comprehensive Europe synbiotic products market analysis covering product variations, distribution channels, application verticals, packaging materials, regional country frameworks, and adoption metrics.
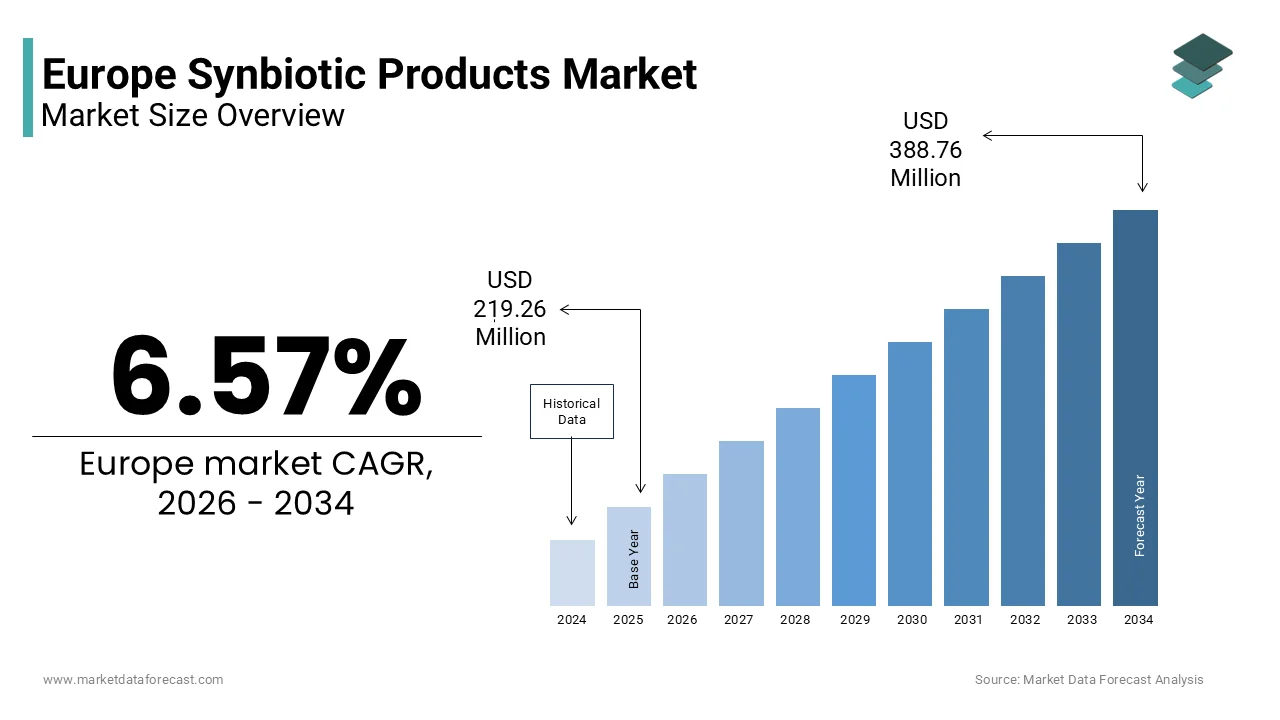
- Market Valuation: Valued at USD 219.26 million (2025), estimated at USD 233.67 million (2026), and projected to reach USD 388.76 million by 2034, registering a robust CAGR of 6.57% (2026–2034).
- Primary Growth Drivers: Rising consumer awareness of health, changes in food consumption patterns, increasing disposable income, and growing prevalence of intestinal and chronic health problems. Key operational highlights include advanced capsule technology (such as Licaps with moisture defense systems for targeted ingredient release) and expanding applications across functional foods, beverages, and animal nutrition.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (2025 Position) | Fastest-Growing Segment |
|---|---|---|
| By Type | Dairy and frozen desserts (held the largest share in the European market) | Dietary supplements (experiencing high consumer demand and rapid expansion) |
| By Distribution Channel | Store-based (expected to earn a significant portion of market revenue) | Non-store based (presumed to grow at a faster pace over the projection period) |
| By Application | Food and beverages (led overall application demand) | Medication and clinical applications |
| By Packaging Material | Plastic and paper packaging formats | Specialized moisture-defense cup and container systems |
| By Region / Country | Europe overall (accounted for the highest global share, led by key nations like Germany, UK, France, and Italy) | Europe (projected to remain the fastest-growing regional market globally) |
Major Market Players & Market Structure
Market Structure: Highly competitive European functional food and supplement landscape featuring major dairy, biotech, and pharmaceutical players competing on advanced encapsulation technology, targeted probiotic-prebiotic synergies, product innovation, and expanded distribution footprints.
Key Companies: Seed Health, Inc., Sabinsa Corporation, Biomin America Inc., Yakult Honsha Co., Ltd., H&H Group, The Kellogg Company, Danone S.A., General Mills, Inc., Pfizer Inc., Daflorn Ltd., United Naturals, and Probiotical S.p.A.
 Download Free Sample Report
Europe Synbiotic Products Market Size
The Europe synbiotic products market size was valued at USD 219.26 million in 2025 and is expected to reach USD 388.76 million by 2034 from USD 233.67 million in 2026. The market is growing at a CAGR of 6.57% during the forecast period.
The synbiotic products are convergence of probiotics and prebiotics designed to enhance gut health through synergistic mechanisms. This specialized sector addresses the growing consumer demand for functional foods that offer scientifically validated health benefits beyond basic nutrition. As per Eurostat, approximately 23% of the European population suffers from chronic digestive disorders, creating a substantial base for targeted therapeutic interventions. Regulatory frameworks within the European Union have become increasingly stringent regarding health claims, forcing manufacturers to invest heavily in clinical validation. According to the European Food Safety Authority, over 80% of submitted health claims for probiotic products have been rejected due to insufficient scientific evidence, shaping a highly competitive landscape where only rigorously tested formulations survive. This heightened consciousness drives innovation in delivery formats ranging from fermented dairy to advanced supplement capsules.
MARKET DRIVERS
Rising Prevalence of Gastrointestinal Disorders Fuels Demand for Preventive Solutions
The escalating incidence of digestive ailments is greatly influencing the growth of the Europe symbiotic products market. According to the European Centre for Disease Prevention and Control, inflammatory bowel disease affects approximately 3 million individuals in the European Union, with diagnosis rates increasing by 4% annually. This persistent health burden compels consumers to seek non pharmaceutical interventions that can modulate gut flora and reduce inflammation. These statistics directly correlate with market growth as patients increasingly turn to synbiotics for symptom management and long term gut health maintenance. Healthcare providers are also recommending dietary modifications that include synbiotic supplementation, further legitimizing these products in the medical community. The economic impact of digestive disorders is profound, with healthcare systems spending billions on treatment and management. As per data, gastrointestinal conditions contribute significantly to absenteeism and reduced productivity, prompting employers to support wellness initiatives that include gut health products. This multifaceted pressure from both medical necessity and economic efficiency drives sustained demand for scientifically backed synbiotic formulations that offer tangible health improvements.
Growing Consumer Preference for Natural and Functional Food Ingredients
The shift towards natural and functional food ingredients profoundly, as consumers prioritize holistic health approaches that is additionally escalating the growth of the Europe symbiotic products market. This preference aligns with broader wellness trends where prevention is valued over cure, leading to increased consumption of fortified foods and beverages. Synbiotics fit seamlessly into this narrative by offering dual benefits through natural fermentation processes and plant based prebiotics. Many shoppers actively look for functional benefits such as immune support and digestive health when purchasing grocery items. This behavior translates into higher sales volumes for synbiotic enriched yogurts, drinks, and supplements. Synbiotics address these needs by supporting nutrient absorption and immune function, making them attractive to older adults, who constitute a significant portion of the health conscious consumer base.
MARKET RESTRAINTS
Stringent Regulatory Frameworks Limit Product Claims and Innovation Speed
The rigorous regulatory standards imposed by European authorities by limiting the ability of manufacturers to make specific health claims, which is limiting the growth of the Europe symbiotic products market. According to the European Food Safety Authority, only a handful of probiotic strains have received positive opinions for health claims, leaving many products unable to communicate their benefits effectively to consumers. This regulatory bottleneck slows down product launches and increases compliance costs, as companies must invest heavily in clinical trials to substantiate even basic functionality statements. This uncertainty discourages smaller enterprises from entering the market, consolidating power among large corporations with sufficient resources for regulatory navigation. Additionally, the varying interpretations of regulations across different member states create fragmentation by making it difficult for companies to implement uniform marketing campaigns. The time required for approval can extend up to 24 months, delaying revenue generation and reducing the agility needed to respond to emerging consumer trends. These regulatory hurdles ultimately restrict the diversity of products available and limit the pace of innovation in the synbiotic sector.
High Production Costs and Supply Chain Complexities Impact Affordability
The intricate production processes and supply chain challenges associated with synbiotic products create financial barriers that is degrading the growth of the Europe synbiotic products market. According to the study, the cost of producing high quality prebiotic fibers remains 30% higher than standard carbohydrates due to specialized extraction methods and purity requirements. These elevated costs translate into higher retail prices by making synbiotic products less affordable for price sensitive consumers. The volatility in raw material prices, particularly for specific bacterial strains and plant-based prebiotics, further exacerbates financial pressures. Small and medium sized enterprises struggle to compete with larger players who benefit from economies of scale, leading to market consolidation. Additionally, the need for specialized packaging to ensure product stability increases material costs, with sustainable packaging options being even more expensive. These financial constraints limit the ability of manufacturers to expand their product portfolios or enter new geographic segments within Europe.
MARKET OPPORTUNITIES
Expansion into Personalized Nutrition and Digital Health Integration
The integration of synbiotic products with personalized nutrition and digital health technologies is solely to create new opportunities for the growth of Europe symbiotic products market. Consumers are increasingly seeking tailored solutions that address their unique physiological needs by creating demand for synbiotic formulations customized based on individual gut profiles. This synergy allows manufacturers to collect valuable data on product efficacy and consumer behavior, enabling continuous improvement of formulations. Partnerships with telehealth providers and nutritionists can further enhance customer engagement by offering professional guidance alongside product purchases. By leveraging artificial intelligence and machine learning, companies can predict consumer preferences and optimize supply chains by reducing waste and improving profitability.
Development of Novel Delivery Formats and Application Diversity
The innovation in delivery formats and application diversity by expanding consumer reach and usage occasions is also to escalate the growth of the Europe symbiotic products market. This diversification allows manufacturers to tap into impulse purchase behaviors and integrate gut health benefits into everyday eating habits. The development of shelf stable synbiotic technologies eliminates the need for refrigeration, reducing logistical costs and expanding distribution channels to include convenience stores and online platforms. As per the study, the healthy snack segment grew by 9%, reflecting consumer demand for convenient yet nutritious options. Incorporating synbiotics into ready to eat meals and baby food addresses specific demographic needs, such as working parents seeking health benefits for their children. Advances in microencapsulation techniques protect probiotic strains from stomach acid, ensuring higher survival rates and enhanced efficacy. The European Federation of Food Science and Technology highlights that novel delivery systems can improve bioavailability by up to 40%, making products more effective and appealing to discerning consumers. By moving beyond traditional supplements and dairy products, companies can attract younger demographics and health enthusiasts who prioritize convenience without compromising on nutritional value.
MARKET CHALLENGES
Consumer Awareness and Lack of Scientific Literacy
The persistent consumer awareness and limited scientific literacy regarding synbiotic mechanisms penetration and brand trust, which is a major challenge for the growth of the Europe synbitoc products market. This knowledge gap makes it difficult for manufacturers to communicate the unique value proposition of synbiotic products, resulting in lower conversion rates. The complexity of microbiome science often overwhelms average consumers, who may perceive marketing claims as exaggerated or misleading. Misinformation spread through social media further complicates the landscape, with unverified claims about miracle cures creating unrealistic expectations. When products fail to deliver immediate results, consumers often abandon them, negatively impacting repeat purchase rates. Educational initiatives are costly and time consuming, requiring sustained effort to change perceptions. The lack of standardized terminology across products adds to the confusion, with varying definitions of synbiotic efficacy causing inconsistency in consumer experiences. Overcoming these barriers requires transparent communication and third-party validation, but many small brands lack the resources to invest in comprehensive educational campaigns.
Intense Competition and Market Saturation in Key Segments
The intense competition and saturation in established segments such as dairy and supplements, limiting growth opportunities for new entrants, which is additionally hinder the growth of the Europe symbiotic products market. The proliferation of private label products by major retailers further intensifies competition by offering consumers cheaper alternatives with similar formulations. The saturation in traditional categories forces companies to invest heavily in research and development to create unique selling propositions, which increases operational risks. Additionally, the influx of international brands from Asia and North America adds to the competitive pressure, bringing diverse product offerings and marketing strategies. The limited shelf space in retail outlets means that new products must demonstrate immediate consumer appeal to secure placement, often requiring significant trade promotions. This environment makes it challenging for innovative startups to gain visibility and build brand recognition.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 6.57% |
| Segments Covered | By Type, Distribution Channel, Application, Packaging Material, and Region |
| Various Analyses Covered | Regional & Country Level Analysis, Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview on Investment Opportunities |
| Regions Covered | UK, France, Spain, Germany, Italy, Russia, Sweden, Denmark, Switzerland, Netherlands, Turkey, Czech Republic and Rest of Europe |
| Market Leaders Profiled | Seed Health, Inc., Sabinsa Corporation, Biomin America Inc., Yakult Honsha Co., Ltd., H&H Group, The Kellogg Company, Danone S.A., General Mills, Inc., Pfizer Inc., Daflorn Ltd., United Naturals, and Probiotical S.p.A. |
SEGMENTAL ANALYSIS
By Type Insights
The dairy and frozen desserts segment was the largest by holding 32.1% of the Europe synbiotic products market share in 2025 with its deep integration into daily European dietary habits and established consumer trust in fermented products. According to the European Dairy Association, per capita consumption of yogurt and fermented milk products exceeds 30 kilograms annually in countries like France and Germany, providing a massive existing base for synbiotic fortification. This high baseline consumption allows manufacturers to introduce synbiotic variants with minimal consumer education costs, as the format is already familiar and accepted. This regular purchasing behavior ensures consistent revenue streams and market stability for synbiotic dairy brands. Furthermore, the natural synergy between lactic acid bacteria used in fermentation and added prebiotic fibers enhances product efficacy, reinforcing consumer perception of health benefits. The widespread availability of these products in mainstream grocery stores ensures easy access, further cementing their leading position. Manufacturers leverage existing cold chain infrastructure to maintain product quality, reducing logistical complexities compared to newer formats.
The dietary supplements segment is lucratively to grow to register a fastest CAGR of 8.5% during the forecast period with aging demographics and chronic disease prevalence. Consumers seeking specific health outcomes such as immune modulation or mental health support prefer supplements because they offer standardized dosages and specialized strain combinations not feasible in food formats. This trend directly benefits synbiotic supplements as they are perceived as effective preventive tools. Furthermore, advancements in encapsulation technology allow for higher colony forming unit counts and improved stability, addressing previous concerns about efficacy. The rapid expansion of e-commerce and direct to consumer models significantly accelerates the growth of the dietary supplements segment by overcoming traditional retail barriers. This digital shift allows niche brands to reach targeted audiences without the high costs associated with physical shelf space in competitive grocery aisles. Supplement buyers often require detailed information and personalized recommendations, which digital platforms provide through interactive content and virtual consultations.
By Distribution Channel Insights
The store based distribution channels segment was the largest by accounting for 38.1% of the Europe Synbiotic Products Market share in 2025 due to the immediate accessibility they offer and the ability for consumers to evaluate products physically before purchase. Consumers often prefer to check expiration dates, packaging integrity, and ingredient labels in person, especially for perishable items like synbiotic yogurts and drinks. This tactile shopping experience builds trust and reduces perceived risk, particularly for first time buyers unfamiliar with synbiotic brands. Additionally, supermarkets and pharmacies provide instant gratification by allowing consumers to address immediate health concerns without waiting for delivery. As per the study, foot traffic in large hypermarkets remains stable, with health conscious shoppers frequently visiting these stores for weekly grocery runs.
The non-store based distribution channels segment is likely to grow at a fastest CAGR of 12.1% during the forecast period. Consumers value the ability to browse extensive product ranges, read detailed reviews, and compare prices from the comfort of their homes. This customization allows consumers to find specific synbiotic formulations tailored to their unique health needs, which may not be available in local stores. Additionally, subscription services provide automatic replenishment, ensuring consistent intake and improving therapeutic outcomes. As per Deloitte, 60% of online shoppers prefer subscription models for recurring health products due to time savings and cost benefits. The seamless integration of mobile apps and web platforms facilitates easy reordering and tracking, enhancing user engagement. This digital convenience appeals particularly to younger demographics and working professionals who prioritize efficiency, driving rapid adoption of non store based channels for synbiotic purchases.
By Packaging Material Insights
The plastic segment was accounted in holding a dominant share of the Europe Synbiotic Products Market in 2025 due to its cost efficiency and versatility in design, which accommodate various product formats. Manufacturers favor plastic for its ability to be molded into diverse shapes such as bottles, cups, and pouches, suitable for drinks, yogurts, and supplements. The European Plastic Converters report that production costs for plastic containers are 25% lower than glass or metal alternatives, allowing companies to maintain competitive pricing. This economic advantage is crucial in a price sensitive market where consumers compare functional foods with standard options. Additionally, plastic offers excellent barrier properties against moisture and oxygen, protecting sensitive probiotic strains from degradation. The lightweight characteristic also reduces transportation costs and carbon footprint during logistics by aligning with some sustainability goals related to fuel efficiency.
The paper packaging segment is expected to witness a fastest CAGR of 11.4% during the forecast period with the stringent sustainability mandates and shifting consumer preferences towards eco-friendly solutions. According to the European Environment Agency, regulations targeting single use plastics have prompted a 20% annual increase in the adoption of paper-based packaging alternatives in the food sector. This demand drives manufacturers to innovate with paper boards and cartons for synbiotic powders and solid supplements. Advances in coating technologies now allow paper to protect moisture sensitive probiotics effectively, addressing previous limitations. This shift aligns with corporate social responsibility goals and brand differentiation strategies. The compostable nature of many paper options appeals to environmentally conscious consumers, driving rapid adoption. Regulatory support and consumer advocacy create a favorable environment for paper packaging to outpace other materials in growth rate.
REGIONAL ANALYSIS
Germany Market Analysis
Germany was the top performer in the Europe Synbiotic Products Market by accounting for 32.1% of share in 2025 with a strong culture of preventive healthcare and high consumer awareness regarding gut health. The country’s advanced pharmaceutical industry supports rigorous scientific validation, enhancing consumer trust in product efficacy. Retailers in Germany emphasize quality and certification, with organic synbiotic products gaining significant traction. Strict regulatory adherence ensures high product standards, fostering consumer confidence. Major pharmacy chains actively promote synbiotic brands by leveraging professional endorsements.
United Kingdom Market Analysis
The United Kingdom synbiotic products market was ranked second by holding 18.4% of share in 2025 with the high urbanization and a growing interest in holistic wellness solutions. Consumers in the UK are highly influenced by digital trends and social media, driving demand for innovative synbiotic formats such as shots and gummies. Retail giants like Tesco and Sainsbury’s have expanded their free from and functional aisles by improving accessibility. The online sales of health supplements grew by 18%, reflecting the shift towards digital procurement. The NHS focus on preventive care further legitimizes synbiotic use, with general practitioners occasionally recommending probiotics for antibiotic associated diarrhea. Additionally, the multicultural population introduces diverse dietary preferences, encouraging brands to develop varied flavor profiles and formulations.
France Market Analysis
France synbiotic products market growth is likely to grow with the rich culinary heritage and increasing integration of functional benefits into traditional dairy products. According to the study, the French spend approximately 15% of their household budget on food, with a growing portion allocated to health oriented items. The popularity of fermented foods like yogurt and cheese provides a natural platform for synbiotic enrichment. Consumers in France value taste alongside health benefits, prompting manufacturers to focus on sensory appeal. The National Institute for Agricultural Research reports that clinical studies on local probiotic strains have boosted consumer confidence in domestic brands. Retailers such as Carrefour and Auchan prioritize private label synbiotic lines, offering affordable options to mass markets. Additionally, the government’s national nutrition health program encourages healthy eating habits, indirectly supporting synbiotic consumption.
Italy Market Analysis
Italy synbiotic products market growth is driven by increasing health consciousness and the adaptation of traditional Mediterranean diets to include functional elements. Pharmacists play a crucial role in educating consumers, with 60% of synbiotic supplements sold through pharmacy channels, as per the study. This professional endorsement enhances credibility and drives trial. Additionally, the tourism industry exposes Italians to global health trends, accelerating adoption of international synbiotic brands. Urban centers like Milan and Rome lead in premium product consumption, while rural areas follow with traditional formats. The strong emphasis on natural ingredients resonates with synbiotic formulations using plant-based prebiotics.
Spain Market Analysis
Spain synbiotic products market growth is fueled by rising health awareness and the integration of functional foods into daily routines. This prevalence drives demand for synbiotic interventions in both food and supplement forms. The dairy industry has responded by launching numerous synbiotic yogurt varieties, capturing mainstream attention. Pharmacies also contribute significantly by offering specialized synbiotic supplements recommended by healthcare professionals. The warm climate influences consumption patterns, with refreshing synbiotic drinks gaining popularity during summer months. Government initiatives promoting healthy aging further support market expansion.
COMPETITIVE LANDSCAPE
The competition in the Europe Synbiotic Products Market is characterized by intense rivalry among established multinational corporations and emerging niche brands seeking to capture market share. Large dairy conglomerates leverage their extensive distribution networks and brand recognition to dominate mainstream segments, while specialized biotechnology firms focus on high potency supplements and personalized solutions. Price competition is moderate due to the premium nature of functional foods, but private label offerings from major retailers exert pressure on branded products. Innovation serves as a key differentiator, with companies constantly launching new formats and strains to appeal to health-conscious consumers. Regulatory compliance creates barriers to entry, favoring players with robust scientific validation capabilities. Digital transformation has intensified competition, as online platforms enable direct to consumer models that bypass traditional retail channels. Collaborations with healthcare professionals enhance credibility and drive prescription-based sales.
KEY MARKET PLAYERS
Some of the notable companies in the Europe synbiotic products market are
- Seed Health, Inc
- Sabinsa Corporation
- Biomin America Inc
- Yakult Honsha Co., Ltd
- H&H Group
- The Kellogg Company
- Danone S.A.
- General Mills, Inc. (US)
- Pfizer Inc. (US)
- Daflorn Ltd. (Bulgaria)
- United Naturals
- Probiotical S.p.A.
Top Players in the Market
- Danone stands as a pivotal force in the Europe Synbiotic Products Market by leveraging its extensive dairy expertise to integrate advanced synbiotic formulations into mainstream consumer goods. The company actively invests in scientific research to validate the efficacy of its proprietary probiotic strains, ensuring robust clinical backing for its product claims. Recent initiatives include the expansion of its Actimel and Activia lines with enhanced prebiotic fibers, catering to the growing demand for comprehensive gut health solutions. Danone collaborates with leading research institutions to explore new bacterial strains and delivery mechanisms, fostering continuous innovation. The company also emphasizes sustainability in its packaging and sourcing practices, aligning with European consumer values. Through strategic partnerships with healthcare professionals, Danone enhances consumer trust and education regarding synbiotic benefits. Its strong distribution network across supermarkets and pharmacies ensures wide availability, reinforcing its market presence.
- Nestle plays a significant role in the Europe Synbiotic Products Market by utilizing its vast resources and global reach to develop innovative health focused solutions. The company integrates synbiotic ingredients into a diverse portfolio ranging from infant nutrition to adult wellness supplements, addressing various life stage needs. Nestle Health Science division spearheads research into personalized nutrition, leveraging digital tools to tailor synbiotic recommendations based on individual microbiome profiles. The company actively engages with medical professionals to promote evidence based usage of synbiotics for specific health conditions. Nestle also prioritizes sustainable sourcing and eco friendly packaging, responding to environmental concerns. Its robust supply chain ensures consistent product quality and availability across multiple European markets.
- Chr. Hansen contributes significantly to the Europe Synbiotic Products Market as a leading supplier of high quality probiotic cultures and prebiotic ingredients. The company focuses on developing specialized bacterial strains with proven health benefits, partnering with food and supplement manufacturers to create effective synbiotic formulations. Chr. Hansen invests heavily in research and development to discover new strains and improve production technologies, ensuring high viability and stability. Recent collaborations with academic institutions have led to breakthroughs in strain specificity for targeted health outcomes. The company provides comprehensive technical support to clients, helping them optimize product formulations and manufacturing processes. Chr. Hansen also emphasizes transparency and traceability in its supply chain, building trust with partners and consumers. Its global presence and local expertise enable it to serve diverse market needs across Europe.
Top Strategies Used by Key Market Participants
Key players in the Europe Synbiotic Products Market employ diverse strategies to maintain competitive advantage and drive growth. Product innovation remains a primary focus, with companies investing heavily in research and development to create novel formulations that address specific health needs such as immune support and mental well being. Strategic partnerships and collaborations with academic institutions enable firms to validate product efficacy through rigorous clinical trials, enhancing consumer trust and regulatory compliance. Expansion into digital health platforms allows brands to offer personalized nutrition advice and subscription services, fostering long term customer loyalty and recurring revenue streams. Sustainability initiatives are increasingly central to corporate strategies, with manufacturers adopting eco-friendly packaging and ethical sourcing practices to align with consumer values and regulatory requirements.
MARKET SEGMENTATION
This research report on the Europe synbiotic products market has been segmented and sub-segmented into the following categories.
By Type
- Dietary Supplements
- Drinks
- Sandwiches
- Dairy and Frozen Desserts
- Bakery And Cake Shop
By Distribution Channel
- Store-based
- Non-Store based
By Application
- Medication
- Animal Food
- Food and Beverages
By Packaging Material
- Paper
- Plastic
- Cup
- Metal
By Country
- UK
- France
- Spain
- Germany
- Italy
- Russia
- Sweden
- Denmark
- Switzerland
- Netherlands
- Turkey
- Czech Republic
- Rest of Europe