- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
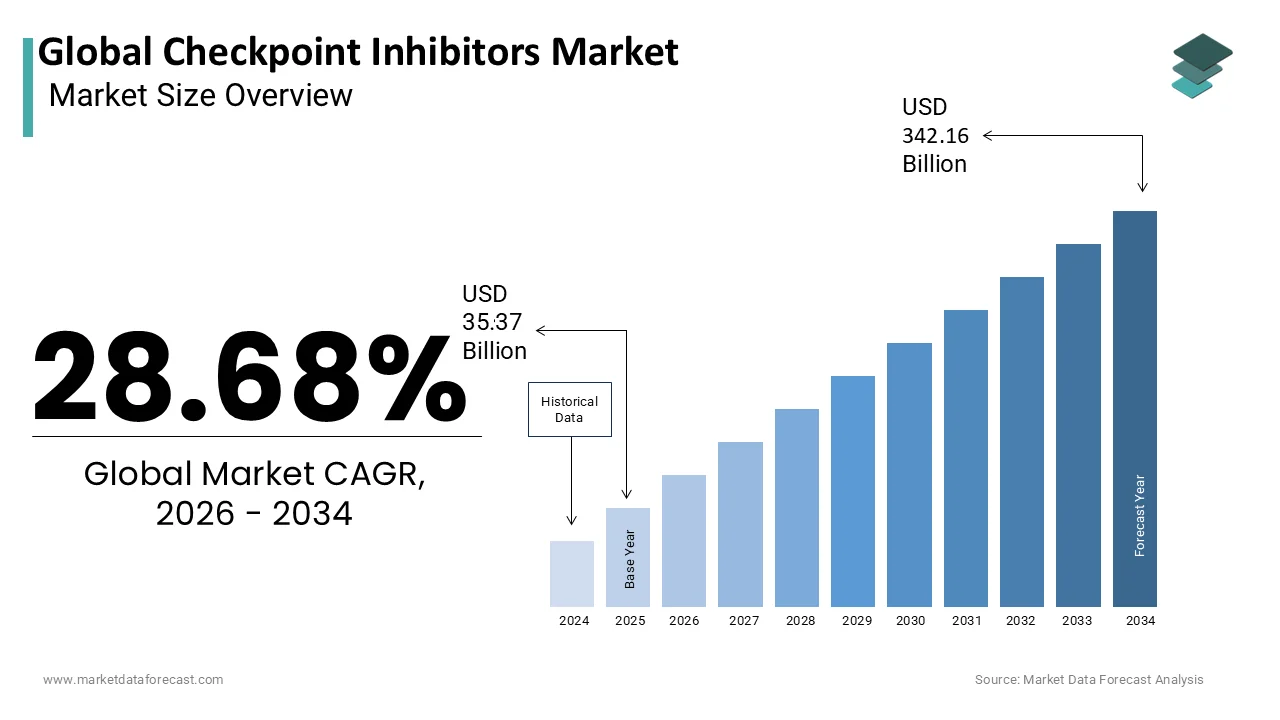
$35.37 BnMarket Estimate, 2026
$45.51 BnMarket Forecast, 2034
$342.16 BnCAGR, 2026–2034
28.68%Executive Summary: Global Checkpoint Inhibitors Market
- Market Scope: Comprehensive global checkpoint inhibitors market analysis covering drug classes, clinical application verticals, and regional leadership frameworks across North America, Europe, Asia-Pacific, Latin America, and MEA.
- Market Valuation: Valued at USD 35.37 billion (2025), estimated at USD 45.51 billion in 2026, and projected to reach USD 342.16 billion by 2034, registering a robust CAGR of 28.68% (2026–2034).
- Primary Growth Drivers: Rising global prevalence of cancer, increasing government funding and R&D support for immunotherapy, favorable reimbursement policies, expanding pharmaceutical pipelines for checkpoint inhibitor drugs, and rising adoption of precision medicine and combination therapies.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (2025 Position) | Fastest-Growing Segment |
|---|---|---|
| By Drug | CTLA-4 & PD-1 Inhibitors (accounting for major market shares due to established combination treatment strategies and high response rates) | Next-generation PD-L1 and specialized checkpoint inhibitor formulations |
| By Application | Lung Cancer (capturing major market share driven by rising mortality rates and standard treatment adoption like NSCLC care) | Melanoma & Renal Cancer Applications |
| By Region | North America (dominating the global market due to advanced healthcare infrastructure, high therapy adoption, and extensive R&D) | Asia-Pacific (fastest-growing regional market driven by large patient populations and rising healthcare investments in China, Japan, and India) |
Major Market Players & Market Structure
Market Structure: Highly competitive global immuno-oncology landscape navigating high R&D costs, immune-related side effects, and stringent regulatory approval processes, offset by strong industry collaborations, clinical trials, and personalized medicine advancements.
Key Companies: Merck & Co. Inc., Bristol-Myers Squibb, Roche, AstraZeneca, Ono Pharmaceutical Co., Ltd., Juno Therapeutics, Novartis International AG, and Kite Pharma.
 Download Free Sample Report
Global Checkpoint Inhibitors Market Size
The Global Checkpoint Inhibitors Market is projected to grow from USD 35.37 billion in 2025 to USD 45.51 billion in 2026 and reach USD 342.16 billion by 2034, registering a CAGR of 28.68% during the forecast period from 2026 to 2034.
Checkpoint inhibitors are a type of drug that helps your immune system fight cancer by releasing the natural "brakes" that stop immune cells from attacking tumours. These monoclonal antibodies target key regulatory pathways such as PD-1, PD-L1, and CTLA-4 to restore T cell activity against malignant tumours. The clinical significance of this therapeutic class is underscored by its transformative impact on survival rates for previously untreatable malignancies. According to the American Cancer Society, approximately 609,820 people are expected to die from cancer in the United States in 2023, highlighting the urgent need for effective systemic treatments. Furthermore, as per sources, immunotherapy has become a standard of care for many types of cancer, including melanoma, lung cancer, and renal cell carcinoma. This broadening indication landscape drives substantial demand for checkpoint inhibitors across oncology practices. The ability of these drugs to induce durable responses in a subset of patients distinguishes them from traditional chemotherapy and targeted therapies. Consequently, pharmaceutical companies continue to invest heavily in developing next-generation inhibitors and combination regimens. The market is characterised by intense innovation aimed at overcoming resistance mechanisms and expanding patient eligibility. As clinical evidence accumulates regarding long-term benefits, checkpoint inhibitors remain central to modern oncology treatment protocols globally.
MARKET DRIVERS
Rising Prevalence of Cancer and Shift Toward Immunotherapy
The escalating global burden of cancer, coupled with a paradigm shift toward immunotherapeutic interventions, is contributing to the expansion of the checkpoint inhibitors market. According to the World Health Organisation, cancer is the leading or second leading cause of death before age 70 in 112 countries, creating an immense patient pool requiring advanced systemic therapies. This epidemiological reality drives healthcare systems to adopt treatments that offer improved survival outcomes compared to conventional modalities. According to sources, immunotherapy usage has increased drastically across major global cancer treatment facilities over the past several years, reflecting rapid and widespread clinical adoption. Additionally, the ageing population in developed regions contributes to higher incidence rates as immune surveillance declines with age. According to the Centers for Disease Control and Prevention and global health agencies, the absolute number of new cancer cases worldwide is projected to rise significantly by 2040 due to population growth and ageing, necessitating highly scalable treatment frameworks. Checkpoint inhibitors address this need by providing a mechanism to harness the patient’s own immune system, offering potential for long-term remission. This clinical advantage encourages physicians to prescribe these agents earlier in the treatment algorithm. The widespread recognition of immunotherapy as a pillar of cancer care ensures sustained demand. Pharmaceutical manufacturers respond by expanding production capacities and securing supply chains to meet growing prescription volumes. This demographic and clinical trend solidifies the foundational growth driver for the market.
Expanding Regulatory Approvals and Indication Broadening
The continuous expansion of regulatory approvals for these inhibitors across diverse tumour types significantly propels the growth of the checkpoint inhibitors market. This expansion thereby widens the eligible patient population. According to the Food and Drug Administration, there are currently more than seven approved checkpoint inhibitor drugs (such as ipilimumab, pembrolizumab, nivolumab, cemiplimab, atezolizumab, durvalumab, and avelumab) covering broad clinical indications ranging from metastatic melanoma to non-small cell lung cancer and Hodgkin lymphoma. Each new approval opens access to thousands of additional patients who previously had limited therapeutic options. The European Medicines Agency has similarly accelerated approvals based on robust clinical trial data demonstrating superior efficacy over standard care. The National Comprehensive Cancer Network updates its guidelines regularly to include checkpoint inhibitors for emerging indications such as triple-negative breast cancer and gastric cancer. These guideline changes influence prescribing behaviour and reimbursement decisions globally. Furthermore, the approval of checkpoint inhibitors in adjuvant settings for early-stage disease expands their use beyond palliative care. As per the Journal of Clinical Oncology and associated oncology literature, adjuvant therapy with pembrolizumab alone or in combination has significantly reduced the risk of recurrence or death (with a hazard ratio demonstrating over a 30% to 49% relative risk reduction depending on the specific trial and combination) in high-risk melanoma patients. This shift toward earlier intervention increases treatment duration and drug consumption. Regulatory support for biomarker-agnostic approvals also allows treatment regardless of tumour origin, further broadening applicability. These regulatory milestones create a favourable environment for sustained market expansion and investment.
MARKET RESTRAINTS
High Treatment Costs and Reimbursement Challenges
The prohibitive cost of checkpoint inhibitor therapies remains a serious obstacle to market accessibility. This also hampers widespread adoption, particularly in resource-constrained healthcare systems. According to sources, the annual cost of checkpoint inhibitor therapy can exceed 100,000 to 150,000 dollars per patient, placing a substantial financial burden on payers and healthcare systems. This high price point leads to strict prior authorisation requirements and coverage denials, which delay or prevent patient access to life-saving treatments. As per studies, administrative burdens associated with insurance documentation and approval processes consume significant physician time and clinical resources. Additionally, out-of-pocket costs for patients under high deductible plans can be financially devastating, leading to treatment abandonment. According to the Commonwealth Fund, cost-related nonadherence is a growing issue in the United States, affecting chronic and acute care alike. In emerging markets, lack of universal health coverage limits availability to affluent segments only. Payers are increasingly demanding real-world evidence of cost-effectiveness before granting broad coverage. This scrutiny slows down formulary inclusion for newer agents. Hospitals may also restrict usage to specific high-value cases to manage budget impacts. These financial barriers restrict the total addressable market volume despite clinical demand. The market requires either an evolution in pricing models or the introduction of generic biosimilars. In the interim, cost will continue to serve as a critical constraint on expansion.
Severe Immune-Related Adverse Events and Safety Concerns
The occurrence of severe immune-related adverse events is a major safety concern that hinders the growth of the checkpoint inhibitors market. This factor limits the broader application of these inhibitors in clinical practice. According to the New England Journal of Medicine, up to 50% to 60% of patients treated with combination checkpoint inhibitor therapy (such as dual CTLA-4 and PD-1 blockade) experience severe grade 3 or 4 treatment-related adverse events requiring clinical intervention. These toxicities can affect any organ system, including the lungs, liver, heart, and endocrine glands, potentially leading to permanent damage or death. The Food and Drug Administration has issued a black box warning for the checkpoint inhibitor ipilimumab due to the risks of severe and fatal immune-mediated adverse reactions. This safety profile necessitates rigorous monitoring and management by specialised oncology teams, increasing the complexity of care delivery. According to research, managing complex immune-related toxicities poses an educational challenge for community oncologists, necessitating clear management guidelines to avoid referral bottlenecks. Fear of adverse events may also deter physicians from prescribing these agents to elderly or comorbid patients who are at higher risk. Additionally, the need for concurrent steroid treatment to manage toxicity can compromise antitumor efficacy. Patient anxiety regarding potential side effects further influences treatment acceptance. These safety concerns require extensive patient education and supportive care infrastructure. Until predictive biomarkers for toxicity are identified and validated, safety risks will continue to restrain optimal utilisation. Consequently, this will also limit market penetration.
MARKET OPPORTUNITIES
Development of Combination Therapies and Novel Targets
The strategic development of combination therapies involving these inhibitors and other modalities offers a lucrative opportunity to overcome resistance and enhance response rates, which are anticipated to drive the expansion of the checkpoint inhibitors market. According to oncology literature and Nature Reviews, there are more than 3,000 active clinical trials globally investigating T-cell modulators and immune checkpoint inhibitors as single agents or in combination with chemotherapy, radiation, targeted therapies, or other immunotherapies. These combinations aim to create synergistic effects that improve tumour infiltration and immune activation. The National Cancer Institute supports research into dual checkpoint blockade, such as PD-1 and CTLA-4 inhibition, which has shown superior efficacy in melanoma and renal cell carcinoma. Additionally, the exploration of novel checkpoints like LAG-3, TIM-3, and TIGIT offers new avenues for differentiation. As per studies, adding a LAG-3 inhibitor to PD-1 blockade significantly improved progression-free survival in previously untreated patients with advanced or metastatic melanoma, validating the dual checkpoint inhibition approach. Pharmaceutical companies are investing heavily in these multi-mechanism strategies to extend patent life and capture larger market shares. Combination regimens also allow for dose optimisation, reducing toxicity while maintaining efficacy. This scientific evolution transforms checkpoint inhibitors from standalone agents to backbone components of comprehensive cancer care. The success of these combinations drives repeat prescriptions and long-term treatment adherence. An increasing number of combination therapies are gaining regulatory approval. As a result, the market scope is expanding significantly beyond traditional monotherapy applications.
Expansion into Early Stage and Adjuvant Settings
The expansion of checkpoint inhibitor indications into early-stage and adjuvant settings paves the way for the growth of their global market. This shift moves treatment from late-stage palliation to curative intent. According to The Lancet Oncology, adjuvant therapy with checkpoint inhibitors has demonstrated significant improvements in disease-free survival for patients with resected stage III melanoma and non-small cell lung cancer. This clinical evidence supports the use of these drugs in earlier disease stages where patient populations are larger, and treatment duration is defined. The American Society of Clinical Oncology guidelines now recommend adjuvant immunotherapy for several high-risk cancers, expanding the eligible patient pool substantially. Treating earlier-stage disease also reduces the long-term burden of metastatic care on healthcare systems. Payers are increasingly recognising the value of curative-intent treatments despite higher upfront costs. The National Comprehensive Cancer Network continues to update guidelines to include neoadjuvant approaches using checkpoint inhibitors before surgery. This shift increases the volume of patients receiving therapy as early-stage diagnoses are more common than metastatic ones. Furthermore, the defined treatment duration in adjuvant settings improves predictability for supply chain management. As clinical data matures for other tumour types, the adjuvant market segment will grow rapidly, offering stable and predictable revenue streams for manufacturers.
MARKET CHALLENGES
Lack of Predictive Biomarkers for Patient Selection
The absence of universally reliable predictive biomarkers for patient selection is a critical challenge to the checkpoint inhibitors market. This deficit leads to inefficient resource utilisation and suboptimal clinical outcomes. According to the Journal of Clinical Oncology, only 20 to 40 % of patients respond to single-agent checkpoint inhibitors, depending on the cancer type, indicating a large non-responder population. Current biomarkers such as PD-L1 expression, tumour mutational burden, and microsatellite instability have limited sensitivity and specificity, leading to false positives and negatives. As per sources, variability in assay formats, scoring cutoffs, and performance metrics creates ongoing challenges for consistent diagnostic biomarker interpretation across different laboratories. This uncertainty forces clinicians to rely on trial and error, exposing non-responders to unnecessary toxicity and cost. As per studies, future research priorities emphasise the development of composite biomarkers that integrate genomic and immunologic parameters to guide precision medicine decisions. Without accurate selection tools, healthcare systems struggle to justify the high cost of treatment for uncertain benefits. Pharmaceutical companies face challenges in designing efficient clinical trials when patient enrichment strategies are imperfect. This diagnostic gap hinders the precision medicine promise of checkpoint inhibitors. Developing robust, validated biomarkers requires significant investment and collaboration between industry, academia, and regulators. Until this challenge is addressed, a significant portion of the market potential remains unrealised due to ineffective treatment allocation.
Emergence of Primary and Acquired Resistance Mechanisms
The emergence of primary and acquired resistance mechanisms poses a formidable biological hurdle that limits the long-term efficacy of checkpoint inhibitors in the global market. According to Cell Press, tumours develop resistance through various pathways, including downregulation of antigen presentation, mutations in interferon gamma signalling, and recruitment of immunosuppressive cells. These adaptations allow cancer cells to evade immune detection despite checkpoint blockade, leading to disease progression after initial response. As per research, understanding underlying tumour resistance mechanisms is critical for designing effective next-generation therapies, though the biological pathways involved remain highly complex. Primary resistance prevents any initial benefit, while acquired resistance leads to relapse after a period of control, both limiting overall survival gains. The lack of effective second-line options for patients who fail checkpoint inhibitors creates a significant unmet medical need. Clinical trials investigating reversal of resistance are ongoing but have yet to yield widely approved solutions. This biological hurdle restricts the durability of response and necessitates continuous development of novel agents. Physicians face difficult decisions when managing progressing patients, often reverting to less effective chemotherapies. The dynamic nature of tumour evolution means that static treatment strategies are insufficient. Overcoming resistance requires personalised approaches based on longitudinal monitoring, which is currently not standard practice. This challenge underscores the need for sustained innovation in the checkpoint inhibitors market.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Analysed | By Drug, Application, and Region |
| Various Analyses Covered | Global, Regional & Country Level Analysis, Segment-Level Analysis; DROC; PESTLE Analysis; Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Regions Analysed | North America, Europe, Asia Pacific, Latin America, the Middle East, and Africa |
| Market Leader Profiled | Merck & Co. Inc., Bristol-Myers Squibb, Roche, AstraZeneca, Ono Pharmaceutical Co |
SEGMENTAL ANALYSIS
By Drug Insights
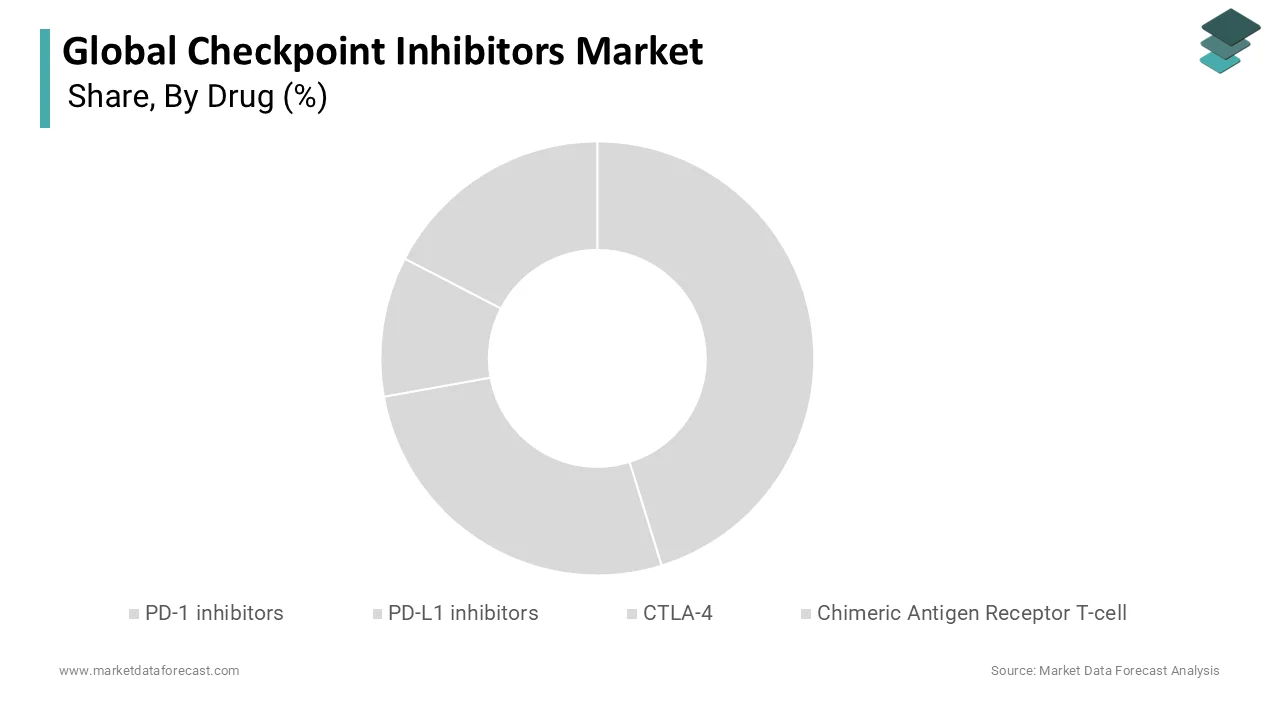
The PD-1 inhibitors segment dominated the checkpoint inhibitors market and accounted for a substantial share in 2025. This dominance of the segment was driven by its proven efficacy across a wide spectrum of solid tumours and hematologic malignancies. According to the Food and Drug Administration, drugs such as pembrolizumab and nivolumab have received approvals for over 20 distinct cancer types, including non-small cell lung cancer, melanoma and renal cell carcinoma. This extensive label expansion allows oncologists to prescribe these agents for a vast majority of patients requiring immunotherapy. The National Comprehensive Cancer Network guidelines recommend PD-1 inhibitors as first-line therapy for several advanced cancers, reflecting strong clinical consensus. Furthermore, the favourable safety profile compared to CTLA-4 inhibitors encourages broader adoption in community settings. As per the American Society of Clinical Oncology, PD-1 blockade has become the backbone of combination regimens, enhancing its utility. The ability to induce durable responses in a significant subset of patients drives high prescription volumes. Pharmaceutical companies continue to invest in post-marketing studies to validate efficacy in rare cancers, further expanding the addressable population. This versatility ensures that PD-1 inhibitors remain the most prescribed class of checkpoint inhibitors globally. The established track record of survival benefits reinforces physician confidence and patient acceptance. Consequently, this segment generates the highest revenue share driven by volume and breadth of application.
The robust reimbursement landscape and mature manufacturing infrastructure for PD-1 inhibitors significantly contribute to their market dominance. According to the Centers for Medicare and Medicaid Services, major PD-1 inhibitors are covered under Part B and Part D plans, ensuring financial accessibility for millions of beneficiaries. Private insurers generally follow these coverage determinations, reducing administrative barriers for prescribing physicians. According to sources, manufacturer co-pay assistance programs and foundation grants serve to alleviate the high out-of-pocket exposure that many cancer patients face when prescribed advanced immunotherapies. Additionally, the large-scale production capabilities of key manufacturers ensure consistent supply meeting global demand. The World Health Organisation includes certain PD-1 inhibitors in its essential medicines lists, facilitating access in developing regions. Economies of scale have allowed manufacturers to optimise pricing strategies, maintaining competitiveness against newer entrants. The long patent life remaining for key agents provides stability for continued investment in marketing and education. Hospitals prefer stocking PD-1 inhibitors due to their predictable demand and streamlined procurement processes. This operational efficiency supports high utilisation rates across healthcare facilities. The combination of financial accessibility and supply reliability cements the leadership of PD 1 inhibitors in the market.
The chimeric antigen receptor T-cell therapies segment is likely to experience the fastest CAGR of 28.5% from 2026 to 2034 due to revolutionary efficacy in treating refractory blood cancers. According to the Journal of Clinical Oncology, CAR T cell therapies have achieved complete remission rates exceeding 80 % in pediatric acute lymphoblastic leukaemia, transforming outcomes for previously untreatable patients. This dramatic clinical success has accelerated regulatory approvals and clinical adoption. The Food and Drug Administration has approved multiple CAR T cell products for diffuse large B-cell lymphoma and multiple myeloma, expanding the eligible patient base. As per the American Society of Haematology, ongoing trials are exploring solid tumour applications, potentially unlocking massive new markets. Technological advancements in viral vector production have reduced manufacturing times, improving accessibility. The National Cancer Institute invests heavily in next-generation CAR designs targeting novel antigens to overcome resistance. These innovations enhance potency and durability of response, driving physician interest. As manufacturing capacities expand, the bottleneck of personalised production is easing. This technological momentum positions CAR T cell therapy as the most dynamic growth engine in the immunotherapy landscape. The promise of curative potential drives premium pricing and rapid uptake in specialised centres.
The rapid expansion of specialised manufacturing infrastructure and supportive regulatory frameworks is accelerating the growth of the CAR T cell segment. According to research, specialised cell therapy manufacturing organisations are heavily expanding physical facility footprints across North America and Europe to address historic capacity limitations and delivery constraints. The Food and Drug Administration has established expedited review pathways for regenerative medicine products, reducing time to market for new candidates. The European Medicines Agency similarly offers priority designation for innovative cell therapies, facilitating faster approval. As per the International Society for Cellular Therapy, standardisation of production protocols is improving consistency and reducing costs. Government grants and public-private partnerships are funding research into allogeneic CAR T cells, which offer off-the-shelf availability. This shift from autologous to allogeneic approaches promises to democratize access and lower prices. The National Institutes of Health supports clinical trials evaluating Segmental Analysis of the Checkpoint Inhibitors Market.
By Application Insights
The lung cancer segment led the checkpoint inhibitors market and captured a significant share in 2025. This leading position of the segment was attributed to its high incidence rate and the establishment of immunotherapy as standard first-line care. According to the American Cancer Society, lung cancer is the leading cause of cancer death worldwide, with approximately 238340 new cases diagnosed annually in the United States alone. This massive patient pool creates substantial demand for effective systemic therapies. The National Comprehensive Cancer Network guidelines recommend checkpoint inhibitors combined with chemotherapy for most patients with advanced non-small cell lung cancer regardless of PD-L1 status. This broad indication ensures that nearly every newly diagnosed advanced patient receives immunotherapy. The Food and Drug Administration has approved multiple PD-1 and PD-L1 inhibitors specifically for lung cancer indications, reinforcing their central role. As per the Journal of Thoracic Oncology and related lung cancer trials, first-line checkpoint inhibitor regimens have significantly improved overall survival metrics in advanced metastatic settings compared to historical chemotherapy benchmarks. This survival benefit drives strong physician preference and patient acceptance. Screening programs identifying early-stage disease also increase the number of patients eligible for adjuvant immunotherapy. The sheer volume of diagnoses combined with universal treatment recommendations sustains the dominance of the lung cancer segment. Continuous updates to guidelines incorporating new trial data further solidify this position.
The extensive clinical trial pipeline and integration of biomarker testing in lung cancer management further reinforce the leading position of this application segment. According to the National Cancer Institute, there are hundreds of active clinical trials exploring immune checkpoint inhibitors for lung cancer, focusing on combinations with targeted drugs, chemotherapy, and radiation. This intense research activity continuously expands the therapeutic arsenal and refines patient selection criteria. The College of American Pathologists emphasises routine PD-L1 testing for all lung cancer patients, ensuring appropriate use of immunotherapy. This diagnostic integration creates a seamless workflow from diagnosis to treatment initiation. Pharmaceutical companies prioritise lung cancer in their development portfolios due to the large market size and clear regulatory pathways. The American Society of Clinical Oncology presents numerous studies annually demonstrating efficacy in various subgroups, including squamous and nonsquamous histologies. Real-world evidence registries track outcomes supporting broader adoption in community practices. The availability of liquid biopsy tests allows for monitoring of treatment response and resistance, guiding subsequent lines of therapy. This comprehensive ecosystem of diagnostics, trials, and clinical practice ensures that lung cancer remains the primary driver of checkpoint inhibitor consumption. The depth of scientific understanding translates directly into high market penetration.
The melanoma segment is expected to exhibit a noteworthy CAGR of 19.2% during the forecast period, owing to its status as the prototype disease for checkpoint inhibitor development and exceptionally high response rates. According to the American Academy of Dermatology, the incidence of cutaneous melanoma has risen consistently over recent decades, ranking it among the most frequently diagnosed malignant conditions in young adult demographics. This demographic trend increases the urgency for effective treatments that preserve quality of life. The New England Journal of Medicine published landmark trials showing that combination checkpoint inhibition achieves five-year survival rates of over 50 % in metastatic melanoma, an unprecedented milestone. These results have shifted treatment paradigms from palliative to potentially curative intent. The National Comprehensive Cancer Network recommends dual checkpoint blockade as preferred first-line therapy for advanced disease. The high visibility of melanoma in public health campaigns raises awareness and drives early detection. Early-stage patients are increasingly treated with adjuvant immunotherapy to prevent recurrence, expanding the treatment window. The Skin Cancer Foundation advocates for regular screening, increasing the number of diagnosed cases eligible for intervention. This combination of rising incidence and superior efficacy fuels rapid market growth. Physicians are highly experienced in managing melanoma with immunotherapy, reducing hesitation in prescribing. The strong clinical data foundation supports aggressive expansion into earlier stages and combination regimens.
The expansion of checkpoint inhibitor indications into adjuvant and neoadjuvant settings for melanoma is propelling significant market growth. According to The Lancet Oncology, adjuvant therapy with PD-1 inhibitors reduces the relative risk of recurrence by 35% to 43% in patients with completely resected stage III and IV melanoma. This evidence has led to widespread adoption of post-surgical immunotherapy to prevent metastasis. The Society of Surgical Oncology now incorporates immunotherapy into standard surgical care pathways, increasing treatment duration and drug consumption. Neoadjuvant trials are showing promising results in shrinking tumours before surgery, potentially improving operability. The Melanoma Research Alliance funds studies exploring shorter-duration adjuvant therapy to reduce toxicity while maintaining efficacy. These refinements make treatment more attractive to patients and providers. The high cost of treating metastatic disease incentivises payers to cover adjuvant therapy as a cost-saving measure. Patient advocacy groups support access to these life-extending treatments, influencing policy decisions. The shift toward earlier intervention captures a larger patient population than metastatic care alone. As guidelines evolve to include stage II high-risk patients, the addressable market expands further. This strategic move from late-stage to early-stage care drives exceptional growth rates in the melanoma segment.
COUNTRY LEVEL ANALYSIS
North America Checkpoint Inhibitors Market Analysis
North America was the top performer in the global checkpoint inhibitors market and occupied a commanding share in 2025. This dominance was driven by advanced healthcare infrastructure and high adoption rates of innovative therapies. According to theCenterss for Disease Control and Prevention, cancer is the second leading cause of death in the United States, creating immense demand for effective treatments. The Food and Drug Administration approves new checkpoint inhibitors rapidly, often granting breakthrough therapy designation, which accelerates market entry. The presence of major pharmaceutical companies fosters a robust ecosystem of research and development. As per the American Cancer Society, over 1.9 million new cancer cases are diagnosed annually in the US, providing a large patient base. High healthcare expenditure allows for widespread access to expensive immunotherapies despite cost concerns. Private insurance coverage and Medicare reimbursement policies facilitate patient access to the latest treatments. Academic medical centres serve as hubs for clinical trials, attracting patients seeking cutting-edge care. The strong regulatory framework ensures high-quality standards, building trust among providers. This combination of innovation, funding, and demand sustains North America's leadership position. The region continues to drive global trends in checkpoint inhibitor usage and development.
Europe Checkpoint Inhibitors Market Analysis
Europe was the next prominent region in the checkpoint inhibitors market in 2025. This position was propelled by centralised healthcare systems and stringent health technology assessments. According to the European Commission, cancer affects millions of Europeans annually, with lung and colorectal cancers being predominant. The European Medicines Agency provides harmonised approval processes facilitating simultaneous market access across member states. However, reimbursement decisions are made at national levels, leading to variability in access speeds. According to the Organisation for Economic Co-operation and Development, healthcare spending in Europe is substantial but focused on cost-effectiveness. Countries like Germany and France have established pathways for early access to innovative drugs. The European Society for Medical Oncology issues guidelines that influence prescribing patterns across the continent. Public healthcare systems negotiate bulk pricing, reducing costs but potentially limiting profit margins for manufacturers. Despite these challenges, the high burden of disease ensures steady demand. Ageing populations in Southern and Eastern Europe further drive consumption. Collaborative research initiatives such as Horizon Europe support biomarker discovery and clinical trials. Europe remains a critical market balancing innovation with fiscal responsibility.
Asia-Pacific Checkpoint Inhibitors Market Analysis
The Asia-Pacific region is emerging as the fastest-growing region in the checkpoint inhibitors market due to rising cancer incidence and improving healthcare access. According to the World Health Organisation, the region accounts for nearly half of global cancer cases due to large populations and lifestyle changes. Governments in China, Japan,n and South Korea are investing heavily in domestic biopharmaceutical industries to reduce reliance on imports. The National Medical Products Administration in China has accelerated approval timelines for innovative oncology drugs. Local manufacturers are developing biosimilars and novel checkpoint inhibitors, increasing competition and lowering prices. According to sources, pan-Asian cooperative oncology frameworks actively promote specialised medical education and clinical trial training to enhance providers' capability for administering advanced immunotherapies. Rising disposable incomes and expanding insurance coverage improve patient affordability. Medical tourism in countries like Thailand and India attracts international patients seeking advanced care. The burden of hepatitis B-related liver cancer drives specific demand for immunotherapies in this region. Demographic shifts toward ageing populations mirror trends in developed nations, sustaining long-term growth. Asia Pacific presents immense potential for volume-driven expansion.
Latin America Checkpoint Inhibitors Market Analysis
Latin America shows steady growth in the checkpoint inhibitors market because of gradual improvements in healthcare infrastructure and regulatory harmonisation. According to the Pan American Health Organisation, cancer mortality rates are declining in some countries due to better access to treatments. Brazil and Mexico lead the region in adopting new oncology therapies through public and private healthcare systems. The local regulatory agencies are aligning with international standards, facilitating faster approvals. Economic challenges and currency fluctuations remain barriers to widespread access for high-cost therapies. However, patient assistance programs and generic entry are improving affordability. The Latin American Cooperative Oncology Group conducts regional clinical trials, generating local evidence to support guideline adoption. Private insurance sectors in urban areas drive demand for premium immunotherapies. Government initiatives to strengthen cancer control plans include provisions for innovative drugs. Awareness campaigns are increasing early detection rates, expanding the treatable population. While per capita spending is lower than in North America, the large population base offers significant volume opportunities. The market is evolving toward greater equity and access.
The Middle East and Africa Checkpoint Inhibitors Market Analysis
The Middle East and Africa region is anticipated to expand notably in the checkpoint inhibitors market from 2026 to 2034, owing to government healthcare modernisation efforts. According to the World Bank, Gulf Cooperation Council countries are investing billions in healthcare infrastructure, including specialised cancer centres. The United Arab Emirates and Saudi Arabia are becoming hubs for medical excellence, attracting top talent and technology. In Africa, the burden of infection-related cancers such as cervical and liver cancer creates specific demand for immunotherapies. The African Union supports initiatives to improve access to essential medicines, including cancer drugs. Limited local manufacturing means reliance on imports, but international partnerships are improving supply chains. Non-governmental organisations play a crucial role in providing access to expensive therapies in low-income settings. Awareness of cancer is rising, leading to increased diagnosis and treatment-seeking behaviour. The Middle East Cancer Consortium facilitates collaboration and knowledge sharing among regional experts. While market size is currently small compared to other regions, the growth trajectory is positive. Strategic investments in healthcare will drive future adoption of checkpoint inhibitors.
COMPETITIVE LANDSCAPE
The competition in the Checkpoint Inhibitors Market is characterized by intense rivalry among established pharmaceutical giants and emerging biotechnology firms who strive to differentiate through efficacy and safety profiles. Leading companies compete primarily on the breadth of approved indications and the strength of clinical data supporting their products. The market sees significant activity in the development of next-generation inhibitors targeting novel checkpoints such as LAG-3 and TIGIT. Price competition is moderated by the high value of these life-saving therapies, but cost-effectiveness remains a key consideration for payers. Strategic alliances and licensing agreements allow firms to fill gaps in their pipelines and access new technologies. Intellectual property protection is crucial, with companies securing patents for proprietary molecules and formulations. Regulatory compliance and rapid approval pathways serve as major differentiators influencing market entry timing. Continuous investment in post-marketing studies and real-world evidence generation helps maintain physician confidence and loyalty. This dynamic environment drives rapid scientific advancement while challenging companies to demonstrate superior clinical utility and economic value to sustain their market positions.
KEY MARKET PLAYERS
Some of the companies that are playing a dominating role in the Global Checkpoint Inhibitors Market include:
- Merck & Co., Inc.
- Bristol-Myers Squibb
- Roche
- AstraZeneca
- Ono Pharmaceutical Co., Ltd.
- Juno Therapeutics
- Novartis International AG
- Kite Pharma
TOP LEADING PLAYERS IN THE MARKET
- Merck & Co Inc. maintains a leading position in the checkpoint inhibitors market through its flagship drug Keytruda, which is approved for numerous cancer indications. The company actively invests in extensive clinical trials to expand the therapeutic use of pembrolizumab across various tumor types and treatment settings. Recent actions include securing approvals for adjuvant therapies in early-stage cancers, which broadens the patient population eligible for treatment. Merck collaborates with diagnostic companies to develop companion tests, ensuring precise patient selection and improved outcomes. The company also focuses on manufacturing scalability to meet global demand while maintaining high quality standards. By prioritizing innovation and strategic partnerships, Merck strengthens its dominance in the immunotherapy sector. Its commitment to research and development ensures a robust pipeline of next-generation therapies. This approach solidifies its reputation as a key driver of progress in oncology care worldwide.
- Bristol Myers Squibb Company is a pivotal player in the checkpoint inhibitors market, known for pioneering drugs such as Opdivo and Yervoy. The company leverages its deep expertise in immuno-oncology to develop combination therapies that enhance efficacy and overcome resistance mechanisms. Recent initiatives involve expanding indications for nivolumab and ipilimumab in rare cancers and earlier stages of disease. Bristol Myers Squibb engages in strategic acquisitions to bolster its pipeline with novel immunotherapeutic agents and technologies. The company also invests in real-world evidence generation to support reimbursement and clinical adoption. By focusing on personalized medicine approaches, they address unmet needs in complex cancer cases. Their strong commercial infrastructure ensures broad access to treatments across diverse healthcare systems. This comprehensive strategy reinforces their leadership and drives sustained growth in the competitive landscape.
- F Hoffmann-La Roche Ltd contributes significantly to the checkpoint inhibitors market with its portfolio including Tecentriq and other innovative immunotherapies. The company emphasizes the integration of diagnostics and therapeutics to deliver precision medicine solutions for cancer patients. Recent actions include launching new formulations and combination regimens that improve patient convenience and clinical outcomes. Roche collaborates extensively with academic institutions and biotechnology firms to discover novel targets and biomarkers. The company also enhances its global supply chain capabilities to ensure consistent availability of critical medications. By focusing on data-driven insights, Roche optimizes treatment strategies for individual patients. Their commitment to sustainability and ethical practices builds trust among stakeholders. This holistic approach enables Roche to maintain a strong competitive edge and drive advancements in cancer care globally.
TOP STRATEGIES USED BY KEY PLAYERS
Key players in the Checkpoint Inhibitors Market employ diverse strategies to maintain competitiveness and drive innovation. Product differentiation through expanded indications and combination therapies remains a primary focus, allowing companies to capture larger patient populations. Strategic partnerships with diagnostic firms facilitate the development of companion tests,s enhancing precision and efficacy. Companies invest heavily in clinical research to explore novel targets and overcome resistance mechanisms. Expansion into emerging markets provides new growth opportunities and diversifies revenue streams. Additionally, many firms prioritize manufacturing excellence to ensure consistent supply and quality. Regulatory engagement accelerates approval processes and supports market access. These multifaceted approaches enable participants to address complex clinical needs and secure long-term success in the evolving oncology landscape.
GLOBAL CHECKPOINT INHIBITORS MARKET NEWS
- In February 2019, Merck & Co., Inc. announced that they had received US FDA approval for the checkpoint inhibitor “Keytruda,” which is used to treat Merkel cell carcinoma.
- For the treatment of non-small cell lung cancer in advanced stages, F. Hoffmann-La Roche Ltd. announced in January 2019 that they received US FDA approval for “Tecentriq, in combination with bevacizumab, paclitaxel, and carboplatin.
- In October 2018, for the treatment of advanced cutaneous squamous cell carcinoma, Regeneron announced that they had received US FDA approval for “Libtayo.”
MARKET SEGMENTATION
This research report on the global checkpoint inhibitors market has been segmented and sub-segmented based on the drug, application, and region.
By Drug
- PD-1 inhibitors
- PD-L1 inhibitors
- CTLA-4
- Chimeric Antigen Receptor T-cell
- Others
By Application
- Lung Cancer
- Renal Cancer
- Blood Cancer
- Bladder Cancer
- Hodgkin Lymphoma
- Melanoma
- Others
By Region
- North America
- Europe
- Asia-Pacific
- Latin America
- The Middle East and Africa