- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$4.56 BnMarket Estimate, 2026
$5.54 BnMarket Forecast, 2034
$22.85 BnCAGR, 2026–2034
19.62%Executive Summary: Global Kombucha Market
- Market Scope: Comprehensive global kombucha market analysis covering functional beverage categories, organic certification frameworks, packaging types, distribution channels, and cold-chain logistics challenges.
- Market Valuation: Valued at USD 4.56 billion (2025), estimated at USD 5.54 billion (2026), and projected to reach USD 22.85 billion by 2034, registering a robust CAGR of 19.62% (2026–2034).
- Primary Growth Drivers: Escalating consumer focus on gut microbiome wellness, rising demand for natural low-sugar beverages, clean-label preferences, functional infusions (turmeric, ginger, CBD), and rapid market penetration in emerging economies.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (2025/2026 Position) | Fastest-Growing Segment |
|---|---|---|
| By Type & Nature | Flavored segment (holds a prominent share by type) alongside organic products (accounting for 56.3% by nature) | Functional variants infused with botanical extracts, adaptogens, and CBD |
| By Packaging & Distribution | Glass bottles (lead packaging) and supermarkets/hypermarkets (dominate distribution with 58.3% share in 2025) | Online retailers (projected as the fastest-growing distribution channel at a CAGR of 22.6%) and aluminum cans (growing at 19.8%) |
| By Region | North America (holds the largest regional share at 41.3% in 2026, followed by Europe at 29.3% in 2025) | Emerging economies in Asia-Pacific and Latin America (driven by expanding health-conscious urban demographics) |
Major Market Players & Market Structure
Market Structure: Highly competitive global functional beverage landscape featuring specialized craft brewers and wellness brands competing on flavor innovation, organic compliance, cold-chain distribution efficiency, and e-commerce accessibility.
Key Companies: Remedy Drinks, GO Kombucha, Vigo Kombucha, BB Kombucha, Equinox Kombucha, GT’s Living Foods, Brew Dr. Kombucha, Health-Ade LLC, Humm Kombucha LLC, Kobenhavn Kombucha, MOMO Kombucha, Brothers and Sisters, Lo Bros, Real Kombucha, and Læsk.
 Download Free Sample Report
Global Kombucha Market Size
The global kombucha market size was valued at USD 4.56 billion in 2025, and the global market size is expected to reach USD 22.85 billion by 2034 from USD 5.45 billion in 2026, growing at a CAGR of 19.62% from 2026 to 2034.
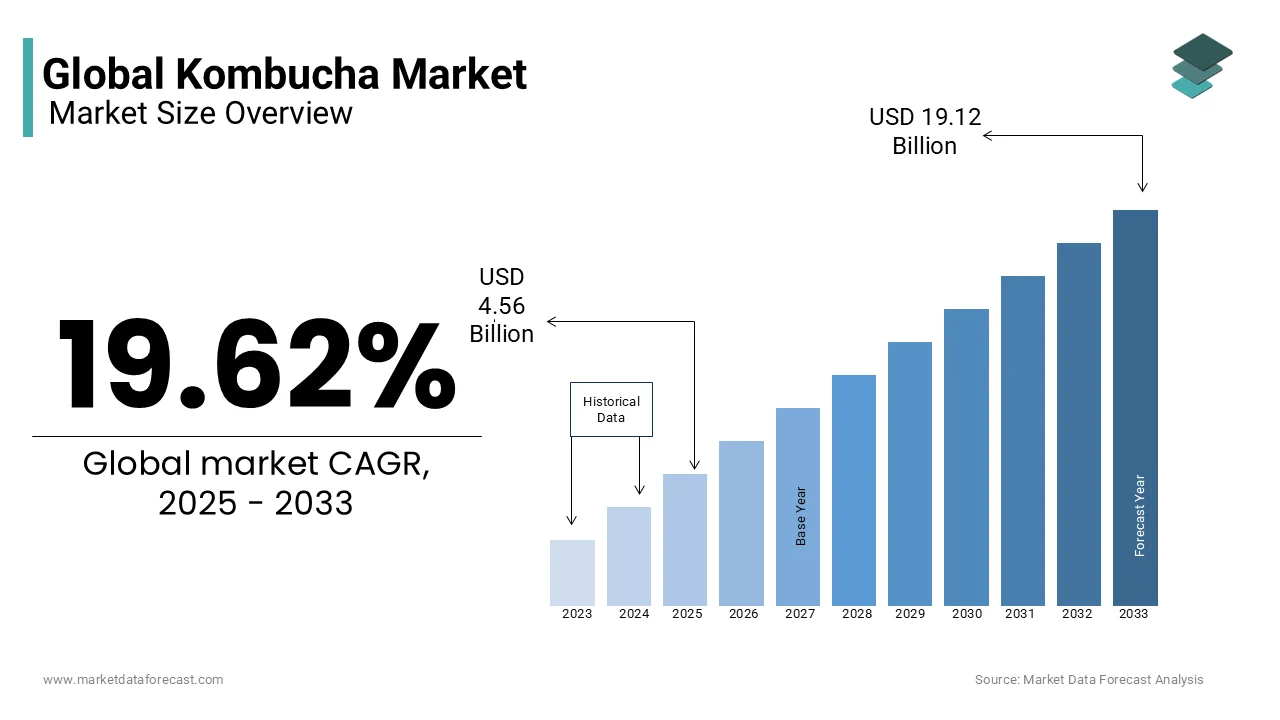
The Kombucha is the global commercial ecosystem centred on kombucha with a fermented tea beverage produced through the symbiotic fermentation of sweetened tea using a SCOBY (Symbiotic Culture of Bacteria and Yeast). The beverage’s origins trace back over two millennia to Northeast China, but its modern resurgence is driven by evolving dietary consciousness and microbiome science. As per the International Scientific Association for Probiotics and Prebiotics, over 70% of the human immune system is influenced by gut microbiota, reinforcing public interest in fermented foods.
MARKET DRIVERS
Growing Consumer Focus on Gut Health and Microbiome Wellness Driving Demand
The escalating scientific and public recognition of gut microbiota’s role in overall health, which is prompting consumers to seek dietary interventions that support digestive balance is escalating the growth of the Kombucha market. Kombucha, as a naturally fermented product containing strains such as Acetobacter, Lactobacillus, and Saccharomyces, offers a non-dairy alternative to yoghurt and kefir, appealing to lactose-intolerant and vegan demographics.
Rising Demand for Natural, Low-Sugar Beverages Amidst Sugar Reduction Initiatives
The global shift toward low-sugar, clean-label beverages is propelled by public health campaigns and regulatory interventions targeting sugar overconsumption, which is accelerating the growth of the Kombucha market. According to the World Health Organization, added sugars constitute less than 10% of total daily caloric intake. As per the Global Burden of Disease Study, over 70% of adults in high-income countries exceed this threshold through sugary drinks. Additionally, its natural fermentation process avoids artificial preservatives and sweeteners, aligning with clean-label expectations.
MARKET RESTRAINTS
High Production Costs and Fragile Supply Chain Limiting Market Scalability
The elevated cost and complexity of production, which hinders scalability and price competitiveness is also to hinder the growth of the Kombucha market. This extended timeline increases operational costs and limits output velocity. Furthermore, the live cultures in kombucha necessitate cold-chain logistics from production to retail, a requirement that escalates distribution expenses. According to the Cold Chain Federation, maintaining refrigerated transport increases beverage logistics costs by 40–60% compared to ambient goods. Small and mid-sized producers, who dominate the market, often lack the capital to invest in automated fermentation monitoring systems, leading to batch inconsistencies.
Limited Consumer Awareness and Misunderstanding of Product Benefits
The persistent lack of consumer understanding regarding kombucha’s composition, health claims, and proper consumption is additionally to hinder the growth of the Kombucha market. As per a 2023 consumer perception survey by the International Food Information Council, only 39% of respondents could correctly identify kombucha as a fermented tea, while 28% mistakenly believed it was a type of carbonated soda or energy drink. Moreover, the beverage’s tart, vinegary taste profile diverges from mainstream sweet beverage preferences, resulting in high initial rejection rates. The absence of standardised health claims further complicates consumer trust; the European Food Safety Authority has rejected all proposed probiotic health claims for kombucha due to insufficient clinical evidence, leaving manufacturers unable to make regulated assertions. In contrast, yoghurt and kefir brands can legally claim digestive benefits in several jurisdictions.
MARKET OPPORTUNITIES
Expansion into Functional and Medicated Beverage Categories
The integration of kombucha into the functional and clinically aligned beverage space, where it can serve as a delivery vehicle for targeted health ingredients is solely to create new opportunities for the growth of the Kombucha market. Kombucha’s acidic pH and microbial activity make it an ideal medium for stabilising and enhancing the bioavailability of these compounds. Brands like Health-Ade and Remedy Organics have already launched variants infused with turmeric, ginger, and CBD, reporting a 35% higher repeat purchase rate compared to plain flavours, according to internal sales analytics.
Growing Adoption in Emerging Markets with Rising Health Consciousness
The penetration of kombucha into emerging economies, where urbanisation, rising disposable incomes, and increasing health awareness are anticipated to gear up the growth of the Kombucha market. In India, the Federation of Indian Chambers of Commerce and Industry reports that organic and functional food sales grew by 52% in 2023 owing to the urban millennials and Gen Z consumers. Local brands such as Bucha and Kompopuli have emerged, using indigenous teas and flavours like tulsi and mango to enhance cultural relevance.
MARKET CHALLENGES
Regulatory Ambiguity Surrounding Health Claims and Product Classification
The lack of harmonised regulatory frameworks governing its classification, labelling, and permitted health claims is degrading the growth of the Kombucha market. In many jurisdictions, kombucha occupies a grey area between food, beverage, and dietary supplement, leading to inconsistent oversight. In the United States, the Alcohol and Tobacco Tax and Trade Bureau regulates kombucha with more than 0.5% alcohol by volume as an alcoholic beverage, a threshold that some brands inadvertently exceed during post-bottling fermentation. As per the U.S. Department of Treasury, over 15 kombucha brands faced regulatory action between 2021 and 2023 for alcohol level violations, resulting in costly recalls and reputational damage. The European Commission’s 2023 Novel Foods Catalogue lists kombucha containing non-traditional microbial strains as subject to pre-market safety assessments, deterring innovation.
Product Stability and Shelf-Life Limitations Due to Live Fermentation
The inherent instability of kombucha due to its live, active fermentation process, which compromises shelf life and logistical reliability is additionally to limit the growth of the Kombucha market. As per research published in the Journal of Food Science, unpasteurised kombucha stored at 25°C for 30 days exhibited a 0.8% increase in alcohol content and a 40% rise in internal bottle pressure, posing safety and quality risks. Furthermore, the beverage’s sensitivity to light and oxygen necessitates dark glass bottles and rapid consumption timelines, increasing packaging costs and limiting distribution reach. A 2023 study by the Institute of Food Technologists found that 18% of kombucha batches failed microbial stability tests after 60 days, even under refrigeration. Some brands have resorted to flash pasteurisation or high-pressure processing (HPP), but these methods can diminish probiotic viability, contradicting core product claims.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 19.62% |
| Segments Covered | By Type, Distribution Channel, Packaging, Nature, And Region. |
| Various Analyses Covered | Global, Regional and Country Level Analysis; Segment-Level Analysis; DROC; PESTLE Analysis; Porter’s Five Forces Analysis; Competitive Landscape; Analyst Overview of Investment Opportunities |
| Regions Covered | North America, Europe, APAC, Latin America, Middle East & Africa |
| Market Leaders Profiled | Remedy Drinks, GO Kombucha, Vigo Kombucha, BB Kombucha, Equinox Kombucha, GT’s Living Foods, Brew Dr. Kombucha, Health-Ade LLC, Humm Kombucha LLC, Kobenhavn Kombucha. |
SEGMENTAL ANALYSIS
By Type Insights
The flavored segment held a prominent share of the Kombucha market in 2025 with the consumer preference for palatable, approachable taste profiles that mitigate the beverage’s naturally tart and vinegary character. Unflavored or natural kombucha, while valued for its purity, often presents a sensory barrier for first-time users. Furthermore, flavor innovation enables differentiation in a crowded marketplace; over 120 new flavored kombucha SKUs were launched globally in 2023 alone, as documented by the Beverage Testing Institute.
The natural segment is swiftly emerging with an expected CAGR of 14.3% in the next coming years with a rising consumer demand for clean-label, minimally processed beverages with transparent ingredient lists. As per the Clean Label Project, 74% of U.S. and European consumers now scrutinize product labels for additives, preservatives, and artificial flavors, with kombucha drinkers particularly sensitive to ingredient integrity. Natural kombucha, defined by its absence of added fruit juices, flavorings, or sweeteners, appeals to purists and health professionals advocating for dietary simplicity. The Rodale Institute’s Regenerative Agriculture Report notes that consumers associating natural kombucha with organic farming and sustainable sourcing are 2.3 times more likely to repurchase.
By Distribution Channel Insights
The supermarkets and hypermarkets segment was the largest and held 58.3% of the Kombucha market share in 2025. Major grocery chains such as Kroger, Tesco, and Woolworths have dedicated “wellness beverage” sections where kombucha is prominently displayed alongside organic juices and plant-based milks, enhancing consumer discovery. According to the Food Marketing Institute, in-store placement within the refrigerated aisle increases kombucha’s purchase likelihood by 37% compared to ambient sections. Furthermore, supermarket private-label programs have entered the space; Tesco launched its own kombucha line in 2023, leveraging economies of scale to offer competitive pricing.
The online retailers segment is expected to grow with an anticipated CAGR of 22.6% in the next coming years with the increasing convenience of home delivery, subscription models, and access to niche or artisanal brands unavailable in physical stores. Platforms like Amazon, Thrive Market, and Farmdrop enable consumers to purchase multi-packs, limited editions, and organic-certified kombucha with subscription options that reduce churn. Additionally, e-commerce allows for detailed product education; brands use digital content to explain fermentation processes, ingredient sourcing, and health benefits, addressing consumer knowledge gaps.
By Packaging Insights
The glass bottles segment was the largest and held a prominent share of the Kombucha market in 2025 with the material’s ability to preserve the beverage’s quality, support branding, and align with sustainability values. As per American Society for Microbiology, kombucha stored in glass retains 92% of its probiotic viability over 60 days, compared to 74% in PET plastic. Additionally, glass bottles offer superior pressure resistance for managing carbonation build-up during secondary fermentation.
The aluminum cans segment is likely to register a CAGR of 19.8% during the forecast period with the portability, compatibility with active lifestyles, and logistical advantages over glass. Cans are lightweight, shatterproof, and require less storage space, making them ideal for on-the-go consumption and outdoor activities. Additionally, cans offer faster chilling and better light blockage than clear glass, preserving microbial stability.
By Nature Insights
The organic segment was accounted in holding 56.3% of the Kombucha market share in 2025 with the intrinsic alignment between kombucha’s artisanal image and organic certification, which assures consumers of pesticide-free tea, non-GMO sugar, and absence of synthetic additives. According to a 2023 consumer survey by the Hartman Group, 69% of organic kombucha buyers perceive it as “safer” and “more effective” than conventional versions. In the European Union, where organic food sales reached €55 billion in 2023 as per Eurostat, kombucha brands with EU Organic certification experience 2.1 times faster shelf placement.
The conventional, or non-organic segment is projected to grow at a CAGR of 16.2% during the forecast period with the affordability, scalability, and expanding access in price-sensitive and emerging markets where organic certification remains a barrier. Additionally, large beverage corporations entering the space such as Coca-Cola with Honest Kombucha that prioritize conventional production to leverage existing supply chains and achieve economies of scale.
REGIONAL ANALYSIS
North America Kombucha Market Analysis
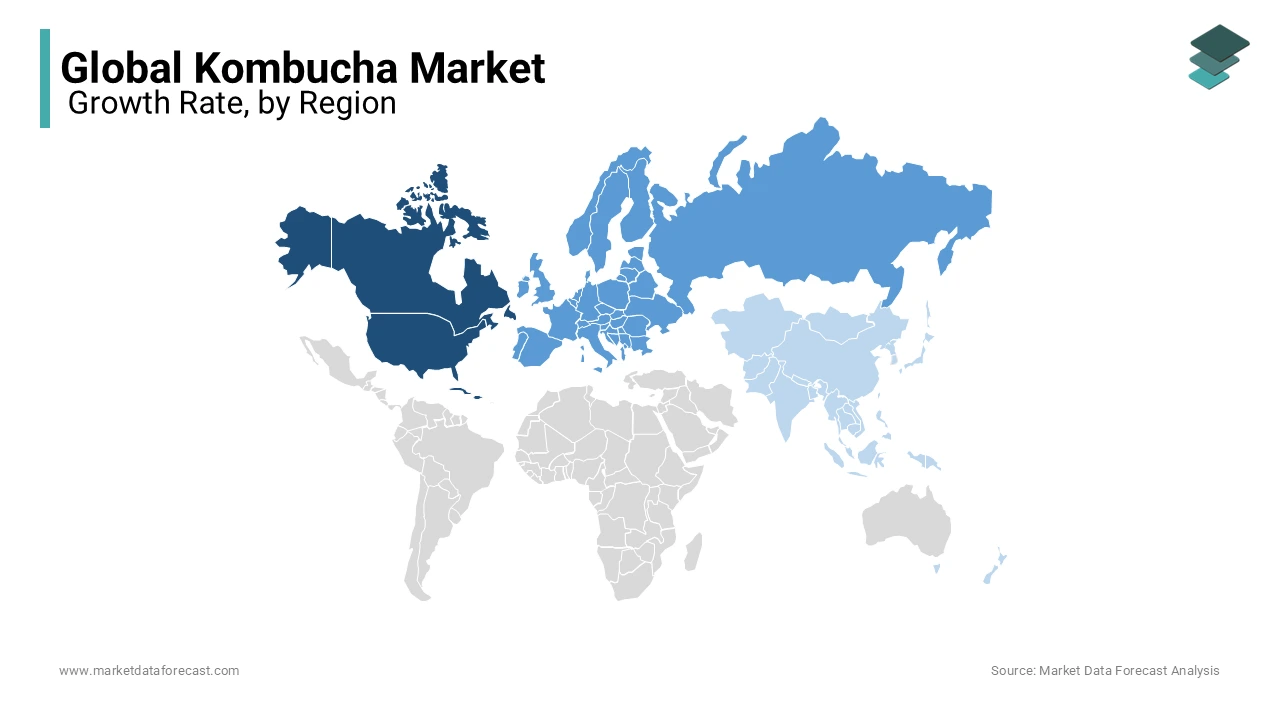
North America was the top performer of the global kombucha market with 41.3% of share in 2026 with the most mature and innovation-driven region. Additionally, the Alcohol and Tobacco Tax and Trade Bureau’s regulatory clarity on alcohol thresholds has enabled consistent product formulation and labelling. The presence of robust cold-chain infrastructure and high disposable incomes further supports premiumisation. According to the National Grocers Association, kombucha commands a 12% shelf space share in refrigerated beverage sections, surpassing many traditional juice brands.
Europe Kombucha Market Analysis
Europe was ranked second with 29.3% of the Kombucha market share in 2025. Germany, the UK, and France are the primary markets, with Germany leading in per capita consumption due to its strong tradition of fermented foods like sauerkraut and kefir. As per the European Federation of Food Science and Technology, 54% of German consumers associate fermentation with digestive health, creating a receptive environment for kombucha. Regulatory frameworks vary with the EU classifies kombucha as a novel food if non-traditional strains are used, countries like Italy and Spain allow broader interpretation.
Asia Pacific Kombucha Market Analysis
Asia Pacific kombucha market growth is likely to be driven by the most dynamic and high-potential region for future growth. Japan and South Korea lead in adoption, where traditional fermented foods like miso, kimchi, and green tea have cultivated consumer familiarity with probiotic benefits. As per Japan’s Ministry of Health, Labour and Welfare, over 40% of adults regularly consume fermented beverages, creating a natural entry point for kombucha. According to the International Finance Corporation, cold-chain infrastructure in major Chinese cities has improved by 45% since 2020, enabling safer distribution.
Latin America Kombucha Market Analysis
Latin America kombucha market growth is likely to be driven with Brazil and Mexico emerging as key growth markets amid rising health awareness and urbanisation. Chile and Colombia are also witnessing growth, supported by wellness-focused retail chains like Santa Isabel and Éxito. However, distribution remains constrained by inconsistent refrigeration; the Inter-American Development Bank estimates that 30% of perishable goods in rural areas suffer spoilage due to cold-chain gaps.
Middle East and Africa Kombucha Market Analysis
The Middle East and Africa kombucha market growth is likely to grow steadily in the coming years. In the UAE, Dubai’s “Smart City” health programs include kombucha in corporate wellness kits, with over 150,000 units distributed in 2023, as reported by the Dubai Health Authority. South Africa leads in Sub-Saharan Africa, where kombucha is available in major retailers like Woolworths and Pick n Pay, with sales growing by 24% in 2023, according to Statista Africa.
COMPETITIVE LANDSCAPE
KEY MARKET PLAYERS
Some of the notable key players in the global kombucha market are
-
København Kombucha
-
MOMO Kombucha
-
Brothers and Sisters
-
GO Kombucha
-
Lo Bros
-
Equinox Kombucha
-
GT’s Living Food
-
BB Kombucha
-
Remedy Drinks
-
Real Kombucha
-
Læsk
-
VIGO Kombucha
TOP STRATEGIES USED BY THE KEY MARKET PLAYERS
Key players in the Kombucha Market are deploying premium branding, regional flavour innovation, e-commerce expansion, strategic retail partnerships, and scientific validation to strengthen their market positions. Companies are investing in clean-label messaging and organic certifications to build consumer trust. Flavour customisation for local palates enhances cultural relevance in diverse markets. Expansion into online retail and subscription models improves accessibility and retention. Collaborations with health professionals and digital education campaigns increase credibility. Sustainable packaging and cold-chain optimisation address logistical challenges. Additionally, entry into foodservice and convenience channels broadens consumption occasions. These strategies collectively drive brand loyalty and scalability in a competitive, quality-sensitive market.
COMPETITON OVERVIEW
The competition in the Kombucha Market is intensifying as artisanal producers, multinational beverage companies, and regional startups converge on the functional beverage space. Differentiation increasingly hinges on authenticity, ingredient transparency, and microbial integrity rather than branding alone. Market leaders are investing in fermentation science, third-party testing, and traceable sourcing to establish credibility. Premium brands emphasize small-batch production and organic certification, while large corporations leverage distribution scale and R&D capabilities. The rise of private-label kombucha in supermarkets has intensified price competition, particularly in Europe and North America. In emerging markets, local players are gaining ground by offering culturally adapted flavours and affordable pricing. Sustainability is a growing differentiator, with reusable packaging and carbon-neutral production influencing brand perception.
TOP PLAYERS IN THE MARKET
- GT’s Living Foods has significantly influenced the Asia Pacific kombucha landscape by introducing authentic, raw fermentation practices to a region traditionally unfamiliar with the beverage. The brand has expanded its distribution through premium health retailers and e-commerce platforms in Australia, Japan, and Singapore, positioning kombucha as a functional wellness drink. In 2023, GT’s partnered with Woolworths in Australia to launch a dedicated kombucha aisle, increasing visibility and consumer education. The company also initiated localized digital campaigns featuring gut health experts to build credibility.
- Health-Ade has strengthened its presence in the Asia Pacific market by leveraging premium branding and innovative product formats tailored to regional preferences. The company entered Japan and South Korea through selective partnerships with high-end supermarkets and wellness boutiques, emphasizing its small-batch, cold-pressed production process. In 2023, Health-Ade launched canned kombucha variants in 250ml sizes, optimized for portability and convenience in densely populated urban centres like Tokyo and Seoul. It also introduced limited-edition flavours using yuzu and ginger to align with local taste profiles.
- Remedy Organics, an Australian-born brand, has played a foundational role in shaping the kombucha market across Asia Pacific by championing sugar-free, raw, and organic formulations. The company has expanded beyond Australia into New Zealand, China, and Southeast Asia through major retail chains like Cold Storage and Guardian, as well as e-commerce platforms such as Tmall Global. In 2023, Remedy launched a “Live Culture Guarantee” campaign, assuring consumers of probiotic viability through batch testing, reinforcing product integrity. It also introduced recyclable glass packaging with QR codes linking to fermentation transparency reports. The brand collaborated with nutritionists in Hong Kong and Shanghai to conduct gut health webinars, building clinical credibility.
RECENT HAPPENINGS IN THE MARKET
- In January 2023, GT’s Living Foods partnered with Woolworths Australia to launch dedicated kombucha retail zones by enhancing visibility and consumer access in over 200 stores nationwide.
- In March 2023, Health-Ade introduced canned kombucha in Japan and South Korea with region-specific flavours like yuzu-ginger, which is optimising for portability and local taste preferences.
- In June 2023, Remedy Organics launched its Live Culture Guarantee campaign by providing batch-specific probiotic testing data via QR codes on packaging to reinforce product authenticity.
- In September 2023, The Laughing Buddha, a UK-based kombucha brand, entered the Indian market through BigBasket and Nature’s Basket by leveraging online and premium retail channels for rapid distribution.
- In February 2025, Kevita, a PepsiCo-owned brand, expanded its probiotic kombucha line into select Middle Eastern markets via agreements with BinDawood Holding in Saudi Arabia by targeting health-conscious urban consumers.
MARKET SEGMENTATION
This research report on the global Kombucha Market has been segmented and sub-segmented based on Type, Distribution Channel, Packaging, Nature, & region.
By Type
- Natural
- Flavored
By Distribution Channel
- Supermarkets/Hypermarkets
- Convenience Stores
- Online Retailers
By Packaging
- Bottles
- Cans
By Nature
- Organic
- Inorganic
By Region
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East and Africa