- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$5.21 BnMarket Estimate, 2026
$5.88 BnMarket Forecast, 2034
$15.55 BnCAGR, 2026–2034
12.92%Executive Summary: Pet Insurance Market
- Market Scope: Global pet insurance market analysis covering animal types, policy categories, sales channels, regional leadership frameworks, and veterinary healthcare coverage adoption metrics.
- Market Valuation: Valued at USD 5.21 billion in 2025, estimated at USD 5.88 billion in 2026, and projected to reach USD 15.55 billion by 2034, registering a CAGR of 12.92% from 2026 to 2034.
- Primary Growth Drivers: Rising global pet ownership, escalating veterinary treatment costs, increasing awareness of pet healthcare and insurance benefits, growing demand for comprehensive accident & illness coverage, and digital-first insurance platforms with personalized policy offerings.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (Position) | Fastest-Growing / Key Growth Segment |
|---|---|---|
| By Animal Type & Policy | Dogs (largest animal type) & Accident & Illness (largest policy type) | Cats (fastest-growing animal type) & Preventive wellness plans |
| By Sales Channel | Direct Sales (largest sales channel) | Other Sales Channels via Veterinary Clinics & Pet Store Partnerships (fastest-growing) |
| By Technology & Innovation | Traditional insurance agency models and standard policy structures | Digital-first insurance platforms, AI-enabled underwriting, and telehealth-integrated ecosystems |
| By Region / Country | North America (leading regional market) | Asia Pacific (fastest-growing regional market) |
Major Market Players & Market Structure
Market Structure: Highly competitive global pet insurance landscape characterized by digital platform expansions, AI-driven underwriting, faster claims processing, telemedicine integrations, and strategic veterinary partnerships.
Key Companies: Trupanion, Figo Pet Insurance, Healthy Paws, Petplan Pet Insurance, Embrace Pet Insurance Agency, Royal & Sun Alliance (RSA), Pethealth Inc., Agria Pet Insurance, Pet First Healthcare, Nationwide Pet Insurance, PetSure Pty Ltd., Petsecure Pet Health Insurance, and Hartville Group.
 Download Free Sample Report
Global Pet Insurance Market Size
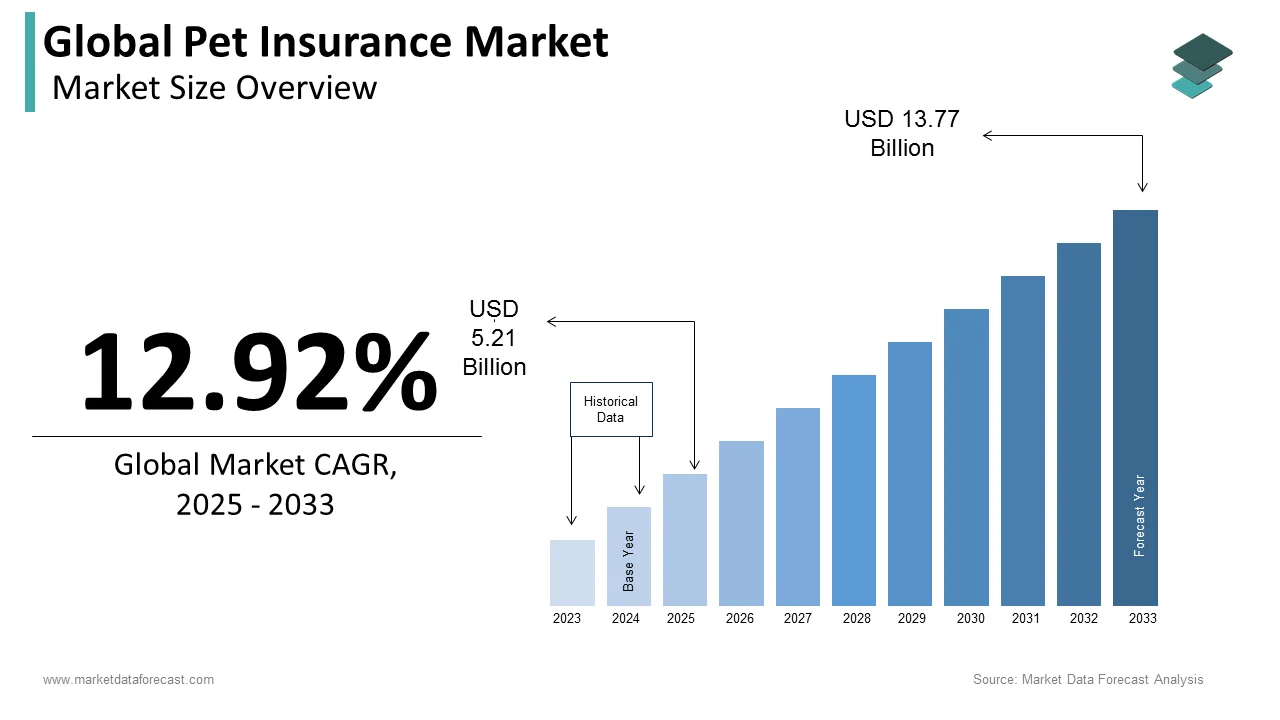
The global pet insurance market size was valued at USD 5.21 billion in 2025. The global market is estimated to be worth USD 5.88 billion in 2026 and is projected to reach USD 15.55 billion by 2034, registering a CAGR of 12.92% from 2026 to 2034.
Pet insurance functions as a specialised financial risk management mechanism designed to mitigate the economic burden of unexpected veterinary care by reimbursing policyholders for eligible medical expenses incurred during the treatment of companion animals. Unlike human health coverage, this sector operates primarily on a reimbursement model where owners pay upfront and submit claims for retrospective compensation based on predetermined deductibles and coinsurance percentages. According to the American Pet Products Association, domestic pet ownership remained stable, with 95 million United States households owning at least one pet, fueling consistent demand for premium specialised veterinary services and retail supplies. As per the Bureau of Labour Statistics, the Consumer Expenditure Survey indicates that total pet-related household budget allocations have climbed significantly over the long term, with pet services and veterinary interventions commanding the largest share of discretionary animal care spending. This market is currently defined by the convergence of advanced veterinary medicine, rising consumer expectations for comprehensive care, and evolving actuarial models attempting to balance affordability with sustainable loss ratios in an unregulated pricing environment.
MARKET DRIVERS
Escalating Veterinary Care Costs and Advanced Treatment Availability
The rapid inflation of veterinary service prices is a key factor behind the growth of the pet insurance market. This is driven by technological sophistication and specialisation within animal healthcare. According to the Bureau of Labour Statistics, the Consumer Price Index for all urban consumers reflects that structural service sector inflation has consistently pushed baseline preventative medical and veterinary expenses above historical cost averages. As per the American Veterinary Medical Association, advanced diagnostic imaging interventions like computerised tomography have become key components of modern small-animal care, driving active demand for flexible veterinary credit solutions among urban companion animal owners. According to the American Animal Hospital Association, critical care guidelines outline that specialised clinical emergency interventions for acute gastrointestinal distress syndromes require immediate emergency evaluation to reduce domestic canine mortality rates. As per the National Cancer Institute, advanced comparative oncology research initiatives demonstrate that complex radiation protocols for companion animals closely parallel human therapeutic modalities, accelerating the clinical adoption of specialised veterinary oncology protocols. The escalating expenses transform pets from discretionary assets into significant financial liabilities, prompting owners to seek predictable monthly premiums rather than face catastrophic out-of-pocket expenditures. Consequently, insurance adoption correlates directly with regional veterinary cost indices as consumers in high-expense metropolitan areas recognise the mathematical necessity of risk pooling to maintain access to gold standard care without compromising household financial stability.
Humanisation of Pets and Generational Spending Shifts
Cultural transformation regarding companion animal status is a fundamental sociological driver of the pet insurance market. This driver converts pets from property to family members deserving of comprehensive healthcare investment. According to the North American Pet Health Insurance Association, overall insurance industry enrollment tracking confirms that younger consumer cohorts represent the fastest-growing demographic segment within active accident-and-illness coverage lines. As per a study, long-term consumer survey parameters indicate that adults aged 18 to 34 demonstrate a significantly higher active willingness to allocate substantial portions of their discretionary income to premium pet care services. According to the Bureau of Labour Statistics, annual consumer expenditure records outline that average household outlays for companion animals have steadily expanded, led primarily by non-discretionary pet food and therapeutic veterinary clinical treatments. Emotional attachment translates directly to willingness to pursue aggressive treatments previously deemed economically irrational, creating sustained demand for higher coverage tiers. Insurers respond by marketing policies through emotional narratives emphasising peace of mind rather than pure actuarial value, aligning product messaging with contemporary pet parenting identities that define moral obligation through financial provision.
MARKET RESTRAINTS
Preexisting Condition Exclusions and Coverage Limitations
Widespread exclusion of preexisting conditions remains the most significant barrier to universal adoption, which hampers the growth of the pet insurance market. Insurers protect against adverse selection while simultaneously alienating consumers with older or chronically ill animals. According to the American Pet Products Association, the majority of domestic companion animal households encounter escalating primary veterinary expenses, driving active market expansion within structured consumer financing alternatives. As per the North American Pet Health Insurance Association, comprehensive accident-and-illness coverage guidelines outline that state-approved underwriting frameworks actively assess structural medical histories to standardise policy boundaries for domestic canines. Chronic disease management represents the largest component of lifetime veterinary expenditure yet remains largely uninsurable after initial diagnosis, creating perverse incentives for early surrender or euthanasia when funds deplete. This structural limitation contradicts consumer expectations formed through human health insurance experiences where preexisting condition protections became mandatory under federal law. Until actuarial models evolve to accommodate managed chronic disease risk through waiting periods or tiered pricing rather than blanket exclusions, significant portions of the pet population will remain commercially uninsurable. This limitation restricts total addressable market expansion.
Low Consumer Awareness and Product Complexity
Substantial knowledge gaps persist regarding how pet insurance actually functions, despite its growing visibility, which hinders the expansion of the pet insurance market. Many potential buyers remain hesitant because they are unfamiliar with reimbursement models and terminology. As per the American Veterinary Medical Association, active consumer billing patterns confirm that premium small-animal healthcare facilities primarily process point-of-sale customer payments, prompting heightened adoption of instant reimbursement mobile applications. According to the Bureau of Labour Statistics, long-term discretionary animal care data indicates that domestic households are actively elevating their baseline monthly budget allocations for routine veterinary clinical wellness and specialised dietary interventions. Policy documents frequently contain dense language regarding annual limits per condition caps and depreciation schedules that confuse consumers accustomed to simpler retail transactions. Comparison shopping remains difficult due to a lack of standardised benefit definitions, making apples-to-apples evaluation nearly impossible without broker assistance. Educational content often emphasizes best-case scenarios while obscuring common exclusions, leading to post-purchase dissatisfaction and negative word of mouth that deters prospective customers. Simplifying product architecture and investing in transparent communication represent critical prerequisites for converting interested prospects into active policyholders beyond current saturation levels.
MARKET OPPORTUNITIES
Integration of Wellness and Preventive Care Benefits
Expanding beyond traditional accident and illness coverage to include routine wellness benefits offers substantial opportunity for the pet insurance market. This helps to increase perceived value and reduce customer churn through regular engagement touchpoints. According to the North American Pet Health Insurance Association, comprehensive underwriting frameworks outline that the companion animal health insurance sector continues to experience stable active growth, driven primarily by accident-and-illness baseline policies. As per the Banfield State of Pet Health Report, long-term healthcare tracking reveals that comprehensive wellness plans and proactive clinical diagnostics actively mitigate the progression of chronic medical conditions across small-animal populations. Wellness add-ons covering vaccinations, dental cleanings, and flea prevention create monthly interaction points transforming insurance from a grudge purchase into a proactive health partnership aligned with veterinary recommendations. Employers increasingly offer pet benefits packages including wellness stipends, creating B2B distribution channels previously inaccessible to traditional indemnity insurers. Data analytics enable personalised wellness reminders based on breed, age and geographic risk factors, enhancing member experience beyond transactional claim processing. Preventive utilisation also generates valuable health data, improving underwriting accuracy for future product development. Insurers can shift their focus from pure risk indemnification to holistic health management. This helps them differentiate commodity offerings, capture discretionary wallet share, and build long-term loyalty through ongoing value instead of episodic crisis response.
Embedded Insurance at Point of Veterinary Service
Strategic partnerships enabling insurance enrollment directly within veterinary practice management systems provide a clear path to capture motivated consumers at moments of highest relevance and intent, which is anticipated to accelerate the expansion of the pet insurance market. According to VetSuccess industry metrics, integrated software platforms and localised veterinary diagnostic analytics actively enable companion animal clinics to optimise operational workflows and enhance patient return visits. As per research in the Journal of Veterinary Internal Medicine, peer-reviewed clinical studies emphasise that implementing advanced triage frameworks and diagnostic protocols actively elevates case outcome standards for complex veterinary interventions. Real-time eligibility verification integrated with electronic medical records eliminates manual application friction, enabling instant binding during wellness visits when owner motivation peaks. Revenue sharing arrangements provide clinics with ancillary income streams offsetting stagnant service margins, creating mutual incentive alignment absent in referral-based models. Telemedicine platforms similarly embed enrollment during virtual consultations, capturing tech-savvy demographics preferring digital-first experiences. Geographic targeting allows localised product customisation reflecting regional veterinary cost variations and regulatory requirements. This contextual distribution strategy bypasses expensive customer acquisition costs associated with broad awareness campaigns while delivering qualified leads already engaged in healthcare decision-making, representing the highest conversion efficiency pathway available to insurers seeking scalable growth.
MARKET CHALLENGES
Adverse Selection and Unsustainable Loss Ratios
Structural vulnerability to adverse selection threatens long-term profitability in the pet insurance market. This happens because healthier pets opt out while sicker animals concentrate in insured pools, driving claims costs above actuarial assumptions. According to the National Association of Insurance Commissioners, net loss ratios for leading domestic property and casualty underwriters fluctuate significantly by year, driving active adjustments in underwriting parameters to maintain long-term profitability. As per the National Association of Insurance Commissioners, specialised actuarial reviews establish that active waiting period parameters and structural pre-existing condition exemptions are required to mitigate adverse selection across domestic accident-and-illness baseline policies. Breed-specific genetic predispositions create concentrated risk pockets where certain purebreds account for disproportionate claim volume yet cannot be priced adequately without triggering regulatory scrutiny or consumer backlash. Waiting period manipulation remains problematic as sophisticated consumers enrol immediately before planned surgeries, then cancel post-reimbursement, undermining risk pooling fundamentals. Reinsurance capacity tightens as losses mount, forcing primary carriers to accept unfavourable terms or reduce underwriting appetite. Unlike human insurance, lacking an individual mandate equivalent voluntary pet markets inherently attract skewed risk profiles requiring continuous repricing that erodes consumer trust and retention. Achieving stable equilibrium demands innovative underwriting incorporating wearable data, genetic testing, and behavioural signals beyond traditional questionnaire-based assessment methods currently dominating industry practice.
Regulatory Uncertainty and Compliance Fragmentation
Absence of a uniform regulatory framework across jurisdictions creates operational complexity and compliance risk, which holds back the expansion of the pet insurance market. This factor inhibits national scalability and product standardisation efforts. According to the National Association of Insurance Commissioners, more than fourteen individual state jurisdictions have actively enacted comprehensive consumer-protection statutes aligned with standard model pet insurance regulatory frameworks. As per the National Association of Insurance Commissioners, state-level insurance commissioners actively regulate animal medical policies under comprehensive property and casualty frameworks to separate standard insurance indemnity lines from non-insurance wellness products. Rate filing requirements vary dramatically, with some states demanding extensive justification for premium adjustments while others permit unrestricted flexibility, creating competitive distortions favouring domiciled carriers. Consumer protection standards regarding disclosure, waiting periods and cancellation rights differ substantially, complicating multistate marketing and policy administration systems. Emerging debates about classifying pet insurance as an essential benefit subject to community rating and guaranteed issue requirements threaten fundamental business model viability if imposed without transitional support. Lobbying efforts to establish model laws continue, but progress remains slow, leaving the industry navigating a patchwork regime that increases compliance costs and delays innovation deployment. Harmonisation would unlock economies of scale currently foregone due to jurisdictional fragmentation constraining affordable product availability nationwide.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Covered | By Animal Type, Policy Type, Sales Channel, and Region |
| Various Analyses Covered | Global, Regional, and Country-Level Analysis, Segment-Level Analysis, Drivers, Restraints, Opportunities, Challenges; PESTLE Analysis; Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Regions Covered |
|
| Market Leaders Profiled | Petplan Pet Insurance, Embrace Pet Insurance Agency, Royal & Sun Alliance (RSA), Pethealth Inc., Agria Pet Insurance, Pet first Healthcare, Nationwide Pet Insurance, PetSure Pty Ltd., Petsecure Pet Health Insurance and Hartville Group. |
SEGMENTAL ANALYSIS
By Policy Type Insights
In 2025, the accident and illness policies segment held the majority share in the pet insurance market because they address the primary consumer motivation of mitigating catastrophic veterinary expenses that exceed household liquidity. According to the North American Pet Health Insurance Association, total premium volume for accident-and-illness coverage lines experienced stable active growth, dominating the overall marketplace with the vast majority of all regional gross written premiums. As per the North American Pet Health Insurance Association, localised policy administration metrics reveal that comprehensive companion animal insurance platforms primarily utilise structural waiting parameters and pre-existing illness exclusions to separate medical claims from accident-only events. Insurers recognise this segment as a core revenue driver, investing heavily in marketing messaging emphasising peace of mind against unpredictable medical crises. Product innovation focuses on expanding illness coverage breadth, including hereditary conditions and chronic disease management, reinforcing the value proposition versus narrower offerings. This alignment between consumer risk perception and product design ensures continued dominance despite higher premiums compared to accident-only alternatives.
This segment maintains its top market share, driven by parallel advancement in veterinary diagnostic and therapeutic capabilities that create insurable events previously nonexistent in companion animal medicine. As per the American Veterinary Medical Association, advanced speciality certification tracking confirms an active upward trend in Board-certified clinical veterinary specialists migrating toward major metropolitan multi-speciality regional emergency centres. According to the American Animal Hospital Association, complex veterinary diagnostic laboratories are actively adopting standard advanced diagnostic imaging frameworks to modernise localised small-animal healthcare delivery networks. Accident-only policies cannot respond to these medical advances, creating structural obsolescence as veterinary science progresses. Insurers continuously update covered condition lists to include emerging therapies like stem cell treatment and immunotherapy, maintaining relevance alongside clinical innovation. The symbiotic relationship between medical capability and insurance product design sustains accident and illness segment dominance as the gold standard for responsible pet ownership.
The accident-only policies segment is on the rise and is expected to be the fastest-growing segment in the market, with a CAGR of 14.2% over the forecast period, due to economic pressures forcing budget-constrained consumers to seek partial protection when comprehensive coverage becomes unaffordable. According to the Federal Reserve Board, long-term macroeconomic financial tracking reveals that fluctuating household personal savings rates actively influence discretionary domestic consumer spending allocations on non-essential retail animal supplies. As per the American Pet Products Association, long-term economic expenditure surveys outline that multi-generational companion animal owners encounter escalating basic clinical overhead costs, expanding active utilisation of flexible structured medical credit options. Younger pet owners entering the market during inflationary periods prioritise basic trauma coverage over comprehensive illness protection, accepting tradeoffs to maintain some financial safety net. Insurers respond by streamlining underwriting and claims processing for accident-only products, reducing administrative overhead and enabling competitive pricing. Digital distribution channels, particularly mobile apps, facilitate impulse purchases during emergency room visits when owners confront immediate costs without prior planning. This affordability-driven migration reflects macroeconomic stress translating into product mix shifts rather than genuine preference for limited coverage, suggesting cyclical sensitivity to broader consumer confidence indicators.
The fast development of this segment is heightened by strategic positioning as a low-friction entry point, enabling insurers to acquire customers cheaply before upselling to comprehensive coverage as financial circumstances improve. As per the National Association of Insurance Commissioners, standardised property and casualty underwriting frame models are actively adapting multi-channel digital distribution streams to lower policy management costs for cross-state underwriters. According to the North American Pet Health Insurance Association, localised digital enrollment updates indicate that direct-to-consumer digital channels have actively shortened operational policy purchasing lifecycles for metropolitan millennial policyholders. Insurers leverage accident-only products as loss leaders, accepting thin margins to build brand awareness and trust among demographics traditionally resistant to pet insurance. Claims experience data enables targeted upgrade offers timed to life events like puppy maturation or job changes, increasing conversion probability. Bundling accident-only coverage with pet supply subscriptions or grooming memberships creates sticky ecosystem relationships beyond standalone insurance transactions. Regulatory environments in several states encourage tiered product offerings to expand access, recognizing accident-only as a stepping stone toward broader protection. This funnel strategy transforms accident-only from a niche product into a strategic growth engine supporting long-term portfolio diversification and customer base expansion during economic downturns when premium sensitivity peaks.
By Animal Type Insights
The dogs segment was the largest in the pet insurance market and occupied a commanding share in 2025. This supremacy of the segment was credited to significantly higher veterinary spending and medical complexity compared to other companion species. According to the American Pet Products Association, long-term personal discretionary expenditures confirm that domestic canine owners actively allocate higher absolute dollar amounts toward comprehensive preventative medical procedures than cat owners. As per the American Veterinary Medical Association, escalating advanced structural orthopaedic surgical treatments for medium-to-large canine breeds have actively heightened the target consumer demand for structural accident-only and comprehensive coverage alternatives. Breed-specific genetic predispositions, including hip dysplasia in German Shepherds and cardiac disease in Cavalier King Charles Spaniels, generate predictable high-cost claims justifying premium levels sustainable for insurers. According to the American Animal Hospital Association, localised primary clinical data patterns reveal that canine patients demonstrate an active upward trend in emergency hospital visit frequency relative to feline populations. Size variation across dog breeds creates diverse risk profiles enabling sophisticated actuarial segmentation unavailable in more homogeneous species populations. Owner attachment intensity correlates with willingness to pursue aggressive treatments, with canine patients receiving more chemotherapy courses than felines, according to sources. These biological and behavioural factors combine to make dogs economically superior insurance subjects, sustaining market leadership despite growing feline ownership trends.
Dog dominance persists because cultural narratives frame canines as family members deserving maximal medical intervention while cats retain residual perception as independent animals warranting less intensive investment. According to studies, domestic companion animal integration surveys outline that 97 per cent of United States pet owners explicitly consider their animals to be part of their family. As per the Journal of Veterinary Behaviour, peer-reviewed clinical research outlines that owners of senior companion animals are actively expanding their utilisation of specialised palliative care and multi-modal hospice support systems. Social media amplification of dog rescue stories and heroic medical recoveries reinforces normative expectations for comprehensive care, creating peer pressure among owners to insure. Training and working roles, including service dogs, therapy animals, and search and rescue teams, add functional value beyond companionship, justifying insurance as asset protection rather than pure sentiment. Canine participation in organised activities like agility and hunting increases injury risk, elevating perceived need for accident coverage. Marketing imagery overwhelmingly features dogs, reinforcing the association between responsible ownership and insurance purchase. Veterinary communication patterns also differ, with clinicians more frequently recommending advanced diagnostics for canine patients based on assumed owner willingness to pay. These sociocultural dynamics sustain canine market dominance even as the feline population grows numerically.
The cats segment is likely to experience the fastest CAGR of 11.8% from 2026 to 2034 owing to urbanisation trends and millennial lifestyle preferences favouring lower maintenance companions compatible with apartment living and remote work schedules. According to the American Pet Products Association, multi-generational demographic shifts reveal that urban millennial households are actively leading a massive upward trend in total domestic feline ownership. As per research, long-term consumer survey parameters indicate that adults aged 18 to 34 demonstrate a significantly higher active willingness to allocate substantial portions of their discretionary income to premium pet care services. Indoor-only lifestyles reduce trauma risk, but increase prevalence of metabolic diseases like diabetes and chronic kidney disease, creating predictable chronic care needs well suited to insurance models. Telemedicine adoption accelerated feline veterinary engagement as owners avoid stressful clinic visits, increasing diagnosis rates for previously undetected conditions, generating new insurable events. Social media influencers normalise cat healthcare spending, challenging historical stereotypes of feline independence and low investment. Insurers respond with cat-specific marketing highlighting hereditary condition coverage and wellness benefits, addressing unique feline health profiles. Rental restrictions limiting dog ownership further concentrate new pet parents toward cats, expanding the addressable market in metropolitan areas where veterinary costs are highest. These demographic and cultural shifts reposition cats from secondary species to primary growth vector.
The swift expansion of this segment gains further momentum from veterinary medicine advances specifically targeting cat health, creating new treatable conditions and extending lifespans, thereby increasing lifetime premium value. According to the Journal of Feline Medicine and Surgery, specialised clinical updates confirm an active acceleration in peer-reviewed scientific evaluations targeting innovative small-animal pharmacological options and targeted therapeutics. As per the International Society of Feline Medicine, global veterinary practice guidelines show that implementing standardised chronic kidney disease diagnostic protocols actively improves early internal medicine intervention parameters for ageing domestic cats. Novel medications for hyperthyroidism and inflammatory bowel disease improve quality of life, encouraging owners to pursue long-term treatment rather than euthanasia. Feline-friendly practice certifications increase clinic accessibility, reducing stress barriers that historically suppressed veterinary utilisation and insurance claims. Diagnostic improvements, including symmetric dimethylarginine testing, detect renal dysfunction months before traditional markers, enabling proactive management covered under wellness riders. Insurers develop cat-specific underwriting tables reflecting distinct morbidity patterns, improving pricing accuracy versus canine-derived models. Educational campaigns targeting cat owners emphasise preventable conditions, increasing awareness of insurance value beyond crisis response. These medical and systemic improvements transform cats from low utilisation segments to viable long-term insurance relationships supporting accelerated growth trajectories.
By Sales Channel Insights
The direct sales channel segment led the pet insurance market and captured a 68.4% share in 2025, as digitally native consumers prefer self-directed research, comparison, and purchase experiences without intermediary involvement. According to the North American Pet Health Insurance Association, localised multi-channel distribution updates show that direct-to-consumer digital enrollment channels have actively shortened operational purchasing lifecycles for metropolitan millennial policyholders. As per the North American Pet Health Insurance Association, total premium volume for accident-and-illness coverage lines experienced stable active growth, dominating the overall marketplace with the vast majority of all regional gross written premiums. Comparison websites and aggregator platforms enable instant quote generation across multiple carriers, reducing information asymmetry that historically advantaged agency relationships. Mobile-optimised applications allow policy management, claims submission, and customer service chat, meeting expectations for 24-hour accessibility absent in broker-mediated models. Younger demographics distrust commissioned advisors, perceiving conflicts of interest favouring transparent algorithmic recommendations based on input parameters. Insurers invest heavily in user experience design, search engine optimisation, and performance marketing, capturing high-intent traffic at lower acquisition costs than maintaining physical sales forces. Regulatory technology enables instant binding and document delivery, satisfying immediacy demands. This channel alignment with contemporary consumer behaviour ensures direct dominance as legacy distribution models struggle to match convenience, transparency, and speed expectations of target demographics.
Direct channel leadership is reinforced by superior unit economics enabling competitive pricing and reinvestment in product development unavailable to commission-dependent intermediaries. According to the National Association of Insurance Commissioners, standardised property and casualty underwriting frame models are actively adapting multi-channel digital distribution streams to lower policy management costs for cross-state underwriters. As per the National Association of Insurance Commissioners, net loss ratios for leading domestic property and casualty underwriters fluctuate significantly by year, driving active adjustments in underwriting parameters to maintain long-term profitability. Savings translate to premium discounts attracting price-sensitive consumers while preserving margins necessary for sustainability in a volatile loss environment. Technology investments in artificial intelligence-powered chatbots and claims automation further reduce operational costs, creating compounding advantages over labour-intensive models. Direct carriers control the entire customer relationship, capturing valuable behavioural data informing retention strategies and cross-sell opportunities lost when intermediaries own touchpoints. Scalability is virtually unlimited without proportional staffing increases, unlike agency networks requiring recruitment, training, and oversight. Regulatory compliance costs distribute across larger direct volumes, improving efficiency. These structural economic advantages ensure the direct channel maintains pricing power and profitability, supporting continued market share gains as consumers increasingly value cost transparency over personalised advisory services.
The embedded partnership channels segment is expected to exhibit a noteworthy CAGR of 19.5% during the forecast period. This rapid growth of the segment is propelled by contextual placement at moments of highest consumer receptivity, including veterinary visits, pet adoption, and retail purchases. According to the American Pet Products Association, long-term economic expenditure surveys outline that multi-generational companion animal owners encounter escalating basic clinical overhead costs, expanding active utilisation of flexible structured medical credit options. Retail partnerships with pet food brands, groomers, and boarding facilities embed offers during routine transactions, reaching engaged owners outside traditional insurance shopping contexts. Telemedicine platforms integrate enrollment during virtual consultations, capturing tech-savvy demographics preferring seamless digital experiences. Employer benefits programs bundle pet insurance with human coverage, leveraging payroll deduction and group pricing, reducing friction and adverse selection. Revenue sharing arrangements incentivise partners to promote enrollment, creating aligned interests absent in referral fee models. Real-time eligibility verification enables instant binding, eliminating application delays that cause abandonment. This contextual distribution strategy bypasses expensive broad awareness campaigns, delivering qualified leads already engaged in pet-related decision-making, representing the highest conversion efficiency pathway available.
Accelerated growth in embedded channels stems from business-to-business infrastructure enabling scalable distribution through trusted intermediaries who transfer credibility to insurance products while reducing customer acquisition costs. As per the Society for Human Resource Management, voluntary corporate benefits packages have actively integrated specialised animal healthcare options to enhance talent retention metrics across major domestic enterprise employers. According to the National Association of Insurance Commissioners, localised companion animal insurance regulatory frameworks are actively establishing standardised policy language to clarify voluntary claim handling procedures for multi-state policyholders. Veterinary partnerships leverage existing client relationships built over years of care, transferring professional endorsement that overcomes scepticism toward financial products. Shelters and rescue organisations embed enrollment during adoption processes, capturing emotionally invested owners at peak commitment moments while supporting mission-aligned messaging about responsible ownership. Technology platforms providing white label solutions enable rapid partner onboarding without custom integration, reducing deployment timelines from months to weeks. Data sharing agreements allow personalised offers based on partner customer profiles, increasing relevance versus generic marketing. Compliance frameworks pre-approved for specific partner types reduce regulatory friction, accelerating expansion. These B2B mechanisms transform fragmented individual sales into systematic bulk acquisitions, achieving scale economics impossible through direct consumer marketing alone while benefiting from institutional trust that reduces education burden and increases conversion velocity.
REGIONAL ANALYSIS
North America Pet Insurance Market Analysis
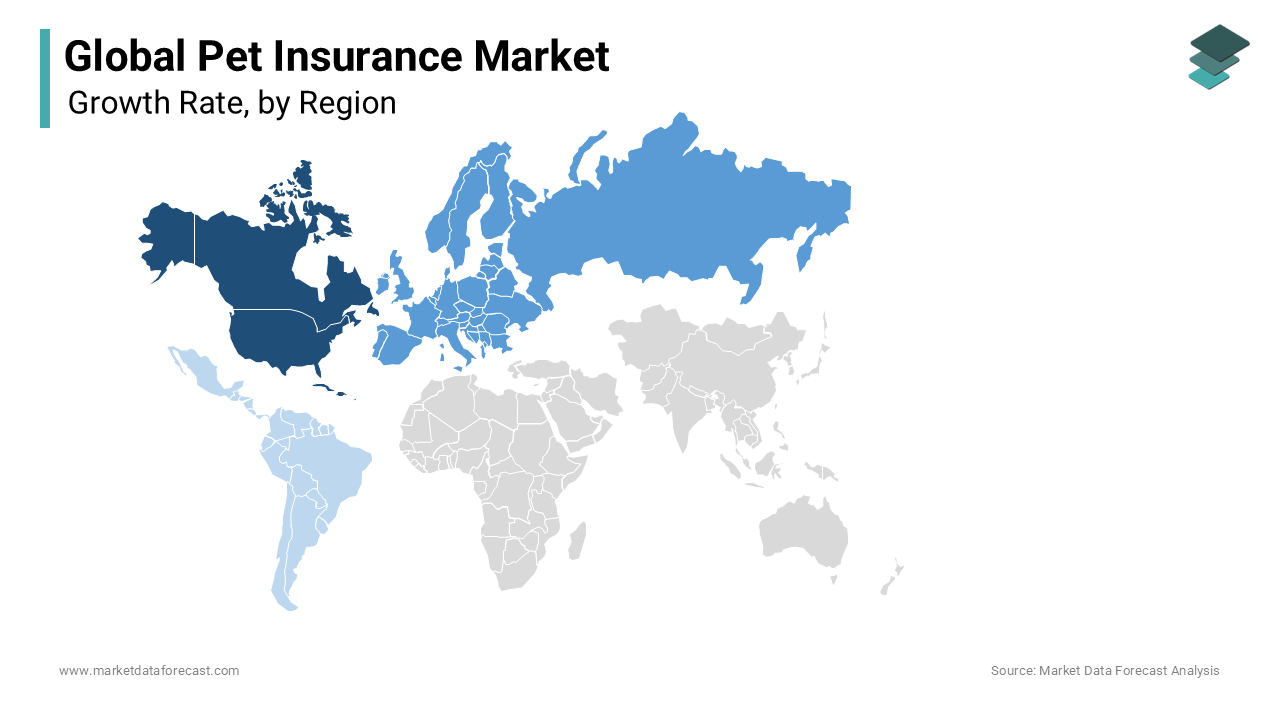
North America dominated the global pet insurance market and accounted for a 45.1% share in 2025. This dominance of the North American market was driven by the mature United States market and the rapidly developing Canadian sector with distinct regulatory and cultural dynamics. According to the North American Pet Health Insurance Association, total premium volume for pet insurance in the United States reached an active milestone of $3.9 billion, representing the vast majority of the collective North American marketplace. As per the North American Pet Health Insurance Association, the Canadian pet insurance segment exhibited active industry expansion as total in-force gross written premiums climbed by over 28 per cent for insured dogs. According to the American Veterinary Medical Association, escalating veterinary clinical expenses have actively driven consumer demand for comprehensive corporate wellness subscriptions and alternative employer-funded indemnity options. Employer-sponsored pet benefits expand rapidly. As per the Society for Human Resource Management, voluntary corporate benefits packages have actively integrated specialised animal healthcare options to enhance talent retention metrics across major domestic enterprise employers. According to the National Association of Insurance Commissioners, localised state insurance regulatory frameworks are actively adapting coverage definitions to standardise policy disclosures and consumer protection rules for cross-state underwriters. As per research, domestic companion animal integration trends show that 97 per cent of United States pet owners explicitly consider their animals to be part of their family. A mature competitive landscape drives product differentiation through wellness bundles and embedded distribution rather than pure price competition, distinguishing North American evolution from growth stage markets.
Europe Pet Insurance Market Analysis
Europe was the next prominent region in the global pet insurance market and captured a 38.2% share in 2025. This growth of the European market was fuelled by pioneering Nordic countries and the United Kingdom, with heterogeneous development across continental nations reflecting diverse welfare state traditions and veterinary financing norms. According to the British Veterinary Association, direct policy enrollment indicators confirm that the mature European companion animal insurance sector maintains highly concentrated consumer market penetration within Nordic countries. As per the Federation of Veterinarians of Europe, regional veterinary medical access strategies highlight that southern European consumer demographics utilise out-of-pocket payment models for primary animal clinical care. Scandinavian models feature automatic enrollment through breeding clubs and municipal registration, creating near-universal coverage absent in voluntary markets. United Kingdom operates the most competitive market, with several active carriers driving product innovation, including lifetime cover and direct vet payment schemes reducing reimbursement friction. European Union pet travel regulations increase cross-border mobility, creating demand for portable coverage harmonised across member states. Value added tax exemptions for pet insurance in several countries improve affordability versus taxed alternatives. Strong consumer protection regulations mandate transparent disclosure and fair claims handling, building trust that supports higher uptake. Diverse national characteristics require localised strategies, preventing pan-European standardisation unlike the more homogeneous North American market.
Asia Pacific Pet Insurance Market Analysis
Asia Pacific exhibits strong growth potential in the global pet insurance market. This growth is anchored by Japan's mature sector and China's emerging market undergoing rapid modernisation. According to the Yano Research Institute, the total Japanese companion animal business sector has demonstrated active market expansion, reaching a projected fiscal value of over 1.91 trillion yen, fueled by premium retail healthcare services and nutrition. As per the China Pet Industry White Paper, consumer metrics outline that over 71 per cent of modern urban households are actively prioritising specialised nutritional upgrades and digital medical wellness channels for their companion animals. According to Animal Medicines Australia, active policy subscription tracking reveals that approximately 24 per cent of domestic dog owners maintain comprehensive pet insurance coverage to mitigate rising surgical and clinical expenses. Cultural variations significantly impact product design, with Japanese policies emphasising senior pet coverage and chronic disease management reflecting demographic parallels to human society. As per studies, domestic companion animal brands are actively expanding their physical distribution networks within metropolitan commercial real estate complexes to enhance consumer proximity and brand retention. Regulatory frameworks remain nascent in most Asian jurisdictions, creating both opportunity and uncertainty for foreign entrants. Mobile-first distribution dominates with WeChat mini programs and QR code enrollment replacing traditional web-based models. Rising veterinary standards and pet humanisation trends suggest Asia Pacific will capture disproportionate future growth as current low penetration normalises toward Western benchmarks.
Latin America Pet Insurance Market Analysis
Latin America maintains a notable share of the global pet insurance market. Most of this market is in Brazil and Mexico, while other countries have very low growth due to unstable money and informal animal care. According to the IPB (Instituto Pet Brasil), overall commercial trade parameters for the regional companion animal marketplace have actively climbed past 50 billion reais, led by heightened middle-class consumer demand for specialised dry food segments. As per the National Autonomous University of Mexico, structural updates in localised small-animal healthcare demonstrate that metropolitan veterinary facilities are actively absorbing advanced imaging and specialised surgical infrastructure to meet premium care standards. Chile and Colombia show early signs of development, with multinational insurers establishing local operations, anticipating regional convergence. Economic instability creates dual dynamics with recessions suppressing premium affordability while inflationary veterinary costs increase the insurance value proposition for those able to pay. Distribution relies heavily on veterinary partnerships and pet store collaborations rather than direct digital channels, reflecting lower internet commerce penetration for financial products. Regulatory frameworks adapted from human health insurance models sometimes misalign with pet insurance realities, creating compliance friction. Currency hedging challenges deter foreign capital inflow, limiting product innovation. Despite constraints, Brazil’s scale and Mexico’s proximity to the US market create beachheads for eventual regional expansion as macroeconomic conditions stabilise and veterinary professionalism deepens across Latin American urban centres.
Middle East and Africa Pet Insurance Market Analysis
The Middle East and Africa region is expected to grow significantly in the global pet insurance market from 2026 to 2034. Market activity is heavily concentrated in the Gulf Cooperation Council states and South Africa. As per the South African Veterinary Association, diagnostic trends across regional small-animal clinics show an active increase in voluntary preventative clinical screenings as pet owners shift away from purely reactive emergency care models. Extreme climate conditions in the Gulf region necessitate indoor pet lifestyles, increasing veterinary dependency and accident risk from confined environments. High disposable incomes among Emirati and Saudi nationals support premium products with comprehensive coverage tiers exceeding Western equivalents. Expatriate turnover creates churn challenges requiring flexible short-term policies and international portability features. Religious considerations influence product acceptability, with Sharia-compliant structures gaining traction in Muslim-majority markets. Infrastructure deficits outside major cities limit veterinary access, concentrating insurance demand in urban enclaves. Development aid programs occasionally include animal welfare components, introducing insurance concepts to rural communities. This fragmented region combines luxury niche markets with frontier development opportunities requiring highly tailored approaches distinct from mass market strategies employed elsewhere globally.
COMPETITIVE LANDSCAPE
Competition in the pet insurance market is characterized by intense rivalry among established mutual insurers, specialized pure-play carriers, and emerging insurtech entrants vying for share through technological innovation and distribution creativity. Market leaders compete primarily on claims experience, speed, customization flexibility, and veterinary integration depth rather than price alone, as adverse selection risks make race-to-the-bottom pricing unsustainable. New entrants leverage superior user interfaces, embedded partnerships and alternative data sources, challenging incumbents burdened by legacy systems and traditional actuarial assumptions. Consolidation accelerates as large financial services firms acquire specialized players, gaining instant scale and expertise while providing capital for technology modernization and geographic expansion. Product homogenization threatens commoditization, forcing differentiation through value-added services including telemedicine access, wellness rewards, and behavioral health support. Customer acquisition costs remain elevated, driving focus on retention, lifetime value optimization, and cross-sell opportunities within existing book business. Regulatory scrutiny intensifies regarding rate adequacy claims handling, fairness, and disclosure transparency, raising compliance barriers favoring well-capitalized operators. This dynamic competitive landscape rewards companies balancing growth discipline with sustainable unit economics, ensuring long-term viability beyond venture-subsidized customer acquisition phases characteristic of earlier market development stages.
KEY MARKET PLAYERS
The leading companies operating in the global pet insurance market include:
- Trupanion
- Figo Pet Insurance
- Healthy Paws
- Petplan Pet Insurance
- Embrace Pet Insurance Agency
- Royal & Sun Alliance (RSA)
- Pethealth Inc.
- Agria Pet Insurance
- Pet first Healthcare
- Nationwide Pet Insurance
- PetSure Pty Ltd.
- Petsecure Pet Health Insurance
- Hartville Group
TOP PLAYERS IN THE MARKET
- Trupanion Inc maintains significant global involvement through its proprietary veterinary hospital integration platform, enabling real-time claims processing and direct payment at point of care. The company recently expanded its VetDirect Pay solution across Canada and Australia, strengthening provider relationships that differentiate its service model from traditional reimbursement competitors. Trupanion invests heavily in data analytics, leveraging millions of historical claims to refine underwriting accuracy and personalize premium pricing for individual pets. Strategic partnerships with animal shelters and rescue organizations embed enrollment during adoption processes, capturing motivated new owners at critical decision moments. Their focus on lifetime coverage without payout limits addresses consumer concerns about chronic disease exclusions prevalent elsewhere. These initiatives reinforce Trupanion’s position as infrastructure partner rather than mere indemnifier, building sustainable competitive advantages through ecosystem integration and trust-based veterinary endorsements worldwide.
- Nationwide Mutual Insurance Company contributes globally through comprehensive product portfolios spanning accident, illness, wellness, and exotic pet coverage addressing diverse consumer segments beyond mainstream dog and cat markets. The company recently launched an enhanced digital claims platform, reducing processing times by improving member satisfaction and retention in a competitive landscape. Nationwide leverages its existing human insurance customer base through bundling discounts and cross-sell campaigns, achieving lower acquisition costs than pure-play pet insurers. Strategic investments in preventive care benefits align with veterinary recommendations, creating engagement touchpoints beyond episodic claims. Their research institute publishes annual pet health data, establishing thought leadership and brand credibility among veterinarians and consumers alike. Educational initiatives targeting first-time pet owners demystify insurance concepts, expanding the addressable market through transparency. These multifaceted efforts strengthen Nationwide’s position as a trusted household brand, extending human insurance loyalty into companion animal financial protection across North America and select international markets.
- Embrace Pet Insurance participates globally through customizable policy architecture allowing owners to tailor deductibles, reimbursement rates, and annual limits matching individual budget constraints and risk tolerance. The company recently introduced a diminishing deductible feature rewarding claim-free years with reduced out-of-pocket costs, incentivizing long-term retention and responsible ownership behaviors. Embrace expanded wellness rewards program covering routine care expenses previously excluded from standard policies, increasing perceived value and engagement frequency. Strategic content marketing through blog resources and breed-specific health guides establishes organic search visibility, capturing high-intent prospects during research phases. Partnerships with veterinary technology platforms enable seamless quote generation within practice management software, reducing friction during clinic visits. Their emphasis on transparent policy language and educational resources addresses industry-wide trust deficits, differentiating the brand in a crowded marketplace. These customer-centric innovations strengthen Embrace’s niche positioning among informed consumers seeking flexibility and clarity over commoditized one-size-fits-all offerings dominating mass market channels.
TOP STRATEGIES USED BY KEY MARKET PARTICIPANTS
Key participants employ multifaceted strategies centered on product differentiation through customizable coverage options, wellness benefit integration, and chronic disease management riders addressing diverse consumer needs beyond basic accident and illness indemnification. Companies prioritize embedded distribution partnerships with veterinary clinics, shelters, employers, and retail platforms, capturing motivated consumers at contextual moments of highest relevance while reducing expensive broad awareness marketing expenditures. Technology investments in artificial intelligence-powered underwriting, automated claims processing, and mobile-first user experiences reduce operational costs and improve satisfaction metrics critical for retention in a voluntary, discretionary product category. Data analytics capabilities enable personalized pricing, dynamic risk assessment, and targeted upsell opportunities, transforming static policies into adaptive relationships responding to individual pet health trajectories. Strategic acquisitions of complementary insurtech firms accelerate capability development in areas like telemedicine integration, wearable device connectivity, and predictive health modeling. Regulatory engagement ensures compliance across fragmented jurisdictions while shaping favorable frameworks for innovation. Brand building through educational content, veterinary partnerships, and community sponsorships establishes trust essential for financial products where promise fulfillment occurs years after purchase. These interconnected strategies collectively sustain competitive positioning in maturing markets where differentiation increasingly depends on holistic solution ecosystems rather than standalone price or coverage features alone.
MARKET SEGMENTATION
This research report on the global pet insurance market is segmented & sub-segmented based on animal type, policy type, sales channel, and region.
By Policy Type
- Accident & Illness
- Accident only
- Others
By Animal Type
- Dogs
- Cats
- Others
By Sales Channel
- Agency
- Broke
- Direct
- Bancassurance
- Others
By Region
- North America
- Europe
- Asia-Pacific
- Latin America
- Middle East and Africa