- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$28.81 BnMarket Estimate, 2026
$30.54 BnMarket Forecast, 2034
$48.68 BnCAGR, 2026–2034
6%Saudi Arabia Food Service Market Summary
The Saudi Arabia food service market was valued at USD 28.81 billion in 2025, is projected to reach USD 30.54 billion in 2026, and is expected to expand to USD 48.68 billion by 2034, growing at a CAGR of 6% from 2026 to 2034. The growth of the Saudi Arabian food service market is driven by rapid urbanization, a young population with evolving dietary preferences, and increasing demand for quick and convenient dining experiences. The expansion of international fast-food chains, coupled with the rise of delivery platforms and food aggregators, is further fueling market growth.
Key Market Trends
- The rising popularity of quick service restaurants (QSRs) catering to fast-paced lifestyles.
- Increasing adoption of food delivery apps and online ordering platforms.
- Growing preference for international cuisines alongside traditional Saudi dishes.
- Expansion of casual dining formats targeting families and young professionals.
- Investments in health-conscious and premium dining options.
Segmental Insights
- Based on place type, the quick service restaurants (QSR) segment was the largest in 2025, holding 42.3% share, driven by affordability, convenience, and the presence of global QSR brands.
- Based on end user, the commercial and office segment led the market with 30.2% share in 2025, reflecting strong demand for corporate catering and workplace dining services.
Regional Insights
- Riyadh serves as the largest hub for the Saudi Arabian food service market, supported by rapid urbanization, a growing expat community, and strong QSR penetration.
- Jeddah and Dammam are witnessing steady growth due to expanding retail hubs, tourism, and rising demand for premium foodservice outlets.
- Other cities in the Kingdom are emerging markets, supported by government initiatives under Vision 2030 to diversify the economy and strengthen the hospitality and foodservice sectors.
Competitive Landscape
Major players in the Saudi Arabian food service market include KFC, McDonald’s, Pizza Hut, Burger King, Shawaya House, Dajen, Al-Beck, Herfy, Kudo, and Taza. These companies are focusing on menu innovation, digital ordering platforms, and aggressive outlet expansion to capture a larger share of the fast-growing Saudi market.
Saudi Arabia Food Service Market Size
The Saudi Arabia food service market size was calculated to be USD 28.81 billion in 2025 and is anticipated to be worth USD 48.68 billion by 2034, from USD 30.54 billion in 2026, growing at a CAGR of 6% during the forecast period.
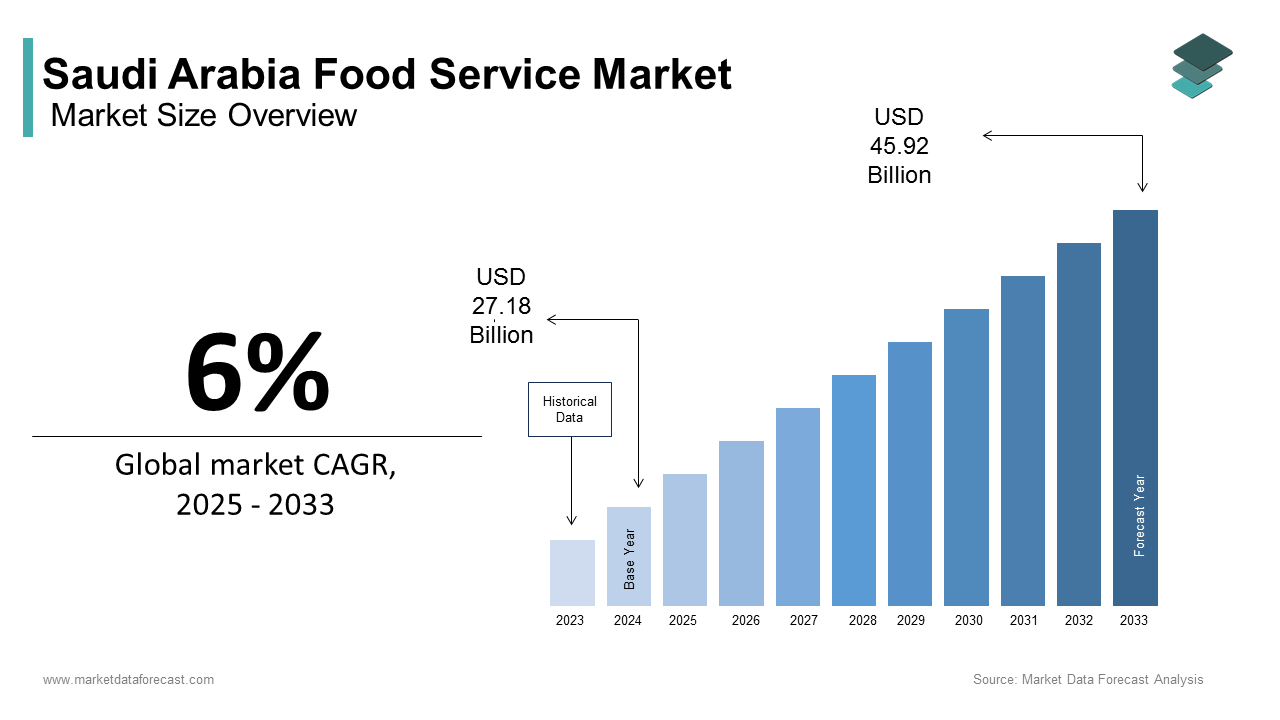
The food service provides prepared meals and beverages for immediate consumption, including quick-service restaurants (QSRs), fine dining venues, cafés, food trucks, and institutional catering services. As per the Saudi Central Bureau of Statistics, over 68% of households in major cities like Riyadh and Jeddah consume at least one meal outside the home each week, reflecting a structural shift in dietary behavior. The integration of digital platforms by evolving consumer preferences, and national economic transformation under Vision 2030 are collectively redefining how food is accessed, consumed, and experienced in the Kingdom.
MARKET DRIVERS
Youth Demographics and Shifting Consumption Habits
The rising young population is a primary driving factor for the growth of the Saudi Arabia food service market. A 2023 survey by YouGov, 72% of Saudis aged 18–24 order food delivery at least twice a week, with strong preferences for international cuisines and branded chains. This demographic is increasingly engaging in social dining, with malls and entertainment zones becoming key food consumption hubs. The weekend foot traffic in Riyadh’s Boulevard World and Jeddah’s Red Sea Mall has many visitors, which escalates the utilization of on-site food services.
Government-Led Urban Development and Entertainment Initiatives
The strategic investment in urban regeneration and entertainment infrastructure is directly fueling the growth of Saudi Arabia food service market. As part of Vision 2030, Saudi Arabia has launched giga-projects such as NEOM, Qiddiya, and the Red Sea Global destinations, all designed to host millions of visitors annually and feature extensive food and beverage zones. Qiddiya, positioned as an entertainment capital, plans to include over 100 food and beverage outlets upon full development, as per its master plan. Similarly, the Diriyah Gate project in Riyadh integrates traditional souks with modern culinary concepts, attracting both locals and tourists. The Public Investment Fund’s backing of such developments ensures sustained capital inflow, enabling long-term planning for restaurant chains and independent operators.
MARKET RESTRAINTS
Regulatory Complexity and Licensing Fragmentation
The operational hurdles due to overlapping regulatory jurisdictions and inconsistent enforcement is degrading the growth of Saudi Arabia food service market. As per the Saudi Standards, Metrology and Quality Organization (SASO), over 30% of new food service applications experience delays exceeding 90 days due to coordination gaps between municipal authorities, health inspectors, and fire safety departments. In secondary cities like Hail and Najran, local municipalities apply varying interpretations of halal certification and kitchen ventilation standards, creating compliance uncertainty. Additionally, the rollout of the national digital licensing platform, Baladi, has been uneven, with many operators in rural areas lacking digital access. These systemic inefficiencies increase time-to-market, discourage small entrepreneurs, and hinder the formalization of significant portion of the sector in independent and street food segments.
Dependence on Expatriate Labor and Workforce Sustainability
The stringent rules, which are vulnerable to labor policy shifts and wage pressures is substantially to hinder the growth of Saudi Arabia food service market. As per the Ministry of Human Resources and Social Development, over 85% of frontline staff in restaurants and cafés are expatriates, primarily from South Asia and Egypt. A 2023 report by the King Abdullah Petroleum Studies and Research Center (KAPSARC) found that only 14% of Saudi nationals express willingness to work in food service roles, citing perceived low status and demanding hours. This mismatch forces operators to offer higher wages to attract local talent, increasing operating costs by up to 18%, according to the Saudi Hospitality Association. Additionally, recent increases in expatriate levies and dependant fees have raised labor costs, compelling some chains to automate or scale back expansion.
MARKET OPPORTUNITIES
Expansion of Cloud Kitchens and Delivery-Only Models
The rise of digital platforms and changing urban lifestyles for delivery-centric food service models is elevating new opportunities for the growth of Saudi Arabia food service market. HungerStation is the leading platform, reported over 15 million active users and 35 million annual orders in 2023, with delivery accounting for 58% of total food service transactions in Riyadh and Dammam. Companies like Kitopi and Sarwa Foods have partnered with international brands to launch virtual restaurants, minimizing overhead while maximizing reach. With urban congestion and high car ownership reducing dine-in frequency, cloud kitchens offer scalability, particularly in secondary cities where real estate costs are lower.
Localization of Global Concepts and Culinary Innovation
There is growing momentum for hybrid food offerings that blend international formats with Saudi tastes by creating a unique competitive advantage. As per NielsenIQ, 78% of Saudi consumers prefer fast food items adapted to local flavor profiles, such as shawarma-infused burgers or date-based desserts. The Ministry of Culture’s “Saudi Seasons” initiative has further amplified culinary innovation, with food festivals in AlUla and Diriyah attracting over 2 million visitors in 2023, as per the Ministry of Tourism. These platforms allow emerging chefs to test new concepts, supported by government-backed incubators.
MARKET CHALLENGES
High Operational Costs in Prime Locations
Securing and maintaining a presence in high-footfall urban areas involves substantial financial commitments that strain profitability for mid-tier and independent operators may restrict the growth of Saudi Arabia food service market. These costs are compounded by utility tariffs and mandatory fit-out standards, pushing initial setup expenses beyond SAR 1.5 million for a mid-sized restaurant.
Intensifying Competition and Brand Differentiation
The rapid influx of both global chains and local startups has saturated key segments by making differentiation increasingly difficult. This attribute is to hamper the growth of Saudi Arabia food service market in coming years. As per the Ministry of Municipal and Rural Affairs, over 8,000 new food service licenses were issued in 2023 alone, with a concentration in fast-casual and coffee segments. In Riyadh’s King Fahd Road corridor, one in every three retail units now hosts a café or quick-service outlet, according to Knight Frank. International entrants like Shake Shack and Tim Hortons compete with established players like Al Baik and Herfy, while digital-native brands emerge with lower overhead. Operators lacking a clear value proposition or digital presence risk being marginalized, even in high-demand areas, as consumer expectations evolve beyond mere sustenance to encompass identity, wellness, and social validation.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 6% |
| Segments Covered | By Place Type, End User and Region |
| Various Analyses Covered | Global, Regional & Country Level Analysis; Segment-Level Analysis; DROC, PESTLE Analysis; Porter’s Five Forces Analysis; Competitive Landscape; Analyst Overview of Investment Opportunities |
| Regions Covered | Riyadh, Makkah, Madinah, Qassim, Eastern Province, Asir, Tabuk, Hail, Northern Borders, Jazan, Najran, Al Bahah, Al Jawf |
| Market Leaders Profiled | KFC, McDonald's, Pizza Hut, Burger King, Shawaya House, Dajen, Al-Beck, Herfy, Kudo, and Taza |
SEGMENTAL ANALYSIS
By Place Type Insights
The quick service restaurants segment was the largest by accounting for 42.3% of the Saudi Arabia food service market share in 2025. Saudi Arabia’s urban youth in Riyadh, Jeddah, and Dammam, favor speed, affordability, and digital convenience core attributes of QSRs. McDonald’s, KFC, and local leader Al Baik have optimized operations for high-volume throughput, with Al Baik serving over 1 million customers daily across its 180+ outlets, as per company disclosures. The expansion of QSRs into secondary cities like Buraidah and Tabuk, supported by franchising models, has extended their reach.
The managed food service segment is likely to grow with an expected CAGR during the forecast period. According to the Public Investment Fund, NEOM alone will require feeding over 9 million annual visitors and 380,000 residents by 2030. International firms like Sodexo and Aramark have secured multi-year contracts to operate staff cafeterias, visitor dining, and event catering within these zones. In industrial cities like King Abdullah Economic City (KAEC), managed food service providers supply over 120,000 meals per month to workers, as per KAEC’s 2023 sustainability report. These contracts emphasize nutrition, halal compliance, and waste reduction, aligning with national sustainability goals.
By End-User Insights
The commercial and office segment was the largest and held 30.2% of the Saudi Arabia food service market share in 2025. Saudi Arabia’s rapid development of commercial hubs such as Riyadh’s King Abdullah Financial District (KAFD) and Jeddah’s Business Gate has created dense ecosystems where thousands of employees require daily meal solutions. Employers are increasingly investing in on-site cafeterias and premium food courts to enhance employee satisfaction and retention. The Human Resources Development Fund reports that 82% of private-sector companies now offer subsidized or free lunch programs, viewing food as a core component of workplace wellness. International chains like Costa Coffee and local brands such as Nama Café have established flagship outlets in these zones, capitalizing on high foot traffic.
The I-transit food service segment is expected to witness a CAGR of 13.2% during the forecast period. Saudi Arabia’s investment in transportation networks is creating new demand for food services in airports, metro stations, and intercity terminals. International brands like Burger King and local chains such as Herfy have secured exclusive concession rights, ensuring brand visibility and high turnover. With the government targeting 150 million annual domestic trips by 2030, in-transit dining is becoming a critical revenue channel. Travelers increasingly expect seamless, high-quality food options during transit, with halal compliance and speed as non-negotiables. Airports like King Abdulaziz International in Jeddah have introduced digital kiosks and mobile ordering to reduce wait times, with average transaction time for food purchases dropping from 12 to 5 minutes, per airport management data. The rise of premium economy and business travel has also driven demand for gourmet in-transit meals, with airlines and rail operators partnering with celebrity chefs.
REGIONAL ANALYSIS
Saudi Arabia food service market Insights
Saudi Arabia food service market was the largest contributor with 38.3% of share in 2025 with its vast population over 36 million people, according to the General Authority for Statistics and aggressive economic diversification under Vision 2030. The Public Investment Fund has allocated over SAR 50 billion to entertainment and hospitality giga-projects, each designed with extensive F&B zones.
LEADING PLAYERS IN THE SAUDI ARABIA FOOD SERVICE MARKET
Al-Mansour Group
Al-Mansour Group is a leading player in the Saudi Arabia Food Service Market, operating prominent international quick-service restaurant (QSR) brands such as KFC, Pizza Hut, and Starbucks across the Kingdom. The company has significantly expanded its footprint by investing in digital transformation, including mobile apps, delivery integrations, and AI-driven customer engagement tools. Al-Mansour has strengthened its market position through localized menu offerings and strategic partnerships with delivery platforms like HungerStation. In the Asia Pacific region, the group contributes by sharing operational best practices and technology integration models with franchise operators, enhancing service efficiency and customer experience. Recent initiatives include opening new outlets in secondary cities and launching sustainability programs to reduce environmental impact.
Herfy Food Services Company
Herfy is one of Saudi Arabia’s largest homegrown fast-food chains, known for its halal-compliant menu and strong brand loyalty. The company operates an extensive network of drive-thrus, delivery hubs, and dine-in outlets, emphasizing speed and affordability. Herfy has invested heavily in automation, cloud kitchens, and digital ordering platforms to meet rising demand for convenience. It recently expanded its presence in urban centers and launched innovative promotions aligned with national events like Saudi Seasons. In the Asia Pacific market, Herfy serves as a benchmark for localized QSR models, inspiring regional operators with its integration of cultural preferences into menu development and marketing. Its technology-driven logistics system has also drawn interest from operators seeking efficient last-mile delivery solutions.
Americana Group
Americana Group is a major multinational food and beverage operator with a dominant presence in Saudi Arabia through brands like KFC, Pizza Hut, Hardee’s, and Costa Coffee. The company has reinforced its market position by modernizing outlets, enhancing digital ordering capabilities, and expanding delivery infrastructure. It has launched localized marketing campaigns and introduced region-specific menu items to cater to Saudi consumers. In the Asia Pacific region, Americana contributes by transferring operational expertise in multi-brand management and supply chain optimization. Recent actions include investing in sustainability initiatives and opening experiential flagship stores in major malls. Its focus on employee training and customer experience innovation strengthens its competitive edge across diverse markets.
TOP STRATEGIES USED BY THE KEY MARKET PARTICIPANTS
Key players in the Saudi Arabia Food Service Market employ strategies such as digital transformation, menu localization, and delivery network expansion to enhance competitiveness. Companies invest in mobile apps, AI-driven analytics, and self-service kiosks to improve customer experience. Franchise optimization and multi-brand operations enable cost efficiency and wider reach. Strategic partnerships with delivery platforms like Jahez and HungerStation ensure rapid service. Expansion into secondary cities and mall-based outlets increases accessibility. Sustainability initiatives, including eco-friendly packaging and energy-efficient kitchens, align with national Vision 2030 goals. Brand repositioning through cultural marketing during festivals and seasonal events strengthens consumer engagement and loyalty across diverse customer segments.
KEY MARKET PLAYERS AND COMPETITION OVERVIEW
Major Players of the Saudi Arabia Food Service Market include KFC, McDonald's, Pizza Hut, Burger King, Shawaya House, Dajen, Al-Beck, Herfy, Kudo, and Taza
The Saudi Arabia Food Service Market is highly competitive, characterized by a mix of international franchise operators and strong local brands vying for consumer preference. Rapid urbanization, a young population, and rising disposable incomes drive demand for convenient and diverse dining options. Companies differentiate through digital innovation, delivery speed, and culturally relevant menus. Intense rivalry exists among QSR chains, with aggressive expansion, promotional campaigns, and technology adoption being common tactics. The market also sees growing competition from cloud kitchens and food delivery aggregators. Government initiatives under Vision 2030 further stimulate investment and innovation, which is making the sector dynamic and increasingly consolidated around major players with scalable, tech-integrated models.
Saudi Arabia Food Service Market News
- In April 2025, Al-Mansour Group launched a new digital loyalty program across its KFC and Starbucks outlets in Saudi Arabia, integrating AI-powered personalization to enhance customer retention and boost repeat visits through tailored promotions and rewards.
- In January 2025, Herfy Food Services opened 15 new automated drive-thru locations in secondary cities including Abha and Hail, expanding its geographic reach and leveraging technology to reduce wait times and improve service efficiency.
MARKET SEGMENTATION
This research report on the Saudi Arabia food service market has been segmented and sub-segmented based on place type and end user
By Place Type
- Full Service Restaurants
- Quick Service Restaurants
- Food Junctions/Cafeterias/Buffets
- Bars
- Managed Food Service
By End User
- Industrial Premises
- Commercial and Office Premises
- Hospital & Nursing Homes
- Educational Premises
- In-transit Food Service
- Sports Centers/Malls
By Region
- Riyadh
- Makkah
- Madinah
- Qassim
- Eastern Province
- Asir
- Tabuk
- Hail
- Northern Borders
- Jazan
- Najran
- Al Bahah
- Al Jawf