- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$54.34 BnMarket Estimate, 2026
$60.69 BnMarket Forecast, 2034
$146.98 BnCAGR, 2026–2034
11.69%Executive Summary: Asia Pacific Cybersecurity Market
- Market Scope: Comprehensive regional cybersecurity market analysis covering deployment models, organization sizes, vertical industries, country leadership frameworks, and cloud-native and AI-enabled XDR trends.
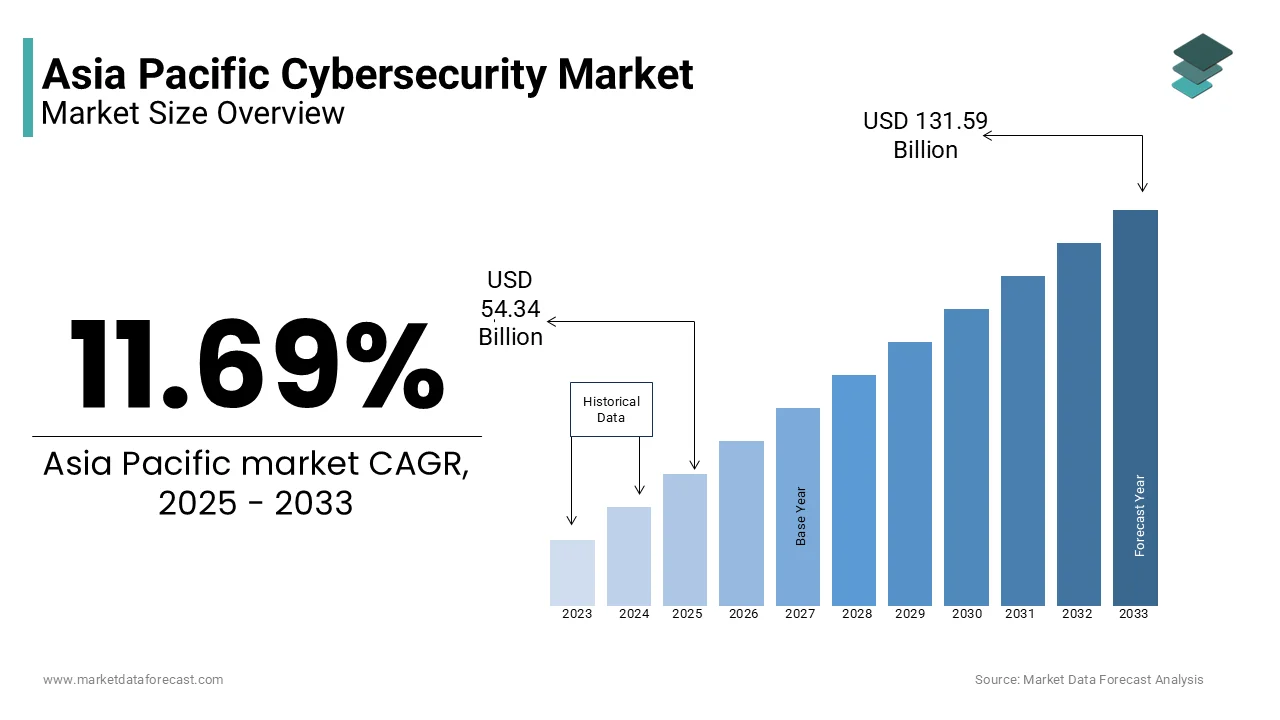
- Market Valuation: Valued at USD 54.34 billion (2025), estimated at USD 60.69 billion (2026), and projected to reach USD 146.98 billion by 2034, registering a solid CAGR of 11.69% (2026–2034).
- Primary Growth Drivers: Accelerating digital transformation, rising IoT adoption across connected environments, stringent government regulations enhancing national cyber defenses, and cloud-based security investments exceeding USD 6.1 billion.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (Base Position) | Fastest-Growing Segment |
|---|---|---|
| By Deployment & Component | Cloud Deployment and Integrated Software Solutions | Cybersecurity Services (projected to grow at the fastest CAGR) |
| By Enterprise Size | Large Enterprises (estimated to hold the largest market share via cyber insurance adoption) | Small and Medium-Sized Enterprises (adopting scalable, on-demand cloud defense) |
| By Industry Vertical | IT & Telecom and Manufacturing (together accounting for nearly 50% market share) | Aerospace & Defense (predicting considerable growth due to government investments) |
| By Region / Country | China (biggest cybersecurity market in the Asia Pacific region) | India (anticipated to surge via CERT-In incident handling and security architecture enhancements) |
Major Market Players & Market Structure
Market Structure: Highly competitive regional cyber defense landscape where leading multinational tech corporations deliver comprehensive security portfolios, AI-enabled XDR platforms, and cloud-native solutions to counter state-sponsored threats.
Key Companies: NEC Corporation, Cisco Systems Inc., Kaspersky Labs, Dell Technologies Inc., Check Point Software Technologies Ltd., IBM Corporation, Imperva, and Proofpoint Inc.
 Download Free Sample Report
Asia Pacific Cybersecurity Market Size
The Asia-Pacific cybersecurity market was valued at USD 54.34 billion in 2025 and is projected to reach USD 146.98 billion by 2034. This represents a compound annual growth rate (CAGR) of 11.69% from 2026 to 2034, with the market expected to scale up from USD 60.69 billion in 2026.
Cybersecurity is used to protect digital infrastructure networks and data assets across the diverse economies of the region. As per the International Telecommunication Union, internet penetration in the Asia Pacific region has surpassed 55%, with over 2.5 billion users coming online primarily through mobile devices, creating an exponentially expanding attack surface for malicious actors. The rapid digitization of infrastructure, including finance, healthcare, and energy, necessitates advanced threat detection and response capabilities. Governments are increasingly enacting stringent data sovereignty laws and mandatory breach notification requirements, driving compliance-driven investments. The proliferation of Internet of Things devices in smart cities and industrial automation further complicates the security landscape, requiring specialized endpoint protection. Regional disparities in technological maturity create a fragmented demand pattern ranging from basic antivirus solutions in developing nations to sophisticated zero trust architectures in advanced economies. The shortage of skilled cybersecurity professionals remains a critical bottleneck influencing service delivery models. Strategic partnerships between local integrators and global vendors shape the competitive dynamics.
MARKET DRIVERS
Rapid Digital Transformation and Cloud Adoption Accelerate Demand
The aggressive pace of digital transformation and cloud migration, which is fuelling the growth of the Asia Pacific Cybersecurity Market. Organizations in the region have experienced cloud-related security incidents due to misconfigurations or lack of visibility, driving urgent adoption of Cloud Access Security Brokers and Cloud Workload Protection Platforms. This transition moves security perimeters from physical boundaries to dynamic virtual environments, necessitating continuous monitoring and automated policy enforcement. Financial institutions and retail giants are leading this shift, requiring real-time threat intelligence to protect customer data during high-volume transactions. The integration of legacy systems with modern cloud platforms creates vulnerability gaps that attackers exploit. Enterprises prioritize solutions that offer seamless integration and centralized management across multi-cloud setups. Regulatory pressures regarding data residency further compel companies to adopt secure cloud architectures.
Stringent Data Privacy Regulations and Compliance Mandates
The implementation of rigorous data privacy laws and national cybersecurity standards is additionally propelling the growth of the Asia Pacific Cybersecurity Market. The Personal Data Protection Commission in Singapore and the Personal Information Protection Law in China require organizations to implement strict access controls, encryption, and incident response plans to safeguard citizen data. The United Nations Conference on Trade and Development notes that over 15 countries in the Asia Pacific region have enacted or updated comprehensive data protection legislation in the past three years, forcing multinational corporations to localize security operations and invest in compliance tools. These regulatory frameworks create a baseline requirement for security investments regardless of company size or industry. Non-compliance can result in fines amounting to millions of dollars and severe reputational damage. Organizations must conduct regular audits and vulnerability assessments to demonstrate adherence to these standards. The complexity of navigating different legal regimes across borders drives demand for managed security services that offer regulatory expertise. This legislative wave ensures that cybersecurity budget allocation becomes a mandatory operational expense rather than a discretionary investment.
MARKET RESTRAINTS
Fragmented Regulatory Landscape and Cross-Border Complexity
The lack of harmonized cybersecurity regulations is a compliance burden and operational inefficiency for multinational organizations, restricting the growth of the Asia-Pacific cybersecurity market. The inconsistent legal frameworks increase the cost of doing business for technology firms operating across multiple jurisdictions, as they must customize security architectures for each local area. Companies must maintain separate compliance teams and technical configurations for each country, increasing overheads. The uncertainty regarding cross-border data transfer rules hinders the adoption of centralized cloud security solutions. Small and medium enterprises often struggle to navigate these complex requirements, leading to inadequate protection. The absence of mutual recognition agreements for security certifications delays product launches and service deployments. Investors hesitate to fund regional expansion due to regulatory unpredictability.
Acute Shortage of Skilled Cybersecurity Professionals
The severe deficit of qualified cybersecurity talent is limiting the ability of organizations to effectively deploy, manage, and monitor advanced security technologies. The acute shortage of skilled cybersecurity professionals is additionally hindering the growth of the Asia Pacific cybersecurity market. The Asia Pacific region faces a shortfall of over 2 million cybersecurity professionals, with countries like India, Australia, and Japan reporting the highest gaps in skilled personnel. Organizations in the region have insufficient staff to handle incident response and threat hunting, leading to prolonged detection times and increased vulnerability to sophisticated attacks. This skills gap forces companies to rely heavily on managed security service providers, which may not always align with internal strategic goals. High turnover rates and salary inflation further exacerbate the problem, making retention difficult. Existing staff often suffer from burnout due to excessive workloads, reducing operational effectiveness. Educational institutions struggle to update curricula fast enough to match the evolving threat landscape. The lack of certified experts delays the implementation of complex projects such as zero trust architecture.
MARKET OPPORTUNITIES
Expansion of Smart City Initiatives and IoT Ecosystems
The widespread deployment of smart city infrastructure and Internet of Things devices is creating new vectors for protection and monitoring services, which is attributed to boosting the growth of the Asia Pacific cybersecurity market. As per the McKinsey Global Institute, smart city investments in Asia Pacific are expected to reach 400 billion dollars by 2025, with millions of connected sensors, cameras, and controllers managing traffic utilities and public safety systems. Municipalities and private operators require robust network segmentation and anomaly detection to prevent large-scale disruptions. The convergence of operational technology and information technology in these environments creates unique security challenges that traditional IT solutions cannot address. Vendors can offer specialized firmware protection and lifecycle management services for these devices. Governments are prioritizing secure-by-design principles in procurement processes. This massive rollout of connected infrastructure generates recurring revenue streams for security providers. It opens new market segments beyond traditional enterprise IT.
Growth of Managed Security Service Providers in Emerging Economies
The rising adoption of Managed Security Service Providers is particularly among small and medium-sized enterprises in emerging economies that lack internal expertise. The growth of managed security providers in emerging economies is also to bolster the growth of the Asia Pacific cybersecurity market. The organizations in Southeast Asia prefer outsourcing their security operations to MSSPs due to the high cost and complexity of building in-house security operations centers. This model allows businesses to focus on core competencies, while ensuring robust protection. MSSPs are increasingly offering modular and subscription-based services that cater to diverse budget constraints. They provide scalability, allowing clients to adjust services as their digital footprint expands. Local MSSPs gain an advantage by understanding regional threat landscapes and regulatory nuances. Partnerships with global technology vendors enable them to offer state-of-the-art tools.
MARKET CHALLENGES
Sophisticated State-Sponsored and Organized Cyber Attacks
The increasing frequency and sophistication of state-sponsored and organized cyberattacks is a major challenge for the growth of the Asia Pacific cybersecurity market. Asia Pacific is the most targeted region for advanced persistent threats, with state actors focusing on intellectual property theft and disruption of critical infrastructure in countries like South Korea, Japan, and Australia. These advanced threats require expensive and complex solutions such as behavioral analytics and artificial intelligence-driven detection, which are beyond the reach of many organizations. The geopolitical tensions in the region further incentivize cyber espionage and sabotage. Defenders must constantly update signatures and tactics to keep pace with agile adversaries. The high cost of recovery and potential regulatory fines add to the burden. Small businesses often shut down after such attacks due to inability to recover.
Legacy Infrastructure and Technical Debt in Critical Sectors
The prevalence of outdated legacy infrastructure and significant technical debt in sectors such as banking, energy, and manufacturing is also to decline the growth of the Asia Pacific cybersecurity market. Many power grids in developing Asian nations rely on supervisory control and data acquisition systems that were never designed with cybersecurity in mind, making them susceptible to remote exploitation and sabotage. Retrofitting these systems with security layers is technically complex and risky, often requiring complete system shutdowns. Organizations hesitate to invest in modernization due to fear of operational disruption. The lack of vendor support for obsolete software leaves known vulnerabilities unpatched. Security teams struggle to gain visibility into these black box systems. This technical inertia slows down the adoption of zero trust and other modern security frameworks.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Covered | By Component, Deployment Type, Enterprise, End-User, and Country. |
| Various Analyses Covered | Global, Regional, and Country-Level Analysis, Segment-Level Analysis, Drivers, Restraints, Opportunities, Challenges; PESTLE Analysis; Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Countries Covered | India, China, Japan, South Korea, Australia, New Zealand, Thailand, Malaysia, Vietnam, Philippines, Indonesia, Singapore, Rest of Asia Pacific |
| Market Leaders Profiled | NEC Corporation, Trend Micro Inc, Cisco Systems Inc., Kaspersky Labs, Dell Technologies Inc., Check Point Software Technologies Ltd., Fortinet Inc, Palo Alto Networks Inc, IBM Corporation, Imperva and Proofpoint Inc. |
SEGMENTAL ANALYSIS
By Component Insights
The solutions segment was the largest, holding 54.8% of the Asia Pacific Cybersecurity Market share in 2025, with the escalating sophistication of cyber threats requiring organizations to deploy advanced software tools for proactive defense and real-time threat detection. The security breaches in the region are attributed to unpatched vulnerabilities or misconfigured software, amplifying the need for automated vulnerability management and configuration assessment solutions. These statistics demonstrate that static defense mechanisms are no longer sufficient, driving demand for dynamic solution-based architectures. Organizations prioritize solutions that offer artificial intelligence-driven analytics to identify anomalies before they escalate into full-scale attacks. The complexity of hybrid cloud environments further necessitates specialized software that can provide visibility across distributed networks. Regulatory mandates for data protection also require specific encryption and access control solutions to ensure compliance. The continuous evolution of attack techniques ensures that solution providers must constantly update their offerings, creating a recurring revenue model.
The services segment is likely to grow at the fastest CAGR of 18.5% during the forecast period, with the severe shortage of skilled cybersecurity professionals, which forces organizations to outsource their security operations to managed service providers. As per the International Information System Security Certification Consortium, the Asia Pacific region faces a deficit of 2.1 million cybersecurity workers, leaving many organizations unable to staff internal security operations centers effectively. This talent gap compels companies to rely on external experts for 24/7 monitoring, incident response, and threat hunting. Managed service providers offer access to a broader pool of certified experts and advanced tools that individual firms cannot afford. The complexity of managing multi-vendor security stacks further drives the need for professional integration and consulting services. Businesses prefer predictable operational expenditure models over high capital investments in internal teams.
By Enterprise Insights
The large enterprises segment held a significant share of the Asia Pacific Cybersecurity Market in 2025 due to their significant financial resources and the nature of their operations, which necessitate comprehensive and layered security frameworks. The Association of Southeast Asian Nations states that multinational corporations operating in the region must comply with strict cross-border data transfer regulations requiring expensive enterprise-grade encryption and data loss prevention solutions to protect sensitive intellectual property and customer information. These organizations operate complex hybrid cloud environments and extensive supply chains that present large attack surfaces. They require centralized security management platforms that provide visibility across global operations. The cost of a single breach for a large enterprise can exceed millions of dollars in fines and recovery costs, justifying heavy investment in preventive measures. Large firms also drive innovation by piloting advanced technologies such as zero trust architecture and behavioral analytics. Their procurement power influences vendor strategies and product development.
The small and medium-sized enterprises segment is likely to register the fastest CAGR of 11.2% from 2026 to 2034; they become increasingly targeted by ransomware gangs and automated attack scripts that exploit their limited defenses. As per the study, ransomware attacks against SMEs in Asia Pacific have surged by 60% in the last year, as attackers perceive them as soft targets with weaker security postures and lower resistance to paying ransoms. Small businesses in the region do not have dedicated IT security staff, making them highly vulnerable to phishing and social engineering attacks that serve as entry points for larger network compromises. This rising threat landscape forces SMEs to abandon the misconception that they are too small to be targeted. The financial impact of a single attack can be catastrophic, leading to business closure. The availability of subscription-based security models lowers the barrier to entry. Awareness campaigns by governments and industry bodies further educate SME owners.
By End-User Insights
The IT and Telecom sector accounted for 34.6% of the Asia Pacific Cybersecurity Market share in 2025 due to its role as the backbone of digital connectivity and the massive volume of sensitive data it processes and transmits. The mobile data traffic in Asia Pacific has grown by 30% annually, requiring telecom operators to secure extensive 5G networks and Internet of Things connections against sophisticated interception and denial-of-service attacks. Regulatory requirements for lawful intercept and data retention add layers of complexity to security architectures. The transition to software-defined networking introduces new vulnerabilities that require specialized protection. Telecom operators also provide security services to their enterprise customers, creating a dual revenue stream.
The healthcare segment is expected to grow at the fastest CAGR of 9.8% from 2026 to 2034 due to the rapid digitization of patient records and the proliferation of connected medical devices that create new vulnerabilities. The cyberattacks on healthcare facilities in Asia Pacific have doubled in the past two years, with ransomware groups specifically targeting hospitals to exploit their critical need for uninterrupted service and willingness to pay ransoms. The adoption of electronic health records in the region has reached 60% in urban areas, creating large centralized databases that are attractive targets for identity theft and insurance fraud. Medical devices such as insulin pumps and pacemakers are increasingly connected to hospital networks, requiring specialized endpoint protection to ensure patient safety. The sensitivity of health data mandates strict compliance with privacy laws, driving investment in encryption and access management. The rise of telemedicine expands the attack surface to include patient home networks. Healthcare providers are recognizing that cybersecurity is a patient safety issue.
COUNTRY-LEVEL ANALYSIS
China Cybersecurity Market Analysis
China was the largest, holding 45.2% of the Asia Pacific Cybersecurity Market share in 2025, with its massive digital economy and stringent national security laws. The implementation of the Data Security Law and Personal Information Protection Law has mandated strict data localization and security reviews for information infrastructure operators, driving billions of dollars in domestic cybersecurity investment. The government prioritizes self-reliance in cybersecurity technologies by reducing dependence on foreign vendors. This policy supports local champions in firewall and encryption markets. The rapid expansion of 5G networks creates new security challenges for industrial automation. State-owned enterprises lead in adopting advanced threat detection systems.
Japan Cybersecurity Market Analysis
Japan cybersecurity market was ranked second, holding 21.2% of the share in 2025, with high awareness and strong government support for cybersecurity resilience. Japanese manufacturers are leading the adoption of industrial cybersecurity standards to protect proprietary technology and maintain quality control in automated production lines. The aging population drives demand for secure healthcare IoT devices. Companies prioritize reliability and long-term vendor relationships. The market values certification and proven track records. Collaboration between public and private sectors is strong. Japan focuses on securing its supply chain against geopolitical threats. It invests heavily in research and development.
India Cybersecurity Market Analysis
India cybersecurity market growth is expected to grow rapidly with the rapid digitalization of government services and a booming IT services sector. As per the Indian Computer Emergency Response Team, cyber incidents in India have increased by 15% year over year, with the financial sector and e-commerce platforms being the most targeted, leading to increased demand for fraud detection and endpoint security solutions. According to the Ministry of Electronics and Information Technology, the Digital India initiative has brought over 800 million citizens online by creating a massive attack surface that requires scalable and affordable security infrastructure. The government promotes local manufacturing of security hardware. Startups are innovating in cloud security and AI-driven analytics. The IT services sector exports cybersecurity skills globally.
South Korea Cybersecurity Market Analysis
South Korea's cybersecurity market is likely to grow at the fastest CAGR from 2026 to 2034 with the highly connected society and frequent exposure to state-sponsored cyber threats. The National Intelligence Service reports that North Korean cyberattacks against South Korean financial and media institutions have intensified, requiring advanced threat intelligence and rapid response capabilities. The Ministry of Science and ICT states that South Korea has one of the highest broadband penetration rates globally, driving demand for secure smart city infrastructure and 5G network protection. The country invests heavily in quantum cryptography research. Gaming and entertainment industries are major targets for DDoS attacks. Companies prioritize real-time monitoring and automation. The government supports cybersecurity startups through incubators. The market is technologically sophisticated.
Australia Cybersecurity Market Analysis
Australia's cybersecurity market growth is likely to grow with strict regulatory compliance and high adoption of managed security services. The Office of the Australian Information Commissioner states that organizations must notify affected individuals and the regulator within 72 hours of a data breach, driving investment in incident response and forensic services. The mining and resources sector is a key target for espionage. Cloud security is a priority due to high cloud adoption. The market values transparency and accountability. Managed service providers thrive due to talent shortages. Government initiatives promote cyber hygiene.
New Zealand Cybersecurity Market Analysis
New Zealand cybersecurity market growth is driven by the strong focus on privacy and small business security. The New Zealand Government Communications Security Bureau reports that cyberattacks on local councils and health boards have increased significantly, leading to national strategies for enhancing public sector cybersecurity resilience. The strict privacy laws require organizations to implement robust data protection measures, fostering demand for encryption and access control solutions. The agricultural tech sector is emerging as a target. Trust and reputation are critical. The government provides resources for SMEs.
Thailand Cybersecurity Market Analysis
Thailand cybersecurity market growth is likely to grow with its digital economy roadmap and increasing internet penetration. The Thailand 4.0 initiative promotes smart industries requiring secure industrial Internet of Things solutions for manufacturing automation. E-commerce growth drives payment security needs. The tourism sector faces data privacy challenges. Local integrators play a key role. Government support is increasing.
COMPETITIVE LANDSCAPE
The competitive landscape of the Asia Pacific Cybersecurity Market is characterized by intense rivalry among global giants, regional specialists, and emerging local vendors who compete on technology innovation, price, and local support capabilities. Multinational corporations leverage their extensive product portfolios and global threat intelligence networks to offer comprehensive end-to-end security platforms. Regional players often gain traction by providing customized solutions that address specific local compliance requirements and language preferences at competitive price points. Price sensitivity in developing economies drives demand for cost-effective managed security services, rather than expensive hardware appliances. Strategic partnerships with local system integrators are crucial for reaching small and medium-sized enterprises in fragmented markets. Innovation in artificial intelligence and automation serves as a key differentiator for vendors seeking to address the talent shortage. Regulatory compliance requirements create barriers to entry for foreign vendors, favoring those with an established local presence.
KEY MARKET PLAYERS
The leading companies operating in the Asia Pacific cybersecurity market include:
- NEC Corporation
- Trend Micro Inc.
- Cisco Systems Inc.
- Kaspersky Labs
- Dell Technologies Inc.
- Check Point Software Technologies Ltd.
- Fortinet Inc.
- Palo Alto Networks Inc.
- IBM Corporation
- Imperva
- Proofpoint Inc.
TOP PLAYERS IN THE MARKET
- Palo Alto Networks Inc. maintains a strong presence in the Asia Pacific Cybersecurity Market by providing comprehensive platform-based security solutions that integrate network, cloud, and endpoint protection. The company focuses on delivering zero trust architecture capabilities to help organizations secure their digital transformation initiatives across the region. Recent actions include expanding its threat intelligence operations in Singapore and Japan to provide localized insights into regional cyber threats. Palo Alto Networks actively partners with local managed service providers to extend its reach into small and medium-sized enterprises. The company invests heavily in artificial intelligence-driven security automation to reduce response times for customers. Its commitment to developer security is supported by Code Security offerings that address the growing need for application protection.
- Fortinet Inc contributes significantly to the Asia Pacific Cybersecurity Market through its broad integrated and automated Security Fabric architecture that connects security tools across the entire digital attack surface. The company leverages its proprietary FortiASIC chips to deliver high-performance security appliances that are cost-effective for diverse areas. Recent initiatives involve strengthening its partner ecosystem in Southeast Asia and India to drive adoption of its secure SD-WAN and SASE solutions. Fortinet actively participates in national cybersecurity drills and collaborates with governments to enhance critical infrastructure protection. The company expands its training programs through the Network Security Expert certification to address the regional skills gap. Its focus is on operational technology security that supports industrial digitization efforts in manufacturing hubs.
- Trend Micro Incorporated plays a pivotal role in the Asia Pacific Cybersecurity Market by offering hybrid cloud security and network defense solutions tailored to the specific needs of regional enterprises. Headquartered in Japan, the company has deep roots in the region and understands local business cultures and threat landscapes. Recent actions include enhancing its XDR capabilities with advanced AI analytics to detect sophisticated ransomware and supply chain attacks. Trend Micro actively collaborates with major cloud providers in the region to offer seamless security integration for hybrid environments. The company strengthens its partnerships with telecommunications operators to deliver managed detection and response services.
TOP STRATEGIES USED BY KEY MARKET PARTICIPANTS
Key players in the Asia Pacific Cybersecurity Market primarily focus on establishing strong local partnerships and channel ecosystems to navigate diverse regulatory landscapes and cultural nuances. Companies invest heavily in localized research and development centers to create solutions that address region-specific threats such as mobile malware and financial fraud. Strategic alliances with telecommunications providers and cloud hyperscalers enable integrated security offerings that simplify deployment for enterprise customers. Talent development initiatives, including certification programs and university collaborations, aim to mitigate the severe skills shortage in the region. Mergers and acquisitions are utilized to acquire niche technologies in areas like cloud security and artificial intelligence. Compliance with local data sovereignty laws drives the establishment of local data centers and support teams.
MARKET SEGMENTATION
This research report on the Asia Pacific cybersecurity market has been segmented and sub-segmented into the following categories.
By Component
-
Solutions
-
Services
By Deployment Type
-
Cloud
-
On-Premises
By Enterprise
-
Large
-
SMEs
By End-User
-
Aerospace & Defense
-
Healthcare
-
IT & Telecom
-
Energy
-
Manufacturing
By Region
-
India
-
China
-
Japan
-
South Korea
-
Australia
-
New Zealand
-
Thailand
-
Malaysia
-
Vietnam
-
Philippines
-
Indonesia
-
Singapore
-
Rest of Asia Pacific