- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$1.05 BnMarket Estimate, 2026
$1.12 BnMarket Forecast, 2034
$1.91 BnCAGR, 2026–2034
6.89%Executive Summary: Europe Medical Image Analysis Software Market
- Market Scope: Comprehensive market analysis of the European medical image analysis software industry covering image types, imaging technologies, application verticals, end-user settings, and regional leadership frameworks.
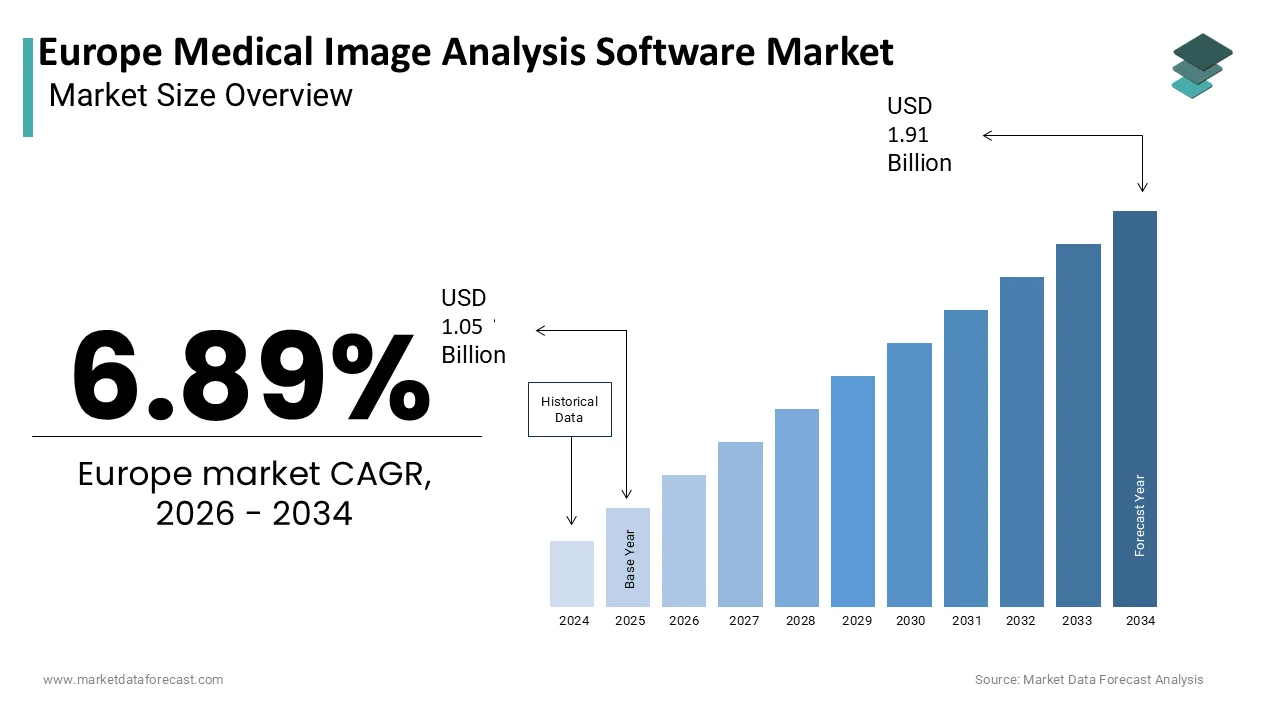
- Market Valuation: Valued at USD 1.05 billion (2025), estimated at USD 1.12 billion (2026), and projected to reach USD 1.91 billion by 2034, registering a robust CAGR of 6.89% (2026–2034).
- Primary Growth Drivers: Accelerated integration of artificial intelligence in radiological workflows to address radiologist shortages, expansion of cross-border diagnostic collaboration networks, and the rising adoption of federated learning for privacy-compliant algorithm development.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (2025 Position) | Fastest-Growing Segment |
|---|---|---|
| By Image Type | 3D imaging (largest segment holding 45.8% market share, widely used in tumor volumetry and surgical planning) | 4D imaging (projected to grow at a CAGR of 19.3% driven by functional cardiology and prenatal diagnostics) |
| By Imaging Technology | Magnetic resonance imaging (MRI) (prominent share supported by quantitative protocols for multiple sclerosis and dementia) | Ultrasound (expected to register a CAGR of 17.8% due to point-of-care portability and telemedicine integration) |
| By Application | Oncology (accounted for 27.3% share in 2025, driven by quantitative imaging biomarkers and radiomics) | Neurology (growing at a CAGR of 21.1% fueled by early dementia diagnosis and pan-European research networks) |
| By End User | Hospitals (dominated market share via integration into enterprise imaging platforms and electronic health records) | Diagnostic centres (expected to grow at a CAGR of 16.5% driven by cloud-native teleradiology solutions) |
| By Region / Country | Germany (largest contributor holding 44.8% share, backed by advanced medtech infrastructure and digital health policies) | France (second position with an 11.2% share, driven by centralized healthcare planning and AI strategies) |
Major Market Players & Market Structure
Market Structure: Highly competitive landscape featuring a dynamic interplay between established medical technology corporations and agile AI startups competing on EU Medical Device Regulation compliance, cloud readiness, interoperability, and clinical validation.
Key Companies: Agfa HealthCare, Medviso AB, Aquilab, Bruker Corporation, Carestream Health, Inc., Esaote S.p.A., GE HealthCare, Spacelabs Healthcare, Merge Healthcare Inc., Xinapse Systems Ltd., MIM Software Inc., Philips Healthcare, Clarion Technologies, Siemens Healthineers, and Toshiba Medical Systems Corporation.
Europe Medical Image Analysis Software Market Size
The Europe Medical Image Analysis Software Market is projected to grow from USD 1.05 billion in 2025 to USD 1.12 billion in 2026 and reach USD 1.91 billion by 2034, registering a CAGR of 6.89% during the forecast period from 2026 to 2034.
Medical image analysis software comprises specialized computational tools that enable the interpretation, enhancement, segmentation, and quantification of diagnostic images generated through modalities such as magnetic resonance imaging, computed tomography, ultrasound, and X-ray. These solutions support radiologists and clinicians by automating pattern recognition, reducing diagnostic variability, and accelerating decision-making. The European landscape for such software has evolved rapidly due to the convergence of artificial intelligence, cloud computing, and regulatory frameworks like the European Union Medical Device Regulation. This widespread adoption of digital imaging creates a fertile ground for integrating intelligent analysis software, especially as healthcare systems strive to manage increasing patient loads without proportional increases in specialist staffing.
MARKET DRIVERS
Accelerated Integration of Artificial Intelligence in Radiological Workflows
Artificial intelligence has transitioned from experimental to operational within European radiology departments, fundamentally transforming how medical image analysis software is deployed and valued. The European Society of Radiology reported in early 2025 that 67% of tier one hospitals in Germany, France, and the Netherlands had implemented at least one artificial intelligence-enabled image analysis tool in routine diagnostic pathways, particularly for neuroimaging and thoracic applications. This integration is primarily driven by a persistent shortage of radiologists, with the European Commission estimating a deficit of over 5000 full time equivalent radiologists across the European Union by 2025. Such workforce constraints create urgent demand for software that can triage studies, flag critical findings, and reduce interpretation time. Moreover, regulatory clarity under the European Union Medical Device Regulation has enabled faster market access for software classified as medical devices, with over 120 artificial intelligence-based imaging solutions certified under the new framework by mid-2024, according to the study. These developments collectively reinforce artificial intelligence not as an ancillary feature but as a core functional requirement in next-generation medical image analysis platforms across Europe.
Expansion of Cross-Border Diagnostic Collaboration Networks
The proliferation of transnational diagnostic networks for standardized and interoperable medical image analysis software is accelerating the growth of the Europe medical image analysis software market. As per the European Health Imaging Initiative, by 2024, more than 40% ofuniversity-affiliatedd hospitals in the European Economic Area participated in at least one cross-border diagnostic imaging consortium focused on rare diseases or oncology. These collaborations necessitate consistent analytical outputs irrespective of geographic origin, compelling institutions to adopt vendor-neutral and algorithmically transparent software platforms. The European Reference Networks, established under the European Union’s cross-border healthcare directive, further catalyze this trend, with neurological and pediatric oncology networks alone generating an estimated 8000 shared image datasets annually that demand uniform analytical protocols. Additionally, the General Data Protection Regulation has spurred development of federated learning systems, where image analysis software trains on distributed datasets without transferring patient data, thereby preserving compliance while enhancing model robustness.
MARKET RESTRAINTS
Stringent and Evolving Regulatory Classification Under the Medical Device Regulation
The European Union Medical Device Regulation has introduced significant complexity in the certification and maintenance of medical image analysis software, which is inhibiting the growth of the Europe medical image analysis software market. Unlike previous directives, the regulation mandates rigorous clinical evidence, post-market surveillance, and unique device identification for software classified as a medical device. This prolonged timeline delays market entry and increases compliance costs, particularly for small and medium-sized enterprises that constitute nearly 60% of Europe’s health technology software developers, according to the study. Furthermore, the regulation requires continuous performance monitoring, compelling vendors to invest in real-world data infrastructure that many lack. For example, a 2024 audit by the German Federal Institute for Drugs and Medical Devices found that 44% of approved image analysis software failed to submit required post-market performance updates within mandated deadlines, risking non-compliance penalties. These structural and procedural hurdles deter innovation velocity and reduce competitive diversity, thereby constraining market expansion despite strong clinical demand.
Persistent Interoperability Gaps Across Legacy Hospital Imaging Systems
The medical image analysis software deployment is significantly hindered by the fragmented and heterogeneous nature of existing hospital imaging infrastructures. The persistent interoperability gaps across legacy hospital imaging systems are also hampering the growth of the Europe medical image analysis software market. According to a 2024 survey by the European Society of Medical Imaging Informatics, 71% of European hospitals operate imaging equipment from three or more different manufacturers, each using proprietary data formats and communication protocols that impede seamless integration with third-party analytical tools. This lack of standardization forces software vendors to develop multiple integration modules, escalating development costs and delaying implementation. Moreover, Health Level Seven International adoption remains inconsistent, with only 43% of European radiology departments fully compliant with current integration profiles, as documented by the Integrating the Healthcare Enterprise initiative in 2024. These interoperability constraints not only increase total cost of ownership for healthcare providers but also limit the scalability of advanced analytical solutions, especially in rural and under-resourced settings where budgetary flexibility is minimal.
MARKET OPPORTUNITIES
Rising Adoption of Federated Learning for Privacy-Compliant Algorithm Development
Federated learning, by aligning artificial intelligence innovation with stringent data protection norms, is set to create new opportunities for the growth of the Europe medical image analysis market. Unlike traditional centralized training models, federated learning allows algorithms to learn from distributed datasets without transferring raw patient images, thereby complying with the General Data Protection Regulation. As per the European Institute for Biomedical Imaging Research, the number of active federated learning consortia in Europe grew from 9 in 2021 to 42 in 2024, encompassing over 300 hospitals collaborating on oncology, neurology, and cardiovascular imaging tasks. This decentralized approach reduces legal and operational barriers to data sharing, enabling vendors to develop more robust and generalizable models without violating national or institutional data governance policies. Additionally, the European Health Data Space framework, expected to be fully operational by 2026, explicitly endorses federated analytics as a preferred method for cross-border health research, signaling long-term institutional support. For software developers, this paradigm lowers entry costs for multi-center validation and accelerates regulatory approval by providing diverse, real-world performance evidence, positioning federated learning as a cornerstone of next-generation medical image analysis in Europe.
Expansion of Image-Guided Minimally Invasive Therapies in Public Healthcare Systems
The increasing adoption of image-guided minimally invasive procedures across European public hospitals is creating substantial demand for real-time medical image analysis software. The expansion of image-guided minimally invasive therapies in public healthcare systems is also fueling the growth of the Europe medical image analysis software market. According to the European Association of Percutaneous Cardiovascular Interventions, over 2.1 million image-guided vascular interventions were performed in the European Union in 2024, representing a 12% annual increase since 2021. These procedures rely heavily on intraoperative imaging analytics for navigation, lesion quantification, and procedural verification. This shift is further reinforced by clinical guidelines from the European Society of Minimally Invasive Neurological Therapy, which now recommend automated volumetric analysis for all stereotactic procedures. The emergence of therapeutic demand, public funding, and clinical endorsement creates a fertile niche for specialized image analysis software that delivers actionable insights during live interventions, distinguishing this segment from purely diagnostic applications and opening new revenue channels for vendors.
MARKET CHALLENGES
Fragmented Reimbursement Policies for Software as a Medical Service
The absence of standardized reimbursement codes for algorithmic interpretation services is a key challenge for the growth of the Europe medical image analysis software market. Unlike the United States, where Category III Current Procedural Terminology codes enable billing for specific artificial intelligence-assisted diagnostics, European countries lack harmonized payment mechanisms for software-derived clinical insights. As per the European Health Management Association, only 4 out of 27 European Union member states had established discrete reimbursement pathways for medical image analysis software by 2024, with the remaining relying on bundled imaging procedure payments that offer no incremental compensation for analytical enhancements. This gap disincentivizes hospital adoption, as administrators cannot recover the software’s added value through existing diagnostic tariffs. Furthermore, the European Commission’s 2024 Health Technology Assessment Network report highlighted that inconsistent national valuation criteria delay cross-border scalability, forcing vendors to navigate 20-plus distinct health economic frameworks.
Algorithmic Bias and Generalizability Gaps in Diverse European Populations
Medical image analysis software in Europe faces growing scrutiny over performance disparities across demographic and geographic subgroups, undermining trust and adoption. Algorithmic bias and generalizability gaps in diverse European populations also inhibit the growth of the Europe medical imaging analysis software market. As per a 2024 audit by the European Institute for Artificial Intelligence in Medicine, 61% of commercially available chest X-ray analysis algorithms demonstrated statistically significant performance degradation when applied to imaging data from Southern and Eastern European populations compared to training data predominantly sourced from Northern Europe. The consequences are clinically meaningful; for instance, a mammography analysis tool evaluated in Portugal showed a 14% lower sensitivity in dense breast tissue common among Mediterranean women, as documented by the Portuguese Oncology Institute in 2024. Regulatory bodies are responding, with the French National Authority for Health now requiring subgroup performance reporting for all Class IIb software submissions, ns but this adds validation complexity and cost.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Covered | By Image Type, Imaging Technology, Application End User, and Region. |
| Various Analyses Covered | Global, Regional, and Country-Level Analysis, Segment-Level Analysis, Drivers, Restraints, Opportunities, Challenges; PESTLE Analysis; Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Countries Covered | UK, France, Spain, Germany, Italy, Russia, Sweden, Denmark, Switzerland, Netherlands, Turkey, Czech Republic, Rest of Europe |
| Market Leaders Profiled | Agfa HealthCare, Medviso AB, Aquilab, Bruker Corporation, Carestream Health, Inc., Esaote S.p.A., GE HealthCare, Spacelabs Healthcare, Merge Healthcare Inc., Xinapse Systems Ltd., MIM Software Inc., Philips Healthcare, Clarion Technologies, Siemens Healthineers, Toshiba Medical Systems Corporation. |
SEGMENTAL ANALYSIS
By Image Type Insights
The 3D imaging stems segment was the largest, holding 45.8% of the Europe medical image analysis software market. As per the European Society of Radiology, over 74% of oncology centers in Germany, France, and the Netherlands routinely use 3D reconstruction software for tumor volumetry and surgical planning as of 2024. This precision reduces interobserver variability, a long-standing challenge in 2D interpretation. Furthermore, the European Association of Neurological Surgeons reported that preoperative 3D models shortened surgical planning time by an average of 37 minutes per case in 2023. The adoption of 3D imaging is further amplified by its seamless integration into hybrid operating rooms and interventional suites. According to the European Association of Percutaneous Cardiovascular Interventions, 55% of catheterization labs in Western Europe upgraded to 3D fusion imaging platforms between 2022 and 2024 by enabling real-time overlay of pre-procedural computed tomography scans onto live fluoroscopy. This convergence demands sophisticated 3D analysis software capable of registration, deformation correction, and real-time rendering. Additionally, the European Health Imaging Initiative noted that new diagnostic imaging tenders issued by European public hospitals in 2024 explicitly required vvendor-neutral3D analysis interoperability.
The 4D imaging segment is likely to grow at the fastest CAGR of 19.3% from 2026 to 2034, according to the European Society of Medical Imaging Informatics. Its rapid expansion is driven by rising demand for functional assessment in cardiology and prenatal diagnostics. In congenital heart disease screening, 4D ultrasound enables real-time visualization of foetal cardiac valves and blood flow dynamics, a capability now recommended in updated 2024 guidelines from the European Reference Network for Rare Heart Defects. This shift toward non-invasive functional phenotyping underpins the segment’s accelerated adoption trajectory. The growth of 4D imaging is further propelled by breakthroughs in computational efficiency that make dynamic analysis clinically feasible. Historically, limited by processing latency, 4D reconstruction now benefits from cloud-accelerated pipelines and edge computing integration. This speed enables same-session clinical decision-making, a prerequisite for routine use. Moreover, the European Health Data Space pilot in the Netherlands demonstrated in early 2025 that 4D datasets could be securely streamed and analyzed across institutions without local high-performance computing, broadening access beyond academic hubs.
By Imaging Technology Insights
The magnetic resonance imaging segment held a prominent share of the Europe medical imaging analysis software market. According to the European Academy of Neurology, over 88% of multiple sclerosis monitoring protocols across EU member states in 2024 mandated quantitative MRI analysis for lesion load tracking, a task impossible with 2D visual assessment alone. Unlike other modalities, magnetic resonance imaging benefits from harmonized European protocols that facilitate software standardization. This standardization reduces validation burden for software developers and accelerates clinical integration. Furthermore, Germany’s Federal Joint Committee included MRI-based volumetric hippocampal analysis in its 2024 national dementia diagnostic pathway by making it reimbursable under statutory health insurance. Such regulatory and payment alignment creates a virtuous cycle where clinical utility is recognized, reimbursed, and scaled, setting MRI apart from other imaging technologies in the software ecosystem.
The ultrasound segment is expected to register the fastest CAGR of 17.8% from 2026 to 2034 with its portability, expected effectiveness, and rapid adoption in point-of-care scenarios. These devices generate vast volumes of images that require a point-of-care analysis to maintain diagnostic consistency, especially when operated by non-radiologists. In response, vendors like Butterfly iQ and GE Healthcare launched European Union Medical Device Regulation-compliant analysis apps for lung sliding detection and bladder volume estimation, with over 12 000 European licenses issued in 2024 according to company disclosures. Ultrasound’s growth is also fueled by its compatibility with telemedicine infrastructures, a priority under the European Digital Health Action Plan. The Nordic Telehealth Consortium reported in 2024 that 4D ultrasound clips from ambulances in Denmark and Sweden were analyzed in real time by central hubs using cloud-based software, reducing stroke misclassification by 19%. Similarly, France’s 15 Samu emergency medical services adopted AI-enhanced cardiac ultrasound analysis in 2024 to triage patients with suspected pulmonary embolism during transport. These use cases demand lightweight, network-enabled analysis software that can operate on mobile devices, a niche where ultrasound excels over bulkier modalities.
By Application Insights
The oncology segment accounted for 27.3% of the Europe medical image analysis software market share in 2025. Oncology’s dominance is anchored in the European Society for Medical Oncology’s 2023 guidelines, which now require quantitative imaging biomarkers for solid tumor response evaluation in all phase III clinical trials conducted in Europe. Beyond response assessment, oncology drives software demand through radiomics, where the high-throughput extraction of imaging features is used to predict genomics, prognosis, and therapy resistance. The European Radiomics Society reported in 2024 that over 200 radiomics-based clinical decision support tools were under validation in European hospitals, with lung, prostate, and breast cancer as primary targets. The European Union’s Innovative Health Initiative has committed 200 million euros through 2027 to scale such tools, requiring vendors to embed radiomics engines into analysis software.
The neurology segment is likely to grow at the fastest CAGR of 21.1% during the forecast period, with Europe’s aging population and the urgent need for early dementia diagnosis. France’s national memory clinics network reported a 65% increase in software-assisted MRI analyses between 2022 and 2024. Neurology’s growth is uniquely enabled by pan-European research infrastructures that generate large-scale, annotated datasets. The European Reference Network for Rare Neurological Diseases coordinates over 150 expert centers and produced 12,000 standardized imaging cases in 2024 alone, all requiring uniform analysis protocols. Additionally, the EU-funded AMYPAD project, which concluded in 2024, established amyloid PET and MRI analysis standards now adopted by 14 countries. Such initiatives reduce algorithmic fragmentation and create demand for interoperable software that can operate across borders. This ecosystem of collaboration, standardization, and policy alignment accelerates software penetration at a rate exceeding other clinical domains.
By End User Insights
The hospitals segment accounted for a dominant share of the Europe medical image analysis market in 2025. Hospitals command the largest share because medical image analysis software is increasingly embedded within enterprise imaging platforms and electronic health records, creating institutional lock-in. As per the European Society of Medical Imaging Informatics, 68% of European university hospitals had unified imaging and analytics workflows by 2024, eliminating siloed analysis tools. This integration is mandated under national digital health strategies; for example, the United Kingdom’s National Health Service required all acute trusts to achieve Level 6 on the Healthcare Information and Management Systems Society Analytics Maturity Model by 2025, a benchmark that includes embedded diagnostic decision support. These systemic investments transform software from an optional add-on into a core component of hospital digital infrastructure, ensuring sustained dominance. Hospitals benefit from centralized procurement power and access to public funding that smaller entities lack.
The diagnostic centres segment is expected to grow at the fastest CAGR of 16.5% from 2026 to 2034. Diagnostic centres increasingly outsource interpretation to tele-radiology providers, necessitating cloud native analysis software that integrates across distributed workflows. Companies like Sectra and Agfa launched subscription-based software models in 2024 tailored to this segment, with over 800 diagnostic centre contracts signed in the first half of 2025. These flexible, opex-friendly solutions lower entry barriers and enable rapid scaling, key advantages for a segment characterized by small size and high competition.
COUNTRY LEVEL ANALYSIS
Germany Medical Image Analysis Software Market Analysis
Germany was the largest contributor to the Europe medical image analysis software market, holding 44.8% of the Europe medical image analysis software share in 2025, with its advanced healthcare infrastructure, strong medtech industry, and proactive digital health policies. The country’s hospital landscape includes over 1,900 facilities equipped with Picture Archiving and Communication Systems, as per the study. A pivotal factor is the nationwide rollout of the electronic patient record, which mandates integration of diagnostic decision support tools by 2026 under the Digital Healthcare Act. In 2024 alone, Germany’s Innovation Fund allocated 87 million euros to projects embedding AI analysis into routine radiology workflows, with 41 hospitals participating. The Federal Joint Committee’s inclusion of quantitative imaging in 12 national disease management programs further institutionalizes software use. Moreover, Germany hosts leading software developers like Siemens Healthineers and Brainlab, whose European Union Medical Device Regulation certified platforms are deployed in 35 countries.
France Medical Image Analysis Software Market Analysis
France medical image analysis software market held the second position, holding an 11.2% share in 2025, with its centralized healthcare planning and aggressive AI strategy. The French National Health Insurance Fund’s 2024 digital transformation budget included 180 million euros forAI-enabledd diagnostic imaging, targeting 100% coverage of university hospitals by 2026. Additionally, France’s Artificial Intelligence for Humanity plan designated medical imaging as a priority sector, resulting in 28 public-private AI health projects launched in 2023, six of which focused on image analysis. The country also leads in federated learning adoption, where the Health Data Hub facilitated cross-hospital algorithm training across 15 regions in 2024 without data centralization.
COMPETITIVE LANDSCAPE
The competition in the Europe Medical Image Analysis Software Market is characterized by a dynamic interplay between established medical technology corporations and agile AI-focused startups. Incumbents leverage their deep integration with imaging hardware and hospital information systems to embed analytics into routine clinical workflows. Meanwhile, specialized software vendors differentiate through modality-specific or disease-focused algorithms, often developed in close collaboration with European reference networks and research consortia. Regulatory barriers under the European Union Medical Device Regulation have raised the entry threshold,d favoring companies with robust quality management systems and clinical validation capabilities. Competition is further shaped by national digital health strategies which influence procurement priorities and reimbursement frameworks. Vendors increasingly compete on interoperability, cloud readiness,s, and compliance with data governance standards rather than algorithmic performance alone.
KEY MARKET PLAYERS
Some of the companies that are playing a dominating role in the Europe Medical Image Analysis Software Market include:
- Agfa HealthCare
- Medviso AB
- Aquilab
- Bruker Corporation
- Carestream Health, Inc.
- Esaote S.p.A.
- GE HealthCare
- Spacelabs Healthcare
- Merge Healthcare Inc.
- Xinapse Systems Ltd.
- MIM Software Inc.
- Philips Healthcare
- Clarion Technologies
- Siemens Healthineers
- Toshiba Medical Systems Corporation
TOP LEADING PLAYERS IN THE MARKET
- Siemens Healthineers plays a pivotal role in the Europe Medical Image Analysis Software Market through its comprehensive portfolio of AI-powered imaging solutions integrated across modalities. The company actively contributes to the global market by embedding advanced analytics into its syngo platform, enabling radiologists to perform quantitative assessments in oncology, neurology,y and cardiology. In recent years, Siemens Healthineers has intensified its focus on regulatory compliance and interoperability under the European Union Medical Device Regulation. The company also expanded its team of clinical AI specialists in Europe to support hospital implementation and real-world validation studies, strengthening its clinical relevance and adoption footprint across the region.
- Philips Healthcare is a key innovator in medical image analysis software with a strong emphasis on workflow integration and diagnostic confidence. Its IntelliSpace platform serves as a cornerstone for radiology departments across Europe,e offering advanced visualization and AI-driven decision support. Globally, Philips reinforces its leadership by collaborating with academic medical centers toco-developp and validate imaging algorithms. It also partnered with multiple European teleradiology networks to deploy its software in distributed reading environments. These initiatives reflect PPhilips'commitment to scalable, secure,e and clinically actionable analytics that align with evolving European healthcare delivery models.
- GE Healthcare significantly influences the Europe Medical Image Analysis Software Market through its Edison platform, rm which hosts a growing ecosystem of AI applications for diagnostic imaging. The company supports global radiology workflows by enabling seamless deployment of third-party and proprietary algorithms within existing imaging infrastructures. In Europe, GE Healthcare has prioritized regulatory certification and clinical utility studies to meet stringent requirements under the European Union Medical Device Regulation. The company also launched a dedicated AI integration service for European hospitals to accelerate adoption. These actions demonstrate GE Healthcare’s strategy of combining technological openness with clinical rigor to expand its software footprint across diverse healthcare settings.
TOP STRATEGIES USED BY THE KEY MARKET PARTICIPANTS
Key players in the Europe Medical Image Analysis Software Market employ several strategic approaches to maintain competitive advantage. They prioritize regulatory compliance by securing European Union Medical Device Regulation certification for AI-based applications. Companies heavily invest in clinical validation through partnerships with academic hospitals to generate real-world evidence. Cloud native architecture and vendor-neutral integration are emphasized to ensure interoperability with legacy Picture Archiving and Communication Systems. Firms actively pursue federated learning collaborations to train algorithms across borders without violating data privacy laws. Additionally, they offer flexible deployment models, including subscription-based and pay-per-use options to cater to diagnostic centres and smaller hospitals. Strategic acquisitions of niche AI startups also feature prominently to expand algorithm portfolios. Continuous enhancement of user interfaces and workflow efficiency remains central to product development.
MARKET SEGMENTATION
This research report on the Europe Medical Image Analysis Software Market is segmented and sub-segmented into the following categories.
By Image Type
- 2D Imaging
- 3D Imaging
- 4D Imaging
By Imaging Technology
- X-Ray
- Computed Tomography
- Positron Emission Tomography
- Single Photon Emission Computed Tomography
- Magnetic Resonance Imaging
- Ultrasound
- Radiographic Imaging
By Application
- Cardiovascular
- Neurology
- Dental
- Urology
- Orthopaedic
- Oncology
- Obstetrics
- Gynaecology
- Mammography
By End-User
- Hospitals
- Research Centres
- Diagnostic Centres
By Country
- UK
- France
- Spain
- Germany
- Italy
- Russia
- Sweden
- Denmark
- Switzerland
- Netherlands
- Turkey
- Czech Republic
- Rest of Europe