- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$2.89 BnMarket Estimate, 2026
$3.11 BnMarket Forecast, 2034
$5.65 BnCAGR, 2026–2034
7.76%Executive Summary: Europe Veterinary Diagnostics Market
- Market Scope: Comprehensive market evaluation of the European veterinary diagnostics ecosystem, analyzing product categories, companion and food-producing animal segments, and country-level adoption frameworks.
- Market Valuation: Valued at USD 2.89 billion in 2025, estimated at USD 3.11 billion in 2026, and projected to reach USD 5.65 billion by 2034, registering a solid CAGR of 7.76% (2026–2034).
- Primary Growth Drivers: Rising prevalence of zoonotic and infectious animal diseases, expanding pet ownership and per capita expenditure on companion animals, strict European regulations regarding food safety and animal welfare, and growing demand for animal protein.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (Base Position) | Fastest-Growing Segment (2026–2034) |
|---|---|---|
| By Product Type | Immunodiagnostics & Clinical Chemistry (dominate routine testing workflows and in-clinic analyzers) | Molecular Diagnostics (experiencing high expansion driven by demand for precise pathogen identification and genetic screening) |
| By Animal | Companion Animals (canine and feline diagnostics account for the largest revenue share due to high pet insurance adoption and care spending) | Food-Producing / Livestock Animals (growing steadily via stringent government disease surveillance and food safety regulations) |
| By Country / Region | United Kingdom & Germany (lead the European market share through extensive pet care expenditure and mature livestock health infrastructure) | France, Italy, Spain, and Rest of Europe (expanding rapidly via rising animal healthcare awareness and veterinary clinic networks) |
Major Market Players & Market Structure
Market Structure: A competitive and highly regulated medical technology landscape featuring major global diagnostics manufacturers, specialized animal health corporations, and established veterinary reference laboratories.
Key Companies: IDEXX Laboratories Inc., VCA Inc., Heska Corporation, Abaxis Inc., VIRBAC, Life Technologies Corporation, Bio-Rad Laboratories Inc., Prionics AG, and Pfizer Inc.
 Download Free Sample Report
Europe Veterinary Diagnostics Market Size
The Europe veterinary diagnostics market size was valued at USD 2.89 billion in 2025 and is anticipated to reach USD 3.11 billion in 2026 from USD 5.65 billion by 2034, growing at a CAGR of 7.76% during the forecast period from 2026 to 2034.
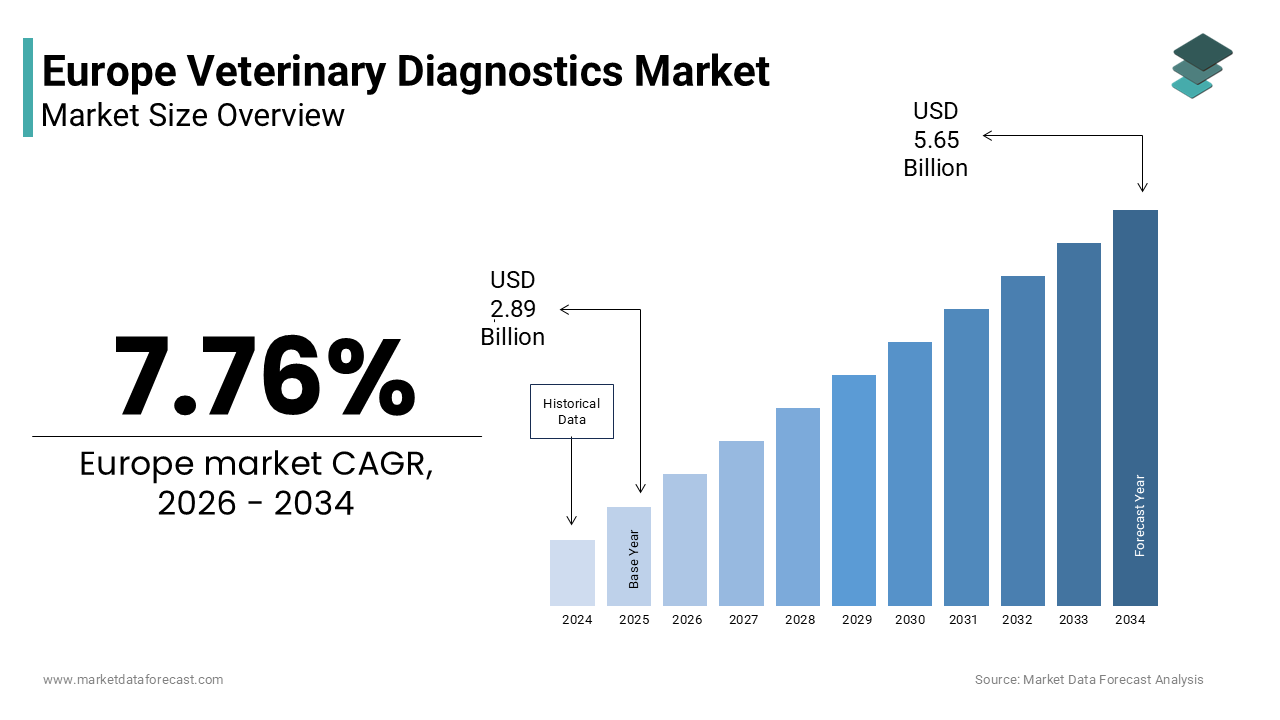
The Europe veterinary diagnostics market encompasses a sophisticated array of tools and technologies designed to detect diseases monitor health status and guide treatment decisions for companion and livestock animals. This sector includes clinical chemistry hematology immunodiagnostics and molecular diagnostics that are essential for accurate disease management. According to FEDIAF, the latest European pet population data covering 2023 recorded 299 million pets in European households and 139 million households owning at least one pet. These substantial animal populations require regular veterinary care and support continued demand for diagnostic services. According to the World Organisation for Animal Health, around 60% of known human infectious diseases originate in animals and 75% of emerging infectious human diseases have an animal origin, necessitating robust diagnostic surveillance in Europe. These epidemiological realities directly drive the demand for precise and rapid diagnostic solutions to prevent cross species transmission. Regulatory frameworks such as the EU Animal Health Law establish requirements for disease prevention early detection notification surveillance and control of transmissible animal diseases. The increasing prevalence of chronic conditions in pets such as diabetes and renal disease further amplifies the need for continuous monitoring. Veterinary professionals rely on advanced diagnostics to differentiate between similar clinical presentations improving patient outcomes. This market represents a critical component of animal health infrastructure driven by the imperative to ensure food safety and enhance the well-being of companion animals across diverse healthcare settings in the region.
MARKET DRIVERS
Rising Prevalence of Zoonotic Diseases Driving Surveillance Demand
The escalating threat of zoonotic diseases is a key factor propelling the Europe veterinary diagnostics market expansion by creating an urgent need for robust surveillance and early detection systems. According to the European Centre for Disease Prevention and Control, 19 countries in Europe reported 1,436 locally acquired human West Nile virus cases in 2024, while veterinary surveillance recorded 494 outbreaks among equids and 447 outbreaks among birds. This public health imperative directly stimulates demand for rapid diagnostic tests and serological assays in both wildlife and domestic animals. According to the World Health Organization, approximately 60% of known infectious diseases can be transmitted by animals and up to 75% of new or emerging infectious diseases have a zoonotic origin, highlighting the critical role of veterinary diagnostics in breaking the chain of transmission. These statistics demonstrate the direct link between animal health monitoring and human safety driving government investment in diagnostic infrastructure. Veterinary laboratories are expanding their capacity to handle high volumes of samples during outbreak scenarios. Regulatory bodies mandate strict reporting protocols for notifiable diseases ensuring consistent utilization of diagnostic services. Farmers and pet owners increasingly prioritize preventive testing to avoid costly treatments and potential quarantine measures. The integration of One Health initiatives further encourages collaboration between human and animal health sectors fostering shared diagnostic resources. This heightened awareness ensures sustained procurement of advanced diagnostic kits. The focus on biosecurity creates a stable foundation for market growth as stakeholders recognize the economic and health benefits of early detection.
Increasing Pet Humanization and Expenditure on Premium Care
The trend of pet humanization further boosts the Europe veterinary diagnostics market growth by driving higher expenditure on advanced medical care and preventive diagnostics for companion animals. According to FEDIAF, 139 million European households owned at least one pet based on 2023 data, providing a broad base for recurring veterinary services and preventive care. This emotional bond translates into a willingness to invest in sophisticated diagnostic procedures such as MRI CT scans and genetic testing. According to FEDIAF, European households contained 299 million pets in 2023, supporting continued demand for veterinary healthcare and diagnostic services. These financial trends enable clinics to adopt state of the art equipment that improves diagnostic accuracy. Pet insurance penetration is rising in countries like Sweden and the United Kingdom reducing out of pocket costs for owners and encouraging comprehensive health checks. Veterinarians are more likely to recommend advanced diagnostics when they know clients can afford them. The aging pet population requires frequent monitoring for chronic conditions further boosting demand for routine blood work and imaging. Manufacturers respond by developing user friendly point of care devices that deliver rapid results in clinical settings. This shift towards premium care ensures robust revenue generation for diagnostic providers. The emphasis on quality of life drives continuous innovation in non-invasive diagnostic technologies.
MARKET RESTRAINTS
High Cost of Advanced Diagnostic Equipment Limiting Adoption
Exorbitant costs associated with advanced diagnostic equipment hampers the veterinary diagnostics market growth in Europe by restricting access for small and medium sized veterinary practices. According to the Federation of Veterinarians of Europe, workforce and practice capacity constraints affect veterinary services across Europe, particularly in rural and remote areas, where limited resources can make access to advanced services more difficult. This financial barrier prevents widespread adoption of cutting edge technologies particularly in rural areas. According to published veterinary equipment and practice literature, advanced imaging systems such as MRI and CT require substantial capital investment and ongoing maintenance, creating a greater financial burden than routine laboratory analyzers. These constraints force clinics to rely on external reference laboratories which may delay diagnosis and increase logistical complexity. Small practices struggle to compete with large corporate chains that benefit from economies of scale and centralized diagnostic hubs. Reimbursement rates for diagnostic procedures often do not cover the full cost of equipment maintenance and upgrades. This affordability crisis suppresses market volume and slows the diffusion of innovative technologies. Manufacturers face challenges in pricing strategies that balance profitability with accessibility for smaller clients. The lack of flexible financing options exacerbates the inequality in diagnostic capabilities. Consequently the market fails to reach its full potential as economic barriers prevent widespread utilization of advanced diagnostic tools among vulnerable practice segments.
Stringent Regulatory Compliance Burdens Delaying Product Launches
Complex and rigorous regulatory frameworks are another significant impediment to the Europe veterinary diagnostics market growth by prolonging approval timelines and increasing compliance costs for manufacturers. According to the European Commission, Regulation EU 2016/429, known as the Animal Health Law, establishes a comprehensive framework for preventing and controlling transmissible animal diseases and includes requirements for early detection notification reporting surveillance eradication and disease control. This stringent scrutiny while ensuring safety creates a bottleneck that hinders rapid commercialization and limits patient access to innovative tests. According to the European Commission, the Animal Health Law has applied since 21 April 2021 and provides a common legal framework for animal disease prevention surveillance biosecurity traceability and control across the European Union. These divergent requirements force manufacturers to navigate a fragmented landscape increasing operational complexity and resource allocation. Small and medium enterprises often lack the financial capacity to meet these stringent demands reducing competition and innovation diversity. The lack of harmonized standards across member states means that a device approved in one country may require separate validation in another duplicating efforts and expenses. Regulatory uncertainty discourages foreign investment in local manufacturing facilities limiting technology transfer. Delays in approval also mean that veterinarians continue to use outdated tests without access to newer more effective interventions. The administrative burden diverts resources from research and development to compliance activities slowing the pace of innovation. This regulatory fragmentation acts as a significant impediment to market growth preventing the timely availability of advanced diagnostic solutions.
MARKET OPPORTUNITIES
Integration of Artificial Intelligence Enhancing Diagnostic Accuracy
The integration of artificial intelligence into diagnostic platforms is a significant opportunity for the Europe veterinary diagnostics market by enhancing accuracy and efficiency in image analysis. According to peer reviewed veterinary imaging research, artificial intelligence and machine learning are increasingly being evaluated for automated interpretation of radiographs ultrasound images CT scans and other veterinary diagnostic images. This capability can reduce diagnostic errors and enable faster decision making in emergency situations. According to the Federation of Veterinarians of Europe, digitalisation and artificial intelligence are among the major technological shifts expected to affect the veterinary profession during the coming years. These technological synergies create new value propositions for manufacturers who can offer smart diagnostic systems. Healthcare providers benefit from automated reporting features that streamline workflow and reduce administrative burdens. The ability to analyze large datasets helps identify patterns and predict disease outbreaks improving preventive care. Governments are supporting digital health initiatives providing grants for clinics adopting AI technologies. This supportive policy environment encourages collaboration between tech firms and veterinary device manufacturers accelerating product development. Patients benefit from more precise diagnoses leading to targeted treatments and better outcomes. The convergence of AI and diagnostics opens new revenue streams through software subscriptions and data analytics services. This opportunity transforms static diagnostic tools into dynamic decision support systems driving market expansion.
Expansion of Point of Care Testing Facilities Improving Accessibility
The rapid expansion of point of care testing facilities offers a substantial opportunity for the Europe veterinary diagnostics market by enabling immediate diagnosis and treatment at the clinic level. According to the European Commission, the EU Animal Health Law explicitly provides for diagnostic methods within animal disease surveillance and control frameworks, reinforcing the importance of timely diagnostic capacity. This shift supports the deployment of compact diagnostic devices that provide results within minutes rather than days. According to peer reviewed veterinary emergency and critical care literature, point of care testing can provide rapid information on blood gases electrolytes glucose lactate and other clinically relevant parameters, supporting quicker intervention for critically ill animals. These improvements drive demand from both urban and rural clinics seeking efficient diagnostic solutions. Manufacturers are developing handheld devices that are easy to use and require minimal training. Insurance providers are beginning to cover point of care tests recognizing their cost effectiveness in reducing follow up visits. The integration of cloud connectivity allows for remote consultation with specialists enhancing diagnostic confidence. This infrastructure growth lowers barriers to entry for innovative companies and encourages the development of portable diagnostic ecosystems. The synergy between speed and accuracy creates a scalable model for delivering high quality care. This opportunity drives market growth through enhanced operational efficiency and patient satisfaction.
MARKET CHALLENGES
Shortage of Skilled Veterinary Technicians Impeding Implementation
A critical shortage of trained veterinary technicians and pathologists is a significant challenge to the Europe veterinary diagnostics market by impeding the effective implementation and interpretation of complex diagnostic tests. According to the Federation of Veterinarians of Europe, around 330,000 veterinarians work in Europe and workforce shortages have expanded across almost all European countries and multiple areas of veterinary practice. This workforce gap directly restricts the number of procedures that can be performed safely and efficiently constraining market growth despite high demand. According to the Federation of Veterinarians of Europe, almost all member organizations report veterinary workforce shortages, particularly in rural and remote areas and in livestock veterinary practices. These disparities force pet owners to travel to urban centers increasing costs and logistical burdens that deter timely care. Training programs for veterinary diagnostics are limited in number and capacity resulting in a slow pipeline of qualified professionals. The complexity of modern diagnostic equipment requires specialized skills further straining existing human resources. Clinics struggle to retain skilled staff due to competitive salaries offered by corporate chains and other industries. The lack of standardized training curricula across countries leads to variability in test quality and interpretation. Manufacturers face difficulties in providing adequate technical support and training to understaffed facilities affecting device utilization. This human resource constraint acts as a bottleneck that prevents the scaling up of diagnostic services. Addressing this challenge requires significant investment in education which remains insufficient in many regions.
Fragmented Reimbursement Policies across Member States
Inconsistent reimbursement policies across European nations is further challenging the expansion of the Europe veterinary diagnostics market by creating uncertainty for providers and limiting patient access to advanced tests. According to the Federation of Veterinarians of Europe, veterinary workforce and service availability vary substantially across European countries and veterinary care remains subject to different national systems and economic conditions. This fragmentation discourages the adoption of expensive diagnostic procedures in markets with low insurance penetration. According to FEDIAF, pet ownership and related expenditure vary considerably across European countries, creating different levels of demand for veterinary services and advanced diagnostics. These disparities create unequal access to diagnostic services affecting market uniformity. Providers hesitate to invest in advanced equipment if they cannot guarantee reimbursement or client willingness to pay. The lack of harmonized pricing guidelines leads to wide variations in test costs confusing consumers. Insurance companies often exclude pre existing conditions or limit coverage for diagnostic imaging reducing utilization. This regulatory and financial inconsistency complicates market planning for global manufacturers. The absence of a unified European veterinary insurance framework hinders the development of standardized care pathways. This challenge acts as a persistent barrier to market efficiency limiting the potential for widespread adoption of premium diagnostic services.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 7.76% |
| Segments Covered | By Product, Animals and Region |
| Various Analyses Covered | Global, Regional & Country Level Analysis; Segment-Level Analysis; DROC, PESTLE Analysis; Porter’s Five Forces Analysis; Competitive Landscape; Analyst Overview of Investment Opportunities |
| Regions Covered | United Kingdom, France, Spain, Germany, Italy, Russia, Sweden, Denmark, Switzerland, the Netherlands, Turkey, and the Czech Republic |
| Market Leaders Profiled | VCA Inc., Heska Corporation, Abaxis Inc., VIRBAC, IDEXX Laboratories Inc., Life Technologies Corporation, Bio-Rad Laboratories Inc., Prionics AG, and Pfizer |
SEGMENTAL ANALYSIS
By Product Type Insights
The clinical biochemistry segment dominated the market and accounted for the largest share of 41.88% of the European market in 2025. The ability to provide rapid results enhances client satisfaction and encourages repeat testing. This structural reliance on routine biochemistry establishes clinical chemistry as the foundational pillar of the veterinary diagnostics market. The dominance of the clinical chemistry segment is primarily driven by the high volume of routine health screenings and pre surgical assessments required for companion animals. According to veterinary clinical pathology literature, biochemical testing is a core component of routine laboratory evaluation in small animal practice and is widely used to assess organ function and metabolic status. This high frequency directly stimulates consistent demand for reagents analyzers and consumables across veterinary clinics. According to peer reviewed veterinary medicine literature, serum biochemical testing is routinely used for the assessment of hepatic renal endocrine and metabolic disorders in companion animals. These statistics demonstrate the direct correlation between visit frequency and clinical chemistry utilization. Veterinarians rely on these tests to assess organ function detect metabolic disorders and monitor chronic conditions such as diabetes. The standardization of biochemical panels ensures widespread adoption and interoperability across different laboratory systems. Manufacturers benefit from recurring revenue streams through the sale of proprietary reagents and maintenance contracts.
On the other end, the molecular diagnostics segment is experiencing the fastest growth and is predicted to witness a CAGR of 9.1% over the forecast period owing to the rising demand for precision oncology and genetic disease screening. According to peer reviewed veterinary oncology literature, molecular testing is increasingly used to characterize tumors and identify genetic alterations that can support diagnosis prognosis and treatment selection in companion animals. This shift towards personalized medicine directly stimulates demand for polymerase chain reaction and next generation sequencing services. According to veterinary genetic research, molecular testing is increasingly applied to hereditary disease screening and breed specific genetic conditions in dogs and cats. These statistics demonstrate the expanding application of molecular tools beyond infectious disease detection. Veterinary specialists are increasingly incorporating genomic data into treatment plans improving survival rates for complex cases. Regulatory bodies are establishing guidelines for genetic testing ensuring quality and reliability of results. Pharmaceutical companies are partnering with diagnostic firms to develop companion diagnostics for new drug approvals. This synergy between therapeutics and diagnostics creates new revenue opportunities for molecular testing providers. The focus on early detection of predispositions drives proactive testing among pet owners. This dynamic evolution positions molecular diagnostics as the most rapidly expanding sector within the market.
By Animals Insights
The companion animals segment occupied 63.6% of the European market share in 2025 due to the increasing pet ownership rates and the emotional bond between owners and their animals. According to FEDIAF, European households contained 299 million pets in 2023 and 139 million households owned at least one pet. This vast animal base creates a substantial demand for routine veterinary care and diagnostic services. According to FEDIAF, dogs and cats remain among the most numerous companion animals in Europe and represent major components of the European pet population. These figures underscore the critical role of pets in family life and the corresponding demand for high quality medical attention. Veterinary clinics are expanding their diagnostic capabilities to meet the expectations of discerning pet owners. The prevalence of age related conditions in pets such as arthritis and kidney disease necessitates regular monitoring through imaging and blood tests. Insurance coverage for pets is becoming more common reducing financial barriers to diagnostic procedures. Manufacturers tailor their products to meet the specific needs of small animal practitioners ensuring relevance and usability. This demographic trend ensures that companion animal diagnostics remain the largest revenue generator in the sector. The focus on longevity and quality of life drives continuous innovation in this segment.
However, the food producing animals segment is anticipated to register a prominent CAGR of 12.5% over the forecast period owing to the stringent food safety regulations and the need for disease free livestock. According to the European Food Safety Authority, EU Member States collect and report surveillance data on zoonotic agents in animals food and foodborne outbreaks to support risk assessment and food safety measures. This regulatory framework directly stimulates demand for rapid diagnostic kits and surveillance programs in the livestock sector. According to the European Food Safety Authority and the European Centre for Disease Prevention and Control, the EU One Health zoonoses reporting system uses data from Member States on humans food animals and the environment to monitor zoonotic diseases. These statistics highlight the critical importance of early detection in preventing economic losses and trade restrictions. Farmers are adopting regular screening protocols to maintain herd health and comply with export requirements. Government subsidies support the implementation of biosecurity measures including diagnostic testing. The integration of digital health records facilitates tracking and reporting of test results improving transparency. Manufacturers are developing robust field ready tests that can withstand harsh farm environments. This regulatory pressure ensures sustained growth for diagnostics in the food animal sector. The focus on consumer safety drives continuous improvement in testing sensitivity and speed.
REGIONAL ANALYSIS
Germany Veterinary Diagnostics Market Analysis
Germany held 41.6% of the European market share in 2025 and is likely to maintain robust growth and market leadership over the next few years due to its advanced healthcare infrastructure and high pet ownership rates. According to the Federation of Veterinarians of Europe, Germany is among the European countries with a large veterinary workforce, contributing to broad access to veterinary services. This professional availability drives robust demand for both clinical and laboratory diagnostics. According to the Federation of Veterinarians of Europe, approximately 328,000 veterinarians were estimated to be practicing across Europe in its 2023 survey and Germany was among the countries containing a substantial share of this workforce. The presence of leading diagnostic manufacturers facilitates rapid adoption of new technologies. Strict regulatory standards ensure high quality of diagnostic products fostering trust among veterinarians. The aging pet population requires frequent monitoring for chronic conditions boosting demand for routine tests. Insurance coverage for pets is well established reducing financial barriers for owners. Research institutions collaborate with industry partners to develop innovative diagnostic solutions. The focus on precision medicine drives adoption of molecular and genetic testing. Germany serves as a hub for veterinary innovation and market growth in the region.
France Veterinary Diagnostics Market Analysis
France is projected to experience steady expansion and consistent service scaling over the next few years, maintaining a strong position in the market characterized by a large companion animal population and supportive government policies. According to the French National Veterinary Order, France has a large registered veterinary workforce providing extensive access to veterinary services across companion animal livestock and other practice areas. This extensive network drives consistent demand for diagnostic tools and services. According to the Federation of Veterinarians of Europe, France is among the major European countries represented in the European veterinary workforce and has identified measures to address shortages in rural veterinary services. The cultural attachment to pets leads to high willingness to pay for advanced medical care. Local manufacturers contribute to the market by producing cost effective diagnostic kits. The integration of digital health records is improving efficiency and data sharing among practitioners. Government initiatives promote preventive care encouraging regular health checks and vaccinations. The focus on animal welfare drives adoption of pain management and diagnostic imaging. France balances traditional veterinary practices with modern technological advancements. The market continues to grow through increased awareness and service expansion.
United Kingdom Veterinary Diagnostics Market Analysis
The United Kingdom is anticipated to achieve the highest growth rate among major European peers with a projected CAGR of 7.55% over the forecast period, operating as a key player in the Europe Veterinary Diagnostics Market known for its high pet insurance penetration and advanced veterinary education. According to the Federation of Veterinarians of Europe, the United Kingdom is one of the European countries with a substantial veterinary workforce and established veterinary services. This professional capacity supports higher utilization of laboratory and imaging diagnostics. According to the Royal College of Veterinary Surgeons, veterinary practices in the United Kingdom provide care across companion animal livestock and specialist sectors, supported by a regulated professional workforce. The presence of prestigious veterinary schools fosters innovation and skilled workforce development. Private practices are increasingly adopting point of care diagnostics to improve client convenience. The rise of corporate veterinary chains is standardizing diagnostic protocols and increasing equipment procurement. Public awareness campaigns promote responsible pet ownership and preventive care. The UK market is characterized by high adoption rates of new technologies and strong regulatory oversight. The focus on evidence based medicine drives demand for accurate and reliable diagnostics. The market remains resilient despite economic fluctuations due to strong emotional bonds with pets.
Spain Veterinary Diagnostics Market Analysis
Spain is expected to post accelerated gains and dynamic market penetration in the coming years, experiencing rapid growth in the veterinary diagnostics market driven by increasing pet ownership and modernization of veterinary practices. According to the Spanish Ministry of Agriculture Fisheries and Food, pet ownership is widespread in Spain and animal welfare and responsible ownership policies continue to receive increasing attention. This trend drives demand for comprehensive veterinary care including diagnostic services. According to the Federation of Veterinarians of Europe, Spain is among the European countries affected by veterinary workforce shortages, particularly in rural and remote areas, creating a need for accessible veterinary services. The tourism industry also contributes to the market through demand for pet travel health certificates and screenings. Local distributors are expanding their portfolios to include advanced diagnostic tools. Government initiatives promote animal welfare and responsible ownership encouraging regular vet visits. The adoption of digital technologies is improving practice efficiency and client communication. The market is transitioning from basic care to more sophisticated medical interventions. Spain offers significant opportunities for growth as awareness and affordability improve. The focus on preventive care is driving steady market expansion.
Italy Veterinary Diagnostics Market Analysis
Italy is forecast to sustain moderate yet stable development driven by clinical specialization and rising diagnostic adoption over the next few years, holding a significant position in the market with a large population of companion animals and a growing focus on veterinary specialization. According to the Federation of Veterinarians of Europe, Italy has one of Europe's larger veterinary workforces and veterinary shortages are reported in multiple European countries and sectors. This specialization drives demand for high quality diagnostic products. The government supports research in animal health fostering innovation in diagnostic technologies. The prevalence of Mediterranean diseases such as Leishmaniasis requires specific diagnostic tests boosting niche market segments. Local manufacturers produce reliable diagnostic kits for both companion and livestock animals. The integration of telemedicine is expanding access to specialist advice in rural areas. The market is characterized by a mix of traditional practices and modern technology. Italy continues to invest in veterinary infrastructure to meet growing demand. The focus on quality care drives adoption of advanced diagnostics.
COMPETITIVE LANDSCAPE
The competition in the Europe Veterinary Diagnostics Market is characterized by intense rivalry among global multinational corporations and specialized regional players. Major companies leverage their extensive product portfolios and established distribution networks to maintain leadership positions in both companion and livestock segments. However the market is witnessing increased entry from niche biotechnology firms offering innovative molecular and genetic testing solutions. Intellectual property protection plays a crucial role as companies strive to differentiate their proprietary assays and platforms. Regulatory harmonization under the new European In Vitro Diagnostic Regulation creates both barriers and opportunities for market participants. Companies differentiate themselves through superior customer support rapid turnaround times and integrated digital solutions. Pricing pressure is moderate in premium segments but intense in commodity testing areas. Collaboration between diagnostic manufacturers and pharmaceutical companies is becoming essential to develop companion diagnostics for new therapies. The focus on precision medicine and personalized care drives continuous innovation and product differentiation. This dynamic environment encourages constant adaptation and strategic agility among participants striving to improve diagnostic accuracy and operational efficiency while meeting stringent regulatory standards and evolving customer expectations in the European region.
KEY MARKET PLAYERS
A few noteworthy companies operating in the European veterinary diagnostics market include
- VCA Inc.
- Heska Corporation
- Abaxis Inc.
- VIRBAC
- IDEXX Laboratories Inc.
- Life Technologies Corporation
- Bio-Rad Laboratories Inc.
- Prionics AG
- Pfizer Inc.
Top Players in the Market
Thermo Fisher Scientific Inc
Thermo Fisher Scientific Inc is a dominant force in the Europe Veterinary Diagnostics Market through its comprehensive portfolio of laboratory instruments and reagents. The company provides advanced clinical chemistry and molecular diagnostic solutions that support both reference laboratories and point of care settings. Recent initiatives include the expansion of its digital pathology platforms which enhance diagnostic accuracy and workflow efficiency for veterinary pathologists. Thermo Fisher actively collaborates with European veterinary associations to standardize testing protocols and improve disease surveillance capabilities. The company invests heavily in research and development to introduce novel biomarkers for early disease detection in companion and livestock animals. Its robust distribution network ensures timely delivery of critical diagnostic supplies across the region. Thermo Fisher also focuses on sustainability by developing eco friendly packaging and energy efficient instruments. These strategic efforts reinforce its leadership in providing reliable and innovative diagnostic tools. The integration of automation technologies supports high throughput testing requirements. This comprehensive approach drives sustained growth and enhances animal health outcomes throughout Europe.
IDEXX Laboratories Inc
IDEXX Laboratories Inc contributes significantly to the market through its specialized focus on companion animal diagnostics and reference laboratory services. The company offers a wide range of point of care tests and cloud based software solutions that streamline veterinary practice operations. IDEXX has recently expanded its European reference laboratory network to reduce turnaround times and improve access to specialized testing. The company actively promotes preventive care programs that encourage regular health screenings for pets. IDEXX invests in artificial intelligence technologies to enhance the interpretation of diagnostic results and support clinical decision making. Its commitment to education includes training programs for veterinarians on the latest diagnostic techniques and technologies. The company also partners with insurance providers to facilitate seamless claims processing for diagnostic procedures. These actions solidify its position as a key enabler of high quality veterinary care. The focus on customer experience drives loyalty and repeat business. IDEXX continues to innovate in digital health solutions to meet evolving market needs.
Zoetis Inc
Zoetis Inc plays a vital role in the Europe Veterinary Diagnostics Market with its strong presence in livestock and companion animal health solutions. The company provides a diverse array of diagnostic tests including immunodiagnostics and molecular assays for infectious diseases. Zoetis has recently launched new rapid test kits for emerging zoonotic pathogens addressing critical public health concerns in Europe. The company collaborates with agricultural stakeholders to implement herd health management programs that rely on accurate diagnostics. Zoetis invests in manufacturing facilities within Europe to ensure supply chain resilience and regulatory compliance. Its focus on innovation includes the development of multiplex tests that detect multiple pathogens simultaneously. The company also supports veterinary professionals through technical support and educational resources. Zoetis emphasizes the importance of biosecurity and disease prevention in livestock production. These strategic moves enhance its competitive edge and strengthen relationships with farmers and veterinarians. The integration of diagnostics with therapeutic products offers comprehensive health solutions. This holistic approach drives market expansion and improves animal welfare standards.
Top Strategies Used by Key Market Participants
Key players in the Europe Veterinary Diagnostics Market employ diverse strategies to maintain competitiveness and drive innovation. Product portfolio expansion remains a primary focus as companies invest heavily in researching novel biomarkers and multiplex testing capabilities. Strategic collaborations with veterinary associations and academic institutions facilitate access to clinical data and accelerate product validation. Regulatory compliance is prioritized to navigate the complex In Vitro Diagnostic Regulation framework ensuring uninterrupted market access. Companies also focus on digital integration by developing cloud based platforms that connect diagnostic devices with practice management software. Market penetration strategies include expanding reference laboratory networks to reduce turnaround times and improve service quality. Geographic expansion into emerging European markets allows firms to tap into growing demand for advanced veterinary care. Sustainability initiatives are increasingly adopted to meet environmental standards and consumer expectations. These multifaceted approaches ensure sustained growth and improved animal health outcomes in a highly regulated landscape.
MARKET SEGMENTATION
This research report on the European veterinary diagnostics market has been segmented and sub-segmented into the following categories.
By Product Type
- Clinical Chemistry
- Molecular Diagnostics
- Hematology
- Diagnostic Imaging
- Immunodiagnostics
By Animals
- Companion Animals
- Canine Diagnostics
- Feline Diagnostics
- Other Veterinary Diagnostics
- Food-Producing Animals
- Bovine Diagnostics
- Porcine Diagnostics
- Ovine Diagnostics
- Poultry Diagnostics
- Piscine Diagnostics
By Country
- UK
- France
- Spain
- Germany
- Italy
- Russia
- Sweden
- Denmark
- Switzerland
- Netherlands
- Turkey
- Czech Republic
- Rest of Europe