- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$3.82 BnMarket Estimate, 2026
$4.12 BnMarket Forecast, 2034
$7.47 BnCAGR, 2026–2034
7.72%Executive Summary: Global Medical Image Analysis Software Market
- Market Scope: Comprehensive global analysis of medical image analysis software covering computational processing platforms, AI/ML diagnostic tools, image modalities, application fields, and regional growth vectors.
- Market Valuation: Valued at USD 3.82 billion (2025), estimated at USD 4.12 billion (2026), and projected to reach USD 7.47 billion by 2034, registering a stable CAGR of 7.72% (2026–2034).
- Primary Growth Drivers: Exponential rise in diagnostic imaging procedures due to aging populations and chronic disease prevalence (e.g., cancer and cardiovascular disorders); rapid clinical integration of artificial intelligence and machine learning algorithms; and the expansion of teleradiology services. Restraints include stringent data privacy regulations (HIPAA, GDPR), cybersecurity vulnerabilities, and high implementation costs with interoperability barriers.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (2025 Position) | Fastest-Growing Segment |
|---|---|---|
| By Image Type | 2D Imaging (dominates primary diagnostics and routine X-ray screening with high volume and fast processing) | 3D Imaging (growing at 14.1% CAGR due to complex surgical interventions and detailed anatomical visualization) |
| By Imaging Technology | MRI segment (leads via superior soft tissue contrast and vital roles in neurology and oncology) | CT segment (growing at 13.3% CAGR driven by trauma applications, emergency speed, and cancer staging) |
| By End User | Hospitals (capture the leading market share as central hubs for acute care and enterprise-wide IT infrastructure) | Diagnostic Centers (fastest-growing at 16.2% CAGR driven by outpatient care shifts and specialized imaging facilities) |
| By Region | North America (dominates market size via high healthcare spend, advanced infrastructure, and early AI adoption) | Asia-Pacific (fastest regional growth fueled by healthcare modernization, rising medical tourism, and smart hospital initiatives) |
Major Market Players & Market Structure
Market Structure: Highly competitive digital health landscape featuring multinational medical imaging equipment manufacturers and specialized software vendors competing on algorithm accuracy, cloud integration, regulatory compliance, and seamless PACS interoperability.
Key Companies: Agfa HealthCare, Medviso AB, Aquilab, Bruker Corporation, Carestream Health Inc., GE Healthcare, Siemens Healthineers, and Philips.
Global Medical Image Analysis Software Market Size
The Global Medical Image Analysis Software Market is projected to grow from USD 3.82 billion in 2025 to USD 4.12 billion in 2026 and reach USD 7.47 billion by 2034, registering a CAGR of 7.72% during the forecast period from 2026 to 2034.

Medical image analysis software comprises advanced computational platforms designed to process, visualize, and interpret diagnostic imaging data such as MRI, CT, PET, and ultrasound scans. These sophisticated tools utilize algorithms including artificial intelligence and machine learning to assist radiologists in detecting anomalies, measuring tissue volumes, and planning surgical interventions with high precision. The global healthcare landscape is witnessing an exponential increase in medical imaging procedures driven by the rising prevalence of chronic diseases and aging populations. According to Organisation for Economic Co-operation and Development data from 2025, the average number of MRI exams per 1,000 inhabitants in member countries reached 65, reflecting a 12% increase from the previous year. As per the World Health Organization, cancer diagnoses have risen by 20% globally over the last decade, necessitating more frequent and detailed imaging for staging and monitoring. Regulatory bodies such as the Food and Drug Administration have accelerated the approval pathway for AI based diagnostic software to address the growing workload of radiology departments. The integration of these software solutions into Picture Archiving and Communication Systems has become standard practice in modern hospitals. This technological evolution supports the industry goal of reducing diagnostic errors and improving patient outcomes through quantitative and objective image assessment. The shift toward value based care further incentivizes the adoption of tools that enhance workflow efficiency and reduce unnecessary repeat scans.
MARKET DRIVERS
Surging Volume of Diagnostic Imaging Procedures Due to Chronic Disease Prevalence
The escalating incidence of chronic conditions such as cardiovascular diseases, cancer, and neurological disorders is contributing significantly to the global medical image analysis software market growth due to the critical role of imaging in diagnosis and treatment monitoring. According to the International Agency for Research on Cancer, there were over 20 million new cancer cases globally in 2025, requiring extensive computed tomography and magnetic resonance imaging for accurate staging and radiotherapy planning. As per the American Heart Association, cardiovascular disease remains the leading cause of death worldwide, with over 18 million deaths annually driving demand for cardiac imaging analysis tools that assess heart function and vessel integrity. Radiology departments face immense pressure to process these increasing volumes of data efficiently without compromising diagnostic accuracy. Advanced software solutions automate routine measurements and highlight potential abnormalities, allowing radiologists to prioritize critical cases and reduce interpretation time. The aging global population further exacerbates this trend, as older individuals require more frequent screening for degenerative conditions such as osteoarthritis and dementia. According to the National Institute on Aging, the number of people aged 65 and older will double by 2050, creating a sustained long term demand for diagnostic imaging services. Hospitals are investing in automated analysis software to manage this workload and prevent radiologist burnout. The ability of these tools to provide consistent and reproducible measurements enhances clinical decision making and supports personalized treatment strategies.
Integration of Artificial Intelligence and Machine Learning Algorithms
The rapid advancement and integration of artificial intelligence and machine learning algorithms into medical imaging workflows is further boosting the global market expansion. According to the Journal of Digital Imaging, studies published in 2025 demonstrated that AI powered software can detect lung nodules in CT scans with 94% sensitivity, compared to 85% for human radiologists alone. These algorithms learn from vast datasets of annotated images, which is enabling them to identify subtle patterns and anomalies that may be overlooked during manual review. As per the Food and Drug Administration, over 100 AI based radiology algorithms were cleared in 2024 and is covering applications in stroke detection, fracture identification, and tumor segmentation. Healthcare providers are increasingly adopting these tools to reduce inter observer variability and improve diagnostic confidence. According to the Radiological Society of North America, AI integration reduces report turnaround time by 30%, allowing for faster clinical intervention. Machine learning models also facilitate predictive analytics by correlating imaging features with patient outcomes, supporting proactive care management. The availability of cloud computing resources enables the deployment of complex algorithms without requiring expensive on premise hardware. This technological synergy transforms raw imaging data into actionable clinical insights, driving widespread adoption across academic medical centers and community hospitals. The continuous improvement of algorithm accuracy through deep learning ensures that these tools remain at the forefront of diagnostic innovation.
MARKET RESTRAINTS
Stringent Data Privacy Regulations and Cybersecurity Concerns
The handling of sensitive patient imaging data by analysis software providers is subject to rigorous regulatory scrutiny under laws such as the Health Insurance Portability and Accountability Act and the General Data Protection Regulation, which is creating significant compliance burdens and hampering the medical image analysis software market expansion. According to the Office for Civil Rights, healthcare entities faced over 700 data breach investigations in 2025, with medical imaging systems being increasingly targeted due to the high value of diagnostic records. As per the European Data Protection Board, new guidelines were issued in 2024 requiring explicit consent for the use of patient images in algorithm training, limiting the availability of diverse datasets for software development. Many healthcare institutions hesitate to adopt cloud based analysis platforms due to fears of unauthorized access and data leakage. According to the Ponemon Institute, the average cost of a healthcare data breach reached 10.9 million dollars in 2025, which is discouraging smaller vendors from entering the market. Patients remain concerned about the secondary use of their imaging data for commercial purposes, which are eroding trust in digital health solutions. Compliance with varying international privacy laws adds complexity and cost to software deployment, particularly for multinational vendors. The need for robust encryption and regular security audits increases operational expenses for providers. These regulatory and security concerns slow down adoption rates among risk averse healthcare organizations. The lack of standardized global privacy frameworks creates uncertainty for developers and users alike.
High Implementation Costs and Interoperability Issues
The substantial capital expenditure required for implementing advanced medical image analysis software and the lack of seamless interoperability with existing hospital information systems act as major barriers to market penetration. According to the Healthcare Information and Management Systems Society, only 40% of hospitals in North America have fully integrated their picture archiving and communication systems with third party analysis software due to proprietary data formats. The average cost of deploying an enterprise wide AI imaging solution exceeds 500,000 dollars, including licensing, hardware upgrades, and staff training, which is prohibitive for small and medium sized clinics. As per the American Hospital Association in 2025, budget constraints force many facilities to prioritize essential clinical equipment over optional software enhancements. Lack of standardized application programming interfaces hinders the smooth exchange of data between different vendor platforms, leading to workflow disruptions. Radiologists often struggle with multiple disjointed interfaces, reducing efficiency rather than enhancing it. The return on investment for these software solutions is not always immediately apparent, making it difficult for administrators to justify the expense. Vendors face challenges in demonstrating tangible financial benefits beyond clinical accuracy. This fragmentation limits the scalability of analysis tools and restricts their utility in multi-vendor environments. The high total cost of ownership remains a persistent obstacle for widespread adoption.
MARKET OPPORTUNITIES
Expansion of Tele radiology and Remote Diagnostic Services
The growth of tele-radiology and remote diagnostic services presents substantial opportunities for medical image analysis software providers to extend their reach beyond traditional hospital settings. According to the American Telemedicine Association, the volume of remote imaging interpretations increased by 35% in 2025 due to the shortage of radiologists in rural and underserved areas. Cloud based analysis platforms enable specialists to access and interpret scans from anywhere, facilitating timely diagnosis for patients in remote locations. As per the World Health Organization, 50% of the global population lacks access to essential diagnostic imaging, creating a vast untapped market for scalable software solutions. Software vendors are developing lightweight web based applications that require minimal local infrastructure, making them accessible to clinics with limited resources. The integration of 5G technologies allows for the rapid transmission of high resolution images, ensuring that remote analysis does not compromise diagnostic quality. Partnerships with teleradiology service providers enable software companies to bundle their tools with interpretation services, creating recurring revenue streams. The flexibility of remote access supports after hours coverage and second opinion services, enhancing patient care continuity. This expansion aligns with global efforts to achieve health equity by democratizing access to specialized diagnostic expertise. The demand for efficient remote collaboration tools will continue to drive innovation in cloud based imaging analysis.
Development of Personalized Medicine and Precision Oncology Tools
The rise of personalized medicine and precision oncology offers significant growth opportunities for the global medical image analysis software market. According to the National Cancer Institute, radiomics, the extraction of large amounts of quantitative features from medical images is becoming a critical component of cancer treatment planning. Software tools that analyze tumor texture, shape, and intensity patterns can predict response to chemotherapy and immunotherapy, enabling tailored treatment strategies. As per the European Society for Medical Oncology in 2025, image based biomarkers are increasingly used in clinical trials to stratify patients and monitor therapeutic efficacy. Pharmaceutical companies are partnering with software vendors to validate these imaging endpoints, accelerating drug development processes. The ability to non-invasively assess tumor heterogeneity provides insights that biopsy alone cannot offer. Advanced segmentation algorithms allow for precise volume measurements, tracking disease progression over time. This capability supports dynamic treatment adjustments, improving patient outcomes and reducing unnecessary side effects. The integration of genomic data with imaging features creates comprehensive patient profiles for holistic care. As precision medicine becomes standard practice, the demand for sophisticated analysis tools that support these complex workflows will surge. Vendors who can demonstrate clinical utility in personalized care will gain a competitive edge.
MARKET CHALLENGES
Lack of Standardized Validation and Clinical Evidence
The absence of standardized validation protocols and robust clinical evidence for many medical image analysis algorithms is a significant challenge to the expansion of the global medical image analysis software market. According to the Radiological Society of North America, less than 15% of available AI imaging tools has undergone prospective multicentre clinical trials to prove their real world effectiveness. This evidence gap makes it difficult for healthcare providers to trust and adopt new software solutions confidently. The Food and Drug Administration has tightened its requirements for algorithm transparency and bias testing, requiring vendors to provide extensive documentation on training data demographics. Variability in imaging equipment and acquisition protocols across different hospitals affects algorithm performance, leading to inconsistent results. According to the Journal of the American Medical Informatics Association in 2025, algorithms trained on data from one institution often fail to generalize to others due to domain shift. Clinicians struggle to evaluate the reliability of black box algorithms that do not explain their decision making process. The lack of universal benchmarks for performance metrics complicates comparative assessments. Healthcare systems are reluctant to integrate unproven tools into critical diagnostic workflows due to potential liability risks. Addressing this challenge requires collaborative efforts between vendors, regulators, and clinicians to establish rigorous validation standards. Without consistent evidence, the full potential of image analysis software remains unrealized.
Shortage of Skilled Personnel for Data Annotation and Algorithm Maintenance
The acute shortage of skilled professionals capable of annotating medical images and maintaining complex analysis algorithms creates a bottleneck in the development and deployment of these technologies, which is further challenging the expansion of the global market. According to the Association for Computing Machinery, the demand for data scientists with expertise in medical imaging outstripped supply by a factor of three in 2025. Accurate algorithm training requires thousands of images labeled by board certified radiologists, who are already facing severe workforce shortages. As per the American College of Radiology, radiologist burnout rates have reached 50%, limiting their availability for ancillary tasks such as data annotation. The high cost and time required to create high quality labeled datasets delay product launches and updates. Hospitals lack the internal IT expertise to manage and troubleshoot advanced software systems, leading to reliance on vendor support. The rapid pace of technological change requires continuous education and upskilling of existing staff, which is often neglected due to operational pressures. The turnover rate for technical staff in healthcare IT is higher than in other sectors, exacerbating the talent gap. This human capital constraint limits the scalability of image analysis solutions and increases operational costs. Companies must invest heavily in automated annotation tools and user friendly interfaces to mitigate these workforce challenges.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Covered | By Image Type, Imaging Technology, Application, End-User, and Region |
| Various Analyses Covered | Global, Regional & Country Level Analysis, Segment-Level Analysis, Drivers, Restraints, Opportunities, Challenges, PESTLE Analysis; Porter's Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Regions Covered | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Market Leader Profiled | Agfa HealthCare, Medviso AB, Aquilab, Bruker Corporation, Carestream Health Inc |
SEGMENTAL ANALYSIS
By Image Type Insights
The 2D Imaging segment dominated the market by holding the leading share of the global market in 2025. The growth of the 2D imaging segment in the global market is attributed to its widespread adoption as the primary modality for initial diagnosis and routine screening across global healthcare systems. According to World Health Organization data from 2025, over 3.6 billion X-ray examinations are performed annually worldwide, forming the backbone of diagnostic radiology in both developed and emerging economies. The simplicity and speed of acquiring two dimensional images make them ideal for high volume settings such as emergency departments and outpatient clinics where rapid triage is essential. As per the American College of Radiology, 2D digital radiography accounts for approximately 60% of all imaging procedures in United States hospitals, reflecting its entrenched role in clinical workflows. Software tools designed for 2D analysis focus on enhancing image quality, detecting fractures, and identifying pulmonary abnormalities, which are common clinical presentations. The lower cost of 2D imaging equipment compared to advanced modalities ensures accessibility in resource limited regions, driving consistent software demand. Regulatory approvals for 2D analysis algorithms are generally faster and less complex than those for volumetric data, facilitating quicker market entry for vendors. The vast existing installed base of digital X ray systems creates a stable recurring revenue stream for software providers through upgrades and maintenance contracts. This segment leadership is reinforced by the continuous integration of artificial intelligence for automated detection of conditions such as pneumonia and tuberculosis in standard chest radiographs.
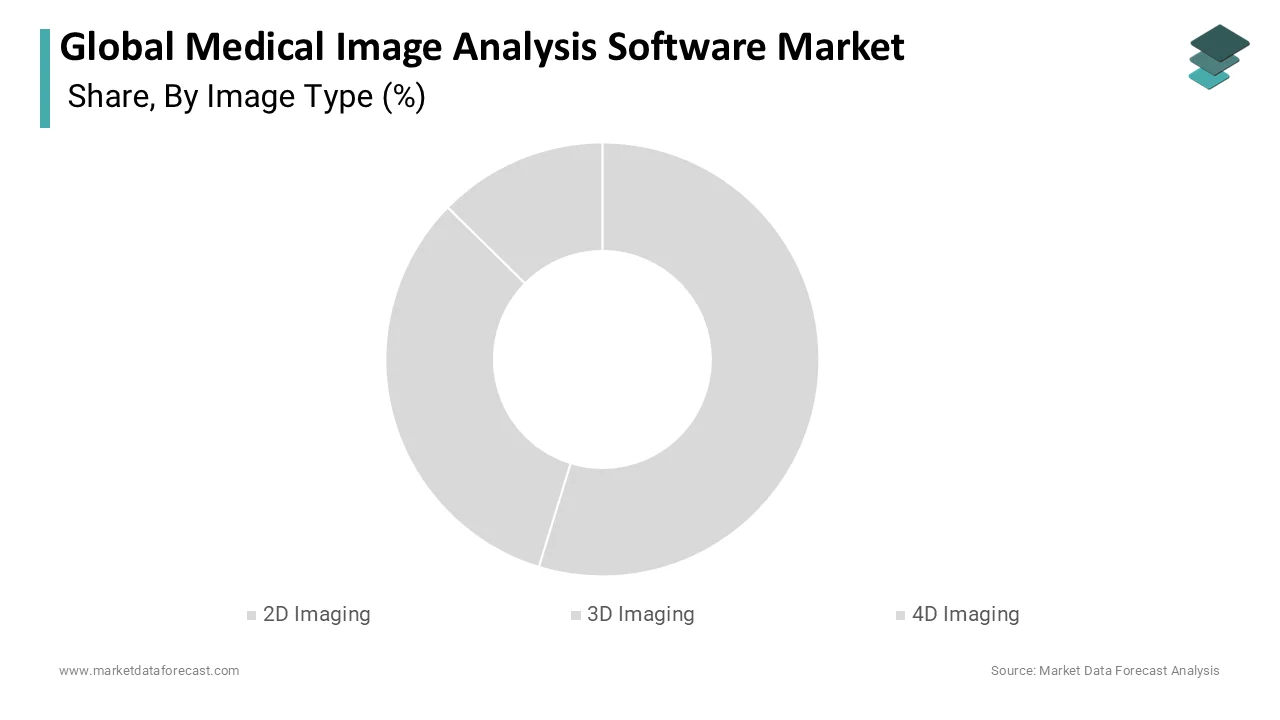
On the other end, the 3D imaging segment is the fastest growing segment and is expected to showcase a CAGR of 14.1% over the forecast period in the global market owing to the increasing complexity of surgical interventions and the demand for precise anatomical visualization. According to the Journal of Digital Imaging, the adoption of 3D reconstruction software for computed tomography and magnetic resonance imaging data increased by 25% in 2025 among orthopedic and neurosurgical departments. These tools allow surgeons to visualize spatial relationships between tumours, blood vessels, and critical structures, enabling safer and more accurate operative planning. As per the Society of Interventional Radiology, 3D printed models derived from software reconstructions reduce operative time by 20% in complex craniofacial and cardiac cases. The rise of minimally invasive procedures necessitates detailed volumetric data to navigate internal anatomy without direct visual access. Advances in graphics processing units have made real time 3D rendering feasible on standard workstations, which is lowering the barrier to adoption. Pharmaceutical companies utilize 3D imaging analysis for tumor volume measurement in clinical trials, accelerating drug development processes. The integration of augmented reality with 3D software provides immersive guidance during surgery, further enhancing precision. As healthcare systems prioritize value based care, the ability of 3D analysis to reduce complications and reoperations drives its rapid uptake. This technological evolution transforms static images into dynamic interactive models supporting personalized medicine.
By Imaging Technology Insights
The MRI segment led the market with the largest share of the global market in 2025. The growth of the MRI segment in the global market is driven by its superior soft tissue contrast and critical role in diagnosing neurological, musculoskeletal and oncological conditions. According to Organisation for Economic Co-operation and Development data, the number of MRI units per million populations in member countries reached 28 in 2025, reflecting significant infrastructure investment. MRI generates large volumes of complex multi planar data, requiring sophisticated software for segmentation, registration, and quantitative analysis. As per the American Journal of Neuroradiology, MRI is the gold standard for detecting brain tumors, multiple sclerosis, and spinal cord injuries, which is accounting for over 40% of neurological imaging studies. The aging global population increases the prevalence of degenerative joint diseases and stroke, necessitating frequent MRI scans for monitoring disease progression. Software solutions for MRI focus on reducing scan times through compressed sensing algorithms and enhancing image resolution via deep learning reconstruction. The expansion of open MRI systems has improved patient comfort, but requires specialized software to correct for magnetic field inhomogeneities. Academic medical centers rely heavily on advanced MRI analysis tools for research into functional connectivity and diffusion tensor imaging. The high reimbursement rates for MRI procedures support the procurement of premium analysis software. This segment dominance is sustained by the irreplaceable diagnostic value of MRI in complex clinical scenarios.
However, the CT segment led the market and is expected to showcase a CAGR of 13.3% over the forecast period owing to its speed, versatility, and critical role in emergency trauma and cancer staging. According to the Centers for Disease Control and Prevention, CT scans accounted for over 80 million procedures in the United States in 2025, making it the most frequently used cross sectional imaging modality. The ability of CT to rapidly visualize internal injuries makes it indispensable in emergency departments where time is critical for survival. As per the National Cancer Institute, CT is the primary tool for lung cancer screening and tumor staging, driving consistent demand for volumetric analysis software. Advances in dual energy CT and spectral imaging provide material decomposition capabilities that require specialized software for interpretation. Artificial intelligence algorithms for automated detection of pulmonary embolism, intracranial hemorrhage, and coronary artery calcium scores are increasingly integrated into CT workflows. The reduction in radiation dose through iterative reconstruction techniques relies heavily on computational power and advanced software algorithms. Hospitals are upgrading to high end slice CT scanners, which generate terabytes of data per scan, necessitating robust analysis platforms. The expansion of CT guided interventions further drives the need for real time image processing tools. This segment growth reflects the central role of CT in modern acute and chronic care management.
By End User Insights
The hospitals segment dominated the market by capturing the leading share of the global market in 2025. The growth of the hospitals segment in the global market is attributed to their role as primary centers for acute care, surgery, and comprehensive diagnostic services. According to the American Hospital Association, over 6,000 community hospitals in the United States perform millions of imaging procedures annually, creating massive demand for integrated analysis solutions. Hospitals require enterprise wide software platforms that can handle diverse imaging modalities and integrate with electronic health records for seamless workflow. The Joint Commission accreditation standards mandate rigorous quality control and reporting, which drives the adoption of standardized analysis tools. Large academic medical centers within hospital networks serve as hubs for complex cases requiring advanced quantification and 3D reconstruction capabilities. The consolidation of healthcare systems has led to centralized radiology departments that leverage cloud based analysis software to serve multiple facilities efficiently. Hospitals prioritize software that reduces radiologist burnout by automating routine measurements and flagging critical findings. The financial scale of hospitals allows for significant capital investment in cutting edge imaging technologies and associated software. Government initiatives to improve healthcare quality metrics further incentivize hospitals to adopt tools that enhance diagnostic accuracy and patient safety. This segment leadership is reinforced by the critical mass of imaging activity concentrated in hospital settings.
However, the diagnostic centres segment is expected to grow at the fastest CAGR of 16.2% over the forecast period owing to the shift toward outpatient care and the proliferation of specialized imaging facilities. According to the International Finance Corporation, the number of independent diagnostic centers in emerging markets grew by 20% in 2025 as patients seek convenient and cost effective alternatives to hospital visits. These centers focus on high throughput imaging services, requiring efficient software tools to maximize patient turnover and minimize reporting turnaround times. As per the International Finance Corporation, the rise of teleradiology enables diagnostic centers to offer 24/7 coverage by connecting with remote radiologists who rely on cloud based analysis platforms. Specialized centers for breast imaging, cardiac care, and musculoskeletal disorders adopt niche software solutions tailored to specific clinical needs. Private equity investment in diagnostic chains has accelerated the adoption of standardized IT infrastructure, including advanced image analysis software. The lower overhead costs of diagnostic centers allow them to invest in latest technology to differentiate themselves from competitors. Patients prefer these facilities for their shorter wait times and personalized service, driving volume growth. The expansion of insurance coverage for outpatient diagnostics further supports this trend. This segment growth reflects the broader decentralization of healthcare delivery and the consumerization of medical services.
COUNTRY LEVEL ANALYSIS
North America Medical Image Analysis Software Market Analysis
North America dominated the market by holding the highest share of the global market in 2025 and is estimated to maintain its position as the largest regional market for medical image analysis software, driven by its advanced healthcare infrastructure, high healthcare expenditure, and early adoption of innovative technologies. According to the Centers for Medicare and Medicaid Services, the United States spent over 4.3 trillion dollars on healthcare in 2025, with a significant portion allocated to diagnostic imaging and digital health solutions. The presence of major software vendors such as GE Healthcare, Siemens Healthineers, and Philips in the region fosters a competitive landscape that drives continuous innovation. The Food and Drug Administration has established a clear regulatory pathway for AI based diagnostic software, encouraging rapid product launches. The high prevalence of chronic diseases such as cancer and cardiovascular conditions creates substantial demand for advanced imaging analysis. Academic medical centers in the United States and Canada lead global research in radiomics and artificial intelligence, facilitating the translation of algorithms into clinical practice. Reimbursement policies from private insurers and government programs support the adoption of value based diagnostic tools. The strong intellectual property protection framework encourages investment in research and development. North America’s mature market serves as a testing ground for new technologies before global expansion. The region’s focus on precision medicine and personalized care further accelerates software adoption.
Europe Medical Image Analysis Software Market Analysis
Europe occupies the second largest position in the global medical image analysis software market due to its robust public healthcare systems and stringent data privacy regulations. According to Eurostat, healthcare expenditure in the European Union reached 10.9% of GDP in 2025, with significant investments in digital health infrastructure. The implementation of the European Health Data Space aims to facilitate cross border data sharing for research and clinical care, driving demand for interoperable analysis software. Countries such as Germany, France, and the United Kingdom have national strategies for artificial intelligence in healthcare, promoting the adoption of diagnostic algorithms. The General Data Protection Regulation imposes strict requirements on patient data handling, influencing software architecture and deployment models. The aging population in Europe increases the burden of chronic diseases, necessitating efficient diagnostic workflows. Public hospitals prioritize cost effective solutions that improve operational efficiency and reduce waiting times. Collaborative research initiatives such as the European Reference Networks foster the development of specialized analysis tools for rare diseases. The presence of leading medical device manufacturers in Germany and the Netherlands supports local innovation. Europe’s emphasis on ethical AI and transparency shapes global standards for medical software. The region’s steady growth is supported by government funding for digital transformation projects.
Asia Pacific Medical Image Analysis Software Market Analysis
The Asia Pacific region exhibits the fastest growth in the global medical image analysis software market owing to the rapid healthcare modernization, increasing healthcare access, and booming medical tourism. According to the Asian Development Bank, healthcare spending in emerging Asia Pacific economies grew by 12% annually between 2020 and 2025, reflecting improved economic conditions and government prioritization. Countries such as China, India, and Japan are investing heavily in hospital infrastructure and digital health technologies to meet the needs of large populations. China’s Healthy China 2030 initiative promotes the use of artificial intelligence in diagnostics to address the shortage of radiologists in rural areas. India’s emergence as a global hub for medical tourism drives demand for high quality diagnostic services in private hospitals. Japan’s super aging society creates immense demand for early detection of cancer and neurological disorders using advanced imaging. The availability of skilled IT professionals in India and China supports the development of local software solutions. Government initiatives in South Korea and Singapore promote smart hospital concepts integrating AI and big data analytics. The rising middle class in Southeast Asia increases out of pocket spending on premium diagnostic services. The region’s diverse market offers opportunities for both high end and cost effective software solutions. Asia Pacific’s dynamic growth trajectory positions it as a key driver of future market expansion.
Latin America Medical Image Analysis Software Market Analysis
Latin America represents an emerging market for medical image analysis software due to the ongoing healthcare infrastructure development and efforts to improve public health outcomes. According to the Pan American Health Organization, healthcare expenditure in the region increased by 8% in 2025 as governments sought to expand access to essential services. Countries such as Brazil and Mexico are implementing national telemedicine programs to bridge the gap between urban and rural healthcare facilities. These initiatives rely on cloud based image analysis software to enable remote diagnosis and specialist consultation. The growing prevalence of non-communicable diseases such as diabetes and hypertension drives demand for diagnostic imaging. Private hospital chains in major cities are adopting international standards and investing in advanced imaging technologies to attract medical tourists. Local distributors partner with global software vendors to provide training and support services. Regulatory frameworks in countries like Argentina and Chile are evolving to accommodate digital health innovations. Economic volatility remains a challenge, but long term demographic trends support market growth. The increasing penetration of internet and mobile technologies facilitates the deployment of cloud based solutions. Latin America’s potential lies in its ability to leapfrog traditional infrastructure limitations through digital health adoption.
Middle East and Africa Medical Image Analysis Software Market Analysis
The Middle East and Africa displays niche but significant growth in the medical image analysis software market due to the government investment in healthcare infrastructure and the development of medical hubs. According to the World Bank, several Gulf Cooperation Council countries allocated over 15% of their national budgets to healthcare in 2025, aiming to become global medical destinations. Countries such as Saudi Arabia and the United Arab Emirates are building state of the art hospitals equipped with the latest imaging technologies and analysis software. The African continent faces challenges related to infrastructure and workforce shortages, but mobile health initiatives are improving access to diagnostic services. South Africa and Kenya are leading the adoption of teleradiology platforms to connect rural clinics with urban specialists. International aid organizations support the deployment of low cost diagnostic tools in sub Saharan Africa. The establishment of medical free zones in Dubai and Abu Dhabi further enhances the region’s appeal as a hub for advanced healthcare delivery and digital health innovation.
COMPETITIVE LANDSCAPE
The Medical Image Analysis Software Market features intense competition among established medical device giants specialized software vendors and emerging artificial intelligence startups competing on algorithm accuracy and workflow integration. Leading companies differentiate themselves through comprehensive platforms that combine hardware compatibility with advanced analytics and cloud based accessibility. The market is characterized by high barriers to entry due to stringent regulatory requirements for clinical validation and data privacy compliance. Price competition is moderate as healthcare providers prioritize diagnostic reliability and ease of use over initial cost savings given the critical nature of medical decisions. Consolidation through acquisitions is common as larger firms seek to expand their algorithm libraries and technical capabilities. Collaboration with research institutions drives innovation and provides credible evidence for clinical utility. The shift toward value based care encourages solutions that demonstrate measurable improvements in patient outcomes and operational efficiency. Regulatory harmonization efforts across regions facilitate faster product launches but require robust quality management systems. Companies that balance technological innovation with practical clinical applicability and strong customer support gain significant market traction in this dynamic sector.
KEY MARKET PLAYERS
Some of the companies that are playing a dominating role in the Global Medical Image Analysis Software Market include:
- Agfa HealthCare
- Medviso AB
- Aquilab
- Bruker Corporation
- Carestream Health, Inc.
- Esaote S.p.A.
- GE HealthCare
- Spacelabs Healthcare
- Merge Healthcare Inc.
- Xinapse Systems Ltd.
- MIM Software Inc.
- Philips Healthcare
- Clarion Technologies
- Siemens Healthineers
- Toshiba Medical Systems Corporation
TOP LEADING PLAYERS IN THE MARKET
- Siemens Healthineers AG maintains a leading position in the Medical Image Analysis Software Market through its comprehensive suite of AI-powered diagnostic tools and integrated imaging platforms. The company leverages its strong hardware presence to bundle advanced software solutions with MRI, CT, and X-ray systems globally. Siemens Healthineers recently strengthened its market position by launching the AI Rad Companion, which automates routine measurements and provides decision support for radiologists. The company invests heavily in research collaborations with academic institutions to validate clinical efficacy and expand algorithm libraries. Its focus on interoperability ensures seamless integration with existing hospital information systems, enhancing workflow efficiency. Siemens Healthineers also emphasizes cybersecurity and data privacy compliance to build trust among healthcare providers. This holistic approach, combining hardware, software, and services, reinforces its reputation as a trusted partner for digital transformation in radiology departments worldwide.
- GE HealthCare Technologies Inc serves as a key innovator in the Medical Image Analysis Software Market, offering cloud-based platforms and artificial intelligence applications for diverse imaging modalities. The company focuses on democratizing access to advanced diagnostics through its Edison intelligent platform, which enables developers to create and deploy algorithms at scale. GE HealthCare recently expanded its portfolio by acquiring specialized AI startups to enhance capabilities in stroke detection and lung nodule analysis. The company strengthens its market presence through strategic partnerships with technology giants to improve computing infrastructure and data management. GE HealthCare prioritizes user-friendly interfaces that reduce cognitive load for clinicians and improve diagnostic accuracy. Its global service network ensures reliable support and continuous software updates for customers. The commitment to open ecosystem development allows third-party developers to contribute to the platform, fostering innovation and customization. This strategy ensures sustained growth and customer loyalty in a competitive global landscape.
- Philips NV contributes significantly to the Medical Image Analysis Software Market by providing integrated informatics solutions and advanced visualization tools for precision diagnosis. The company specializes in enterprise imaging platforms that connect disparate data sources to provide a unified view of patient health. Philips recently introduced new AI driven workflows for cardiac and oncology imaging that automate complex quantification tasks and reduce reporting time. The company strengthens its market position by focusing on value based care models that demonstrate improved patient outcomes and operational efficiency. Philips collaborates with healthcare systems to co develop solutions tailored to specific clinical needs and workflow requirements. Its emphasis on data security and regulatory compliance ensures adherence to global standards such as GDPR and HIPAA. The company also invests in training programs to help radiologists adapt to new technologies and maximize their potential. This customer centric approach drives adoption and long term engagement across hospitals and diagnostic centers globally.
TOP STRATEGIES USED BY THE KEY MARKET PARTICIPANTS
Key players in the Medical Image Analysis Software Market employ strategic initiatives focused on artificial intelligence integration and cloud connectivity to maintain competitive advantage. Companies prioritize the development of automated algorithms that reduce manual workload and enhance diagnostic precision for radiologists. Strategic partnerships with technology firms and academic institutions facilitate access to large datasets for algorithm training and validation. Manufacturers invest in interoperable platforms that seamlessly integrate with existing hospital information systems and electronic health records. Expansion into emerging markets through localized solutions and affordable pricing models drives global reach and adoption. Regulatory compliance and data security remain central to building trust and ensuring smooth market entry. Continuous innovation in user experience design improves clinician acceptance and workflow efficiency. These strategies ensure resilience and growth in a rapidly evolving market characterized by technological advancement and increasing demand for precise diagnostic tools.
RECENT HAPPENINGS IN THIS MARKET
-
In October 2023, Deepnoid offered AI solutions to help staff make diagnostic decisions by detecting abnormal areas. For example, deep Chest is an invention that offers pulmonary sclerosis and pneumothorax through chest X-ray images. In addition, deep Neuro detects brain abnormalities through MRI with the help of the brain's head and neck region aneurysms.
-
In October 2023, Carestream Health announced an expansion of its family of DR detectors with the addition of Focus HD 35 and Focus HD 43 detectors. They offer a higher resolution for magnification of the image and a higher definition for improved image quality for better visibility of small objects and microstructures.
MARKET SEGMENTATION
This research report on the global medical image analysis software market is segmented and sub-segmented based on the image type, imaging technology, application, end-user, and region.
By Image Type
- 2D Imaging
- 3D Imaging
- 4D Imaging
By Imaging Technology
- X-Ray
- Computed Tomography
- High-End Slice CT
- Mid-End Slice CT
- Low-End Slice CT
- Positron Emission Tomography
- Single Photon Emission Computed Tomography
- Magnetic Resonance Imaging
- Open MRI Systems
- Closed MRI Systems
- Ultrasound
- Radiographic Imaging
By Application
- Cardiovascular
- Neurology
- Dental
- Urology
- Orthopedic
- Oncology
- Obstetrics and Gynaecology
- Mammography
By End-User
- Hospitals
- Research Centres
- Diagnostic Centres
By Region
- North America
- Europe
- Asia Pacific
- Latin America
- The Middle East and Africa