- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$116.8 BnMarket Estimate, 2026
$121.4 BnMarket Forecast, 2034
$165.2 BnCAGR, 2026–2034
3.92%Global Canned Food Market Size, Growth, Trends & Forecast (2026–2034)
The global canned food market size was valued at USD 116.86 billion in 2025, is anticipated to reach USD 121.44 billion in 2026, and is projected to scale up to USD 165.18 billion by the end of 2034, registering a compound annual growth rate (CAGR) of 3.92% during the forecast period from 2026 to 2034. Driven by rapid urbanization, busy lifestyles requiring convenient meal solutions, and exceptional shelf stability that reduces food waste, the canned food industry continues to expand across residential and institutional sectors worldwide.
Key Executive Metrics (At-a-Glance)
- 2025 Base Valuation: USD 116.86 Billion
- 2026 Current Valuation: USD 121.44 Billion
- 2034 Forecast Valuation: USD 165.18 Billion
- Compound Annual Growth Rate (CAGR): 3.92% (2026–2034)
- Dominant Type Segment: Canned Vegetables (holding the largest market share in 2025)
- Dominant Distribution Channel: Supermarkets (holding the major market share in 2025)
- Dominant Region: North America (capturing 34.3% of the global market share in 2025)
Core Market Drivers
- Increasing Urbanization and Busy Lifestyles: Growing demand for quick, time-saving meal preparation options among working professionals and dual-income households.
- Enhanced Shelf Stability and Food Security: Long shelf life (2 to 5 years) minimizing food spoilage, reducing waste, and ensuring reliable provisions during supply chain disruptions.
Primary Market Restraints & Challenges
- Consumer Perceptions and Packaging Health Concerns: Persistent misconceptions regarding lower nutritional value compared to fresh produce, alongside anxiety over chemical contaminants like BPA in can linings.
Global Canned Food Market Segmentation Breakdown
| Segment Category | Leading Sub-Segment | Fastest-Growing Sub-Segment |
|---|---|---|
| By Type | Canned Vegetables (held largest share in 2025 due to year-round nutrient access and affordability) | Canned Ready-to-Eat Meals (projected at a 5.8% CAGR driven by single-person households and urban professionals) |
| By Distribution Channel | Supermarkets (held major share in 2025 offering comprehensive brand varieties and one-stop shopping) | Internet Sales (projected at an 8.4% CAGR fueled by online grocery expansion and home delivery convenience) |
| By Region | North America (held 34.3% share backed by high per capita consumption and established retail infrastructure) | Asia-Pacific (projected with rapid growth driven by urbanization, retail modernization, and emerging middle classes) |
Major Industry Players Profiled
Key enterprises shaping the competitive global canned food market include Dole Food Company Inc, DelMonte Pacific Ltd, ConAgra Foods Inc, H.J. Heinz Company, Pinnacle Foods Inc, B&G Food Holdings Corporation, Bolton Group International, La Doria, Campbell Soup, Nestle, Zanlakol, CECAB Group, Princes Limited, Bonduelle, and Thai Union Group among others.
Global Canned Food Market Size
The global canned food market size was valued at USD 116.86 billion in 2025 and the global market size is expected to reach USD 165.18 billion by 2034 from USD 121.44 billion in 2026. The market is growing at a CAGR of 3.92% during the forecast period.

Canned food comprises a diverse array of preserved food products, including fruits, vegetables, seafood, meats, and ready-to-eat meals, that are sealed in airtight containers and thermally processed to ensure long-term shelf stability. This preservation method effectively inhibits microbial growth while retaining nutritional value and flavor profiles, making it a cornerstone of global food security and convenience. According to the United States Department of Agriculture, canned foods retain comparable nutritional quality to fresh varieties, challenging the misconception that processing significantly degrades quality. Furthermore, according to the Food and Agriculture Organization of the United Nations, approximately 13.2% of all food produced globally is lost due to spoilage, a figure that canning technology drastically reduces by extending product life for several years. These factors underscore the critical role of canned goods in minimizing waste and ensuring consistent food availability across seasons and geographies. As urbanization accelerates and dual-income households become the norm, the demand for quick preparation options rises. The industry continues to innovate with BPA-free linings and sustainable packaging materials to address consumer health and environmental concerns. This evolution ensures that canned food remains a vital component of modern diets, balancing convenience with nutritional integrity and economic accessibility for consumers worldwide.
MARKET DRIVERS
Increasing Urbanization and Busy Lifestyles Driving Convenience Demand
Rapid urbanization and the consequent shift in lifestyle patterns are driving the global canned food market expansion. According to the United Nations Department of Economic and Social Affairs, 68% of the world population will live in urban areas by 2050, which is creating a demographic that prioritizes time-saving solutions for meal preparation. Urban dwellers often face longer commutes and demanding work schedules, leaving limited time for cooking from scratch. According to the Bureau of Labor Statistics, the average American spends only 35 minutes per day on food preparation and cleanup, highlighting the need for convenient alternatives. Canned foods offer an immediate solution by eliminating washing, peeling, and chopping steps, thereby reducing meal preparation time by up to 50%. This efficiency aligns perfectly with the needs of working professionals and young families who seek nutritious yet quick dining options. The correlation between urban density and packaged food consumption is well documented, as city living often limits access to fresh produce markets compared to rural areas. Consequently, supermarkets in metropolitan areas stock extensive varieties of canned goods to meet this sustained demand. This structural shift in daily routines ensures that canned food remains an indispensable part of the modern urban pantry, which is driving consistent market growth.
Enhanced Shelf Stability Reducing Food Waste and Ensuring Security
The exceptional shelf life of canned foods is another significant driver for both household consumers and institutional buyers concerned with food security and waste reduction. According to the Natural Resources Defense Council, 40% of food in the United States goes uneaten, with perishable items contributing disproportionately to this waste due to short expiration dates. Canned products, by contrast, can remain safe and nutritious for two to five years without refrigeration, allowing consumers to purchase in bulk and store for extended periods. This longevity is particularly valuable during emergency situations or supply chain disruptions, as evidenced by increased sales during natural disasters. According to the Federal Emergency Management Agency, keeping a three-day supply of non-perishable food is recommended, with canned goods being the primary recommendation due to their durability. For retailers, reduced spoilage rates translate to lower operational costs and higher profit margins, encouraging wider distribution. The ability to transport canned goods without cold chain infrastructure also lowers logistics costs and carbon emissions. This economic and environmental efficiency makes canned food an attractive option for governments and NGOs addressing food insecurity. The inherent stability of these products thus drives adoption across various sectors, reinforcing their market position.
MARKET RESTRAINTS
Consumer Perception of Lower Nutritional Value and Freshness
Despite scientific evidence to the contrary, a persistent consumer perception that canned foods are less nutritious than fresh alternatives is impeding the regional market growth. According to the International Food Information Council, 60% of consumers believe fresh produce is significantly healthier than canned versions, leading them to prioritize fresh items despite higher costs and shorter shelf lives. This misconception is often fueled by marketing campaigns that emphasize farm-to-table freshness and organic sourcing, which canned products struggle to match in public image. Additionally, concerns about sodium and added sugars in canned vegetables and fruits deter health-conscious buyers. According to the Centers for Disease Control and Prevention, excessive sodium intake is a major public health issue, and many canned products contain high levels for preservation and flavor. Although low-sodium options exist, they represent a smaller portion of shelf space and are often more expensive. This negative perception limits the willingness of premium segment consumers to incorporate canned goods into their regular diets. Manufacturers face an uphill battle in changing these deep-seated beliefs, requiring substantial investment in educational marketing. Until this perception shifts, the market will continue to face resistance from a significant portion of the health-oriented demographic.
Health Concerns Regarding Chemical Contaminants in Packaging
Growing awareness regarding potential chemical migration from can linings into food products is further impeding the global canned food market expansion. According to the National Institute of Environmental Health Sciences, concerns about Bisphenol A, a chemical used in epoxy resins for can linings, may disrupt endocrine function. Although many manufacturers have shifted to BPA-free alternatives, consumer skepticism remains high due to lack of transparency about replacement chemicals. According to the Environmental Working Group, over 70% of canned foods tested still contained detectable levels of BPA or its substitutes, raising alarms among safety advocates. This uncertainty leads some consumers to avoid canned products entirely in favor of glass or fresh options perceived as safer. Regulatory bodies in various regions are tightening standards for food contact materials, forcing companies to invest heavily in research and development for safer lining technologies. These compliance costs can increase product prices, further eroding competitiveness against fresh produce. The fear of long-term health effects creates a barrier to entry for new customers and encourages existing users to reduce consumption. Addressing these safety concerns is critical for the global market to maintain trust and prevent further erosion of its customer base.
MARKET OPPORTUNITIES
Innovation in Sustainable and Eco-Friendly Packaging Materials
The development and adoption of sustainable packaging solutions is a significant opportunity for the canned food market to appeal to environmentally conscious consumers. According to the Ellen MacArthur Foundation, only 14% of plastic packaging is currently recycled globally, prompting a surge in demand for recyclable metal containers, which have a recycling rate of over 70% in many developed nations. Aluminum and steel cans are infinitely recyclable without loss of quality, making them a preferred choice for brands aiming to reduce their environmental footprint. Companies are investing in lightweighting technologies to reduce material usage and transportation emissions, further enhancing sustainability credentials. According to the Aluminum Association, recycling aluminum saves 95% of the energy required to produce new metal, a compelling statistic for eco-friendly marketing. By highlighting these benefits, manufacturers can differentiate their products and attract younger demographics who prioritize sustainability. Additionally, innovations in plant-based linings and biodegradable labels offer further avenues for green branding. This shift towards circular economy principles not only mitigates regulatory risks, but also builds brand loyalty among consumers who view packaging choices as a reflection of their values. Embracing sustainability thus opens new market segments and strengthens competitive advantage.
Expansion into Premium and Gourmet Product Segments
The emergence of premium and gourmet canned foods offers a lucrative opportunity to elevate the category beyond basic staples and attract higher-income consumers. According to the Specialty Food Association, sales of specialty foods, including artisanal canned seafood and exotic vegetables, grew by 12% annually, outpacing conventional grocery categories. Consumers are increasingly willing to pay a premium for high-quality ingredients, unique flavors, and ethical sourcing stories associated with gourmet canned products. Brands are offering items such as hand-packed tuna, heirloom beans, and organic fruit compotes in aesthetically pleasing packaging to appeal to discerning buyers. This trend is driven by the culinary exploration habits of millennials and Gen Z, who seek restaurant-quality experiences at home. The rise of social media food culture further amplifies demand for visually appealing and Instagram-worthy products. By positioning canned goods as culinary ingredients rather than just emergency rations, manufacturers can command higher margins and build stronger brand equity. Collaborations with celebrity chefs and inclusion in subscription boxes also help penetrate this upscale market. This strategic pivot allows the industry to tap into the growing discretionary spending on food experiences, driving value growth even if volume remains stable.
MARKET CHALLENGES
Volatility in Raw Material and Energy Costs
The canned food market faces significant challenges due to the volatility in prices of key raw materials such as steel, aluminum, and agricultural commodities. According to the World Bank Commodity Markets Outlook, metal prices fluctuated by 25% in the past year due to supply chain disruptions and geopolitical tensions, directly impacting production costs for can manufacturers. Since packaging constitutes a substantial portion of total product cost, these fluctuations squeeze profit margins for food processors, who often operate on thin margins. Additionally, the thermal processing required for canning is energy-intensive, making the sector vulnerable to rising electricity and fuel prices. According to the International Energy Agency, industrial energy costs increased by 15% globally, forcing companies to either absorb costs or pass them on to consumers. Price increases can dampen demand, especially in price-sensitive markets where canned food competes with inexpensive fresh produce. Hedging strategies offer some protection, but are complex and costly to maintain. This financial instability makes long-term planning difficult and discourages investment in capacity expansion. Manufacturers must continuously optimize operations and explore alternative materials to mitigate these risks, but the inherent exposure to global commodity markets remains a persistent challenge.
Stringent Regulatory Compliance and Labeling Requirements
Navigating the complex and evolving landscape of food safety regulations and labeling requirements poses a substantial challenge for canned food manufacturers. The Food and Drug Administration in the United States and the European Food Safety Authority in Europe frequently update guidelines on additives, contaminants, and nutritional labeling, requiring constant vigilance and adaptation. According to the Global Food Safety Initiative, compliance costs can account for up to 10% of total operational expenses for small and medium-sized enterprises, creating a barrier to market entry and expansion. Recent mandates for clearer allergen warnings and front-of-pack nutrition labels require redesigning packaging and reformulating products, which involves significant time and financial investment. Non-compliance can result in severe penalties, product recalls, and reputational damage, making accuracy critical. Additionally, differing regulations across export markets complicate international trade, as manufacturers must tailor products to meet specific local standards. This regulatory fragmentation increases administrative burdens and slows down product launches. Keeping pace with these changes requires dedicated legal and quality assurance teams, adding to overhead costs. For smaller players, these demands can be overwhelming, leading to market consolidation. Thus, regulatory complexity remains a formidable hurdle that requires robust management systems to overcome.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 3.92% |
| Segments Covered | By Type, Distribution Channel, and Region |
| Various Analyses Covered | Global, Regional and Country Level Analysis; Segment-Level Analysis; DROC; PESTLE Analysis; Porter’s Five Forces Analysis; Competitive Landscape; Analyst Overview of Investment Opportunities |
| Regions Covered | North America, Europe, APAC, Latin America, Middle East & Africa |
| Market Leaders Profiled | Dole Food Company Inc, DelMonte Pacific Ltd, ConAgra Foods Inc, H.J. Heinz Company, Pinnacle Foods Inc, B&G Food Holdings Corporation, Bolton Group International, La Doria, Campbell Soup, Nestle, Zanlakol, CECAB Group, Princes Limited, Bonduelle, Thai Union Group |
SEGMENTAL ANALYSIS
By Type Insights
The canned vegetables segment held the largest share of the global market in 2025 due to their ability to provide year-round access to essential nutrients with minimal preparation time. According to the United States Department of Agriculture, canned vegetables retain up to 90% of their original vitamin content, dispelling myths about significant nutrient loss during processing. This nutritional parity with fresh produce, combined with a shelf life of two to five years, makes them a staple in household pantries. According to the Centers for Disease Control and Prevention, only 10% of Americans meet the daily recommended intake of vegetables, driving health-conscious consumers toward convenient alternatives like canned greens and beans. The relation between health goals and convenience is pivotal, as canned options eliminate washing and chopping barriers. Furthermore, the affordability of canned vegetables compared to out-of-season fresh produce ensures consistent demand across income levels. Retailers prioritize this segment due to high turnover rates and low spoilage risks. The versatility of canned vegetables in various cuisines further cements their market leadership. As consumers seek to balance busy schedules with dietary guidelines, canned vegetables offer a practical solution that aligns with modern lifestyle constraints while supporting public health objectives.
However, the canned ready-to-eat meals segment is the fastest-growing segment with a projected CAGR of 5.8%, driven by the increasing number of single-person households and urban professionals seeking quick meal solutions. According to the United Nations Department of Economic and Social Affairs, single-person households will account for 33% of all households in developed nations by 2030, creating a surge in demand for portion-controlled meals. These consumers prioritize speed and ease of preparation, favoring products that require only heating. According to the Bureau of Labor Statistics, full-time workers spend an average of 35 minutes per day on food preparation, making ready-to-eat options highly attractive for lunch and dinner. The relation between time scarcity and meal choice is direct, as canned meals eliminate cooking and cleaning efforts. Manufacturers are responding by introducing diverse global flavors and healthier formulations to appeal to discerning tastes. The portability of these meals also supports the growing trend of eating on the go or at work. This demographic shift ensures sustained growth for the segment as urbanization continues to reshape domestic dining habits and prioritizes efficiency over traditional cooking methods.
By Distribution Channel Insights
The supermarkets segment held the major share of the global market in 2025 due to their ability to offer a wide variety of brands and products under one roof. According to the National Grocers Association, supermarkets account for over 60% of all grocery sales in the United States, providing consumers with unparalleled access to canned goods. The extensive shelf space allows for detailed comparison of prices, ingredients, and nutritional information, empowering informed purchasing decisions. According to the Food Marketing Institute, 75% of shoppers prefer supermarkets for their weekly grocery needs due to the convenience of buying fresh produce alongside packaged items. This one-stop shopping experience drives impulse purchases and bulk buying of canned staples. Supermarkets also leverage their buying power to negotiate lower prices with manufacturers, passing savings to consumers and maintaining competitive advantage. The presence of private label brands further enhances affordability and loyalty. Promotional activities such as discounts and bundle offers are frequently used to stimulate demand. The established infrastructure and widespread geographic presence of supermarkets ensure that canned foods remain easily accessible to the majority of the population, solidifying their dominant position in the distribution landscape.
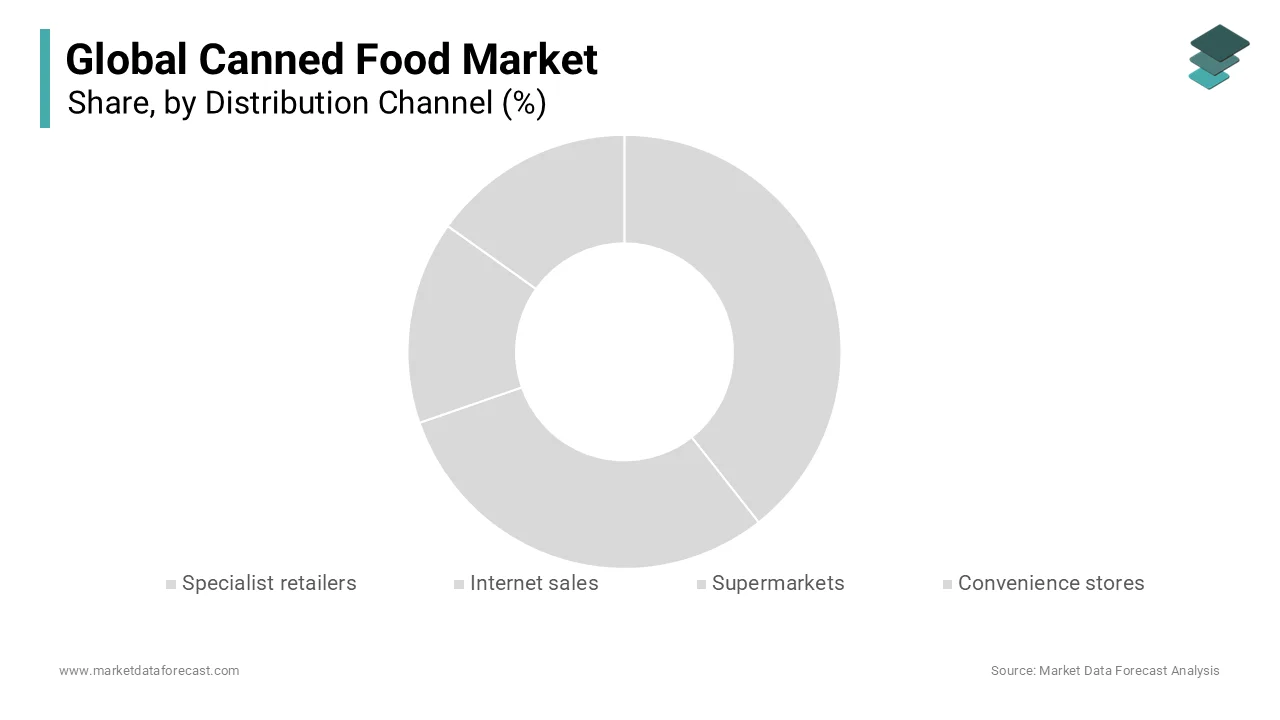
However, the internet sales segment is estimated to record a CAGR of 8.4% over the forecast period in the global market owing to the rapid expansion of online grocery platforms and improved logistics networks. According to the United States Census Bureau, e-commerce sales for food and beverage stores increased by 15% in the last year, reflecting a permanent shift in consumer shopping habits. The convenience of home delivery appeals to busy families and elderly individuals who find physical shopping challenging. According to the McKinsey Global Institute, 40% of consumers now use online grocery services regularly, citing time savings and ease of comparison as key benefits. The relation between digital accessibility and purchase frequency is strong, as automated reorder features ensure pantry staples are never out of stock. Major retailers and pure-play e-commerce giants have invested heavily in cold chain and dry goods logistics to ensure timely and safe delivery of canned products. The ability to access a wider range of niche and international brands online further drives growth. As internet penetration increases in rural areas, the reach of online canned food sales expands. This digital transformation reshapes the retail landscape, offering a scalable and efficient alternative to traditional brick-and-mortar stores.
REGIONAL ANALYSIS
North America Canned Food Market Analysis
North America captured 34.3% of the global market share in 2025 and is likely to maintain steady expansion over the next few years owing to the high consumer acceptance and well-established retail infrastructure. According to the United States Department of Agriculture, canned food consumption per capita in the US remains steady at over 90 servings per year, reflecting its entrenched role in daily diets. The region benefits from advanced manufacturing technologies and strict food safety standards that ensure product quality and consumer trust. According to the Canadian Food Inspection Agency, compliance with labeling and safety regulations is high, facilitating smooth trade between the US and Canada. The prevalence of dual-income households and busy lifestyles further sustains demand for convenient meal solutions. Innovation in BPA-free linings and sustainable packaging addresses environmental concerns, keeping the market relevant to eco-conscious consumers. The strong presence of major multinational food corporations drives continuous product development and marketing initiatives. Additionally, the region’s robust e-commerce sector supports the growth of online canned food sales. Government initiatives promoting food security and waste reduction also favor canned products due to their long shelf life. This combination of cultural acceptance, regulatory stability, and technological advancement ensures North America remains a mature yet dynamic market for canned foods.
Europe Canned Food Market Analysis
Europe is projected to experience stable development in the coming years due to a strong emphasis on sustainability and high quality standards. According to the European Commission, the EU has implemented stringent regulations on packaging waste, driving innovation in recyclable metal cans and biodegradable labels. Consumers in Europe are increasingly demanding organic and locally sourced canned products, prompting manufacturers to adapt their supply chains. According to the European Canned Fruit and Vegetable Association, sales of organic canned goods grew by 10% annually, reflecting this shift in preference. The region’s mature retail sector focuses on premiumization, with gourmet canned seafood and vegetables gaining popularity. Environmental awareness is a key driver, as consumers associate metal packaging with higher recycling rates compared to plastic. The Farm to Fork Strategy aims to reduce the environmental footprint of food systems, encouraging sustainable production practices. Trade agreements within the EU facilitate the movement of canned goods across borders, ensuring diverse product availability. However, strict regulations on additives and contaminants require continuous compliance efforts. Despite these challenges, the focus on quality and sustainability keeps the European market robust and innovative, setting trends for other regions.
Asia Pacific Canned Food Market Analysis
Asia Pacific is expected to witness rapid growth in the near future and is dominating the global market due to the rapid urbanization and changing dietary habits in emerging economies. According to the Food and Agriculture Organization of the United Nations, urban population growth in Asia is leading to increased demand for convenient and processed foods, including canned items. Countries like China and India are seeing a rise in middle-class consumers who value the convenience and safety of branded canned products. According to the Asian Development Bank, retail modernization is expanding access to supermarkets and e-commerce platforms, facilitating greater distribution of canned goods. Traditional preferences for fresh food are gradually shifting as younger generations adopt westernized lifestyles. Local manufacturers are investing in capacity expansion to meet rising domestic demand, while international brands enter the market through partnerships. The region’s diverse culinary traditions offer opportunities for localized product innovations, such as canned curries and noodles. Government initiatives to improve food security and reduce post-harvest losses also support the canning industry. However, price sensitivity remains a challenge, requiring affordable product offerings. The sheer scale of population and economic growth ensures that Asia Pacific will continue to be a primary engine for global canned food market expansion.
Latin America Canned Food Market Analysis
Latin America is anticipated to show positive market momentum over the next few years due to the increasing urbanization and the expansion of modern retail channels. According to the Inter-American Development Bank, the middle class in Latin America has grown significantly, leading to higher disposable incomes and greater consumption of packaged foods. Brazil and Mexico are the largest markets in the region, benefiting from strong agricultural bases that support local canning industries. According to the Brazilian Association of Food Industries, canned bean and corn consumption is high due to their staple status in local diets. Economic volatility sometimes impacts purchasing power, but canned foods remain popular due to their affordability and long shelf life. The rise of supermarket chains and convenience stores improves product accessibility in urban areas. Export opportunities for tropical fruits and seafood also contribute to market vitality. However, infrastructure challenges in logistics and distribution can hinder market penetration in rural areas. Government policies supporting local agriculture and food processing help stabilize supply. As economic conditions improve and retail infrastructure develops, Latin America presents significant potential for growth in the canned food sector, particularly for value-oriented products.
Middle East and Africa Canned Food Market Analysis
The Middle East and Africa are projected to post gradual gains over the coming years with potential for growth driven by food security initiatives and urbanization. According to the African Union, reducing post-harvest losses is a priority, and canning offers a viable solution for preserving perishable agricultural outputs. In the Middle East, high reliance on food imports makes canned goods essential for ensuring stable supply. The Gulf Cooperation Council countries have well-developed retail sectors that support the sale of international canned brands. Population growth and urbanization in Africa are gradually increasing demand for convenient food options. According to the World Bank, investment in food processing infrastructure is increasing, enabling local production of canned tomatoes and fruits. However, limited cold chain infrastructure and lower purchasing power in many African nations constrain market size. Religious dietary laws in the Middle East influence product formulation, requiring halal certification for meat and seafood products. Political instability in some regions can disrupt supply chains, posing risks to market consistency. Despite these challenges, the strategic importance of food preservation and the growing urban population create opportunities for market expansion, particularly for basic staple canned goods.
COMPETITIVE LANDSCAPE
The competitive landscape of the Canned Food Market is characterized by intense rivalry among established multinational corporations and regional specialists. Major players compete on the basis of brand recognition, product quality, and sustainability credentials rather than price alone. The market exhibits moderate barriers to entry due to high capital requirements for processing facilities and strict regulatory compliance. Incumbent firms leverage their extensive distribution networks and economies of scale to maintain cost advantages and shelf space dominance. Competition is further intensified by the rise of private label brands offered by large retail chains which provide cheaper alternatives to name brands. Companies must continuously innovate to meet changing consumer preferences for health and convenience. Strategic alliances with suppliers and logistics providers are essential for ensuring consistent product availability. The presence of numerous small artisanal brands adds diversity but poses limited threat to major players. This dynamic environment fosters continuous improvement in product offerings and operational efficiency benefiting consumers through greater choice and value.
KEY MARKET PLAYERS
Some of the key players in the global canned food market are
- Dole Food Company Inc
- DelMonte Pacific Ltd
- ConAgra Foods Inc
- H.J. Heinz Company
- Pinnacle Foods Inc
- B&G Food Holdings Corporation
- Bolton Group International
- La Doria
- Campbell Soup
- Nestle
- Zanlakol
- CECAB Group
- Princes Limited
- Bonduelle
- Thai Union Group
Top Players in the Market
- Conagra Brands is a leading force in the North American canned food sector with a diverse portfolio including iconic brands like Hunt’s and Chef Boyardee. The company recently launched a comprehensive sustainability initiative aimed at reducing packaging waste and sourcing ingredients from regenerative agriculture practices. This strategic move aligns with growing consumer demand for environmentally responsible products and enhances brand loyalty. Conagra also invested in digital marketing campaigns to engage younger demographics through social media platforms. These efforts strengthen its market position by modernizing its image while maintaining trust among traditional consumers. The company continues to innovate with healthier formulations such as low sodium and no added sugar options. By focusing on operational efficiency and product quality, Conagra ensures consistent delivery of value to retailers and consumers alike.
- Del Monte Foods specializes in high quality canned fruits and vegetables with a strong global presence and commitment to sustainable farming. The company recently expanded its organic product line to meet the rising demand for clean label foods in key markets. This expansion allows Del Monte to capture health conscious consumers who prioritize natural ingredients and ethical sourcing. The company also implemented advanced supply chain technologies to improve traceability and reduce environmental impact. These actions enhance transparency and build trust with stakeholders. Del Monte actively partners with local farmers to ensure a steady supply of premium produce. By focusing on innovation and sustainability, the company strengthens its competitive edge and maintains its reputation for quality. Its strategic investments in production capabilities ensure it can meet evolving consumer preferences effectively.
- Thai Union Group is a global leader in canned seafood particularly tuna and sardines with a focus on sustainable fishing practices. The company recently achieved significant milestones in its SeaChange sustainability strategy by ensuring all sourced tuna is fully traceable and responsibly caught. This commitment addresses consumer concerns about overfishing and environmental degradation. Thai Union also invested in state of the art processing facilities to improve product quality and safety standards. These enhancements allow the company to meet stringent international regulations and access premium markets. The group actively collaborates with NGOs and industry partners to promote ocean conservation. By prioritizing sustainability and innovation, Thai Union strengthens its brand equity and secures long term growth in the competitive global seafood market.
Top Strategies Used by Key Market Participants
Key players in the Canned Food Market primarily focus on product innovation and sustainability to maintain competitive advantage. Companies invest heavily in research and development to create healthier formulations with reduced sodium and no artificial additives. They frequently adopt eco friendly packaging solutions to address environmental concerns and appeal to conscious consumers. Strategic partnerships with local farmers ensure high quality raw materials and support sustainable agriculture practices. Mergers and acquisitions are used to expand product portfolios and enter new geographic markets rapidly. Leading participants also leverage digital marketing and e commerce platforms to reach broader audiences and enhance customer engagement. Pricing strategies often involve private label collaborations with major retailers to ensure volume stability. Additionally, companies prioritize supply chain resilience to mitigate risks from geopolitical tensions and climate change. These multifaceted approaches enable firms to navigate market dynamics and sustain long term growth.
MARKET SEGMENTATION
This research report on the global canned food market has been segmented and sub-segmented based on type, distribution channel, and region.
By Type
- Canned meat products
- Canned seafood
- Canned vegetables
- Canned fruit
- Canned ready to eat meals
- Canned desserts
- Canned pasta
- Canned soups
- Canned cooking sauces
By Distribution channel
- Specialist retailers
- Internet sales
- Supermarkets
- Convenience stores
By Region
- North America
- Europe
- The Asia Pacific
- Latin America
- Middle East and Africa