- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$60.04 BnMarket Estimate, 2026
$73.55 BnMarket Forecast, 2034
$372.96 BnCAGR, 2026–2034
22.50%Executive Summary: Global Self-Driving Cars Market
- Market Scope: Comprehensive global market analysis of self-driving (autonomous) cars covering application sectors, hardware and software components, automation levels (Level 3 to Level 5), AI/LiDAR sensing technologies, and regional adoption metrics.
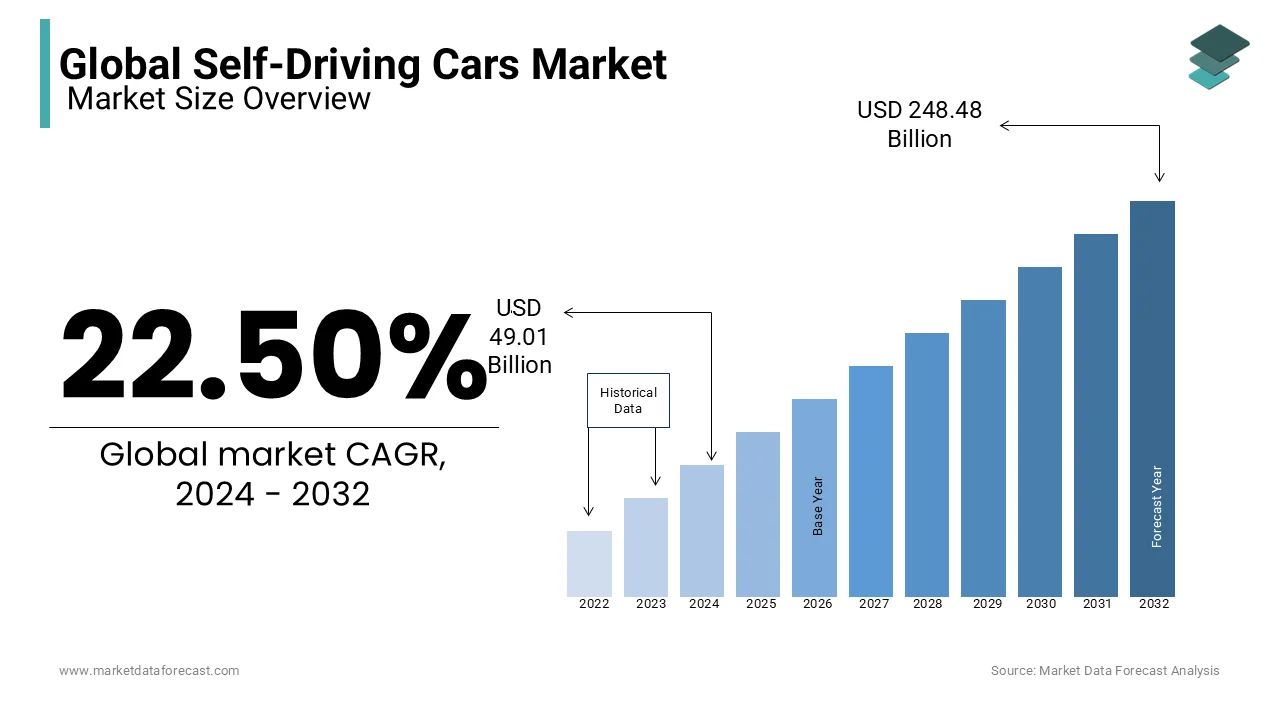
- Market Valuation: Valued at USD 60.04 billion in 2025, estimated at USD 73.55 billion in 2026, and projected to reach USD 372.96 billion by 2034, registering a robust CAGR of 22.50% during the forecast period from 2026 to 2034.
- Primary Growth Drivers: Significant decrease in hardware and sensor equipment costs; heavy R&D investments by leading automotive and tech companies; development of smart cities; and increasing global demand for connected vehicles utilizing IoT to combat traffic congestion. Key restraints include strict government regulations, safety concerns, public misconceptions regarding employment impact, and intense competition among market players.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (2025 Position) | Fastest-Growing Segment |
|---|---|---|
| By Application | Taxi & Ride-Hailing (dominates market share driven by rapid urbanization and rising disposable incomes) | Taxi Fleets & Heavy-Duty Autonomous Trucks |
| By Component | Hardware / Sensor Systems (essential for mapping and environment tracking) | Software Solutions (witnessing rapid growth due to worldwide digital transformation and AI algorithm upgrades) |
| By Automation Level | Level 3 Cars (dominate current adoption due to lower risk profiles and balanced human oversight) | Level 4 & Level 5 Fully Autonomous Systems (steadily capturing future market share) |
| By Region | North America & Europe (represent over half of the global market share supported by early model releases and active auto-industry developments) | Asia-Pacific (projected for high expansion driven by smart city initiatives and technology investments) |
Major Market Players & Market Structure
Market Structure: A highly competitive, technology-intensive ecosystem blending traditional automotive original equipment manufacturers (OEMs) with software giants and ride-sharing networks investing heavily in autonomous driving (FSD) suites.
Key Companies: Uber Technologies Inc., Daimler AG, Toyota Motor Corp, Tesla Inc., Google Inc. (Waymo), Nissan Motor Co. Ltd., Volvo Cars, Volkswagen AG, General Motors Company (GM), and BMW.
 Download Free Sample Report
Global Self-Driving Cars Market Size
The global self-driving cars market size was valued at USD 60.04 billion in 2025 and is anticipated to reach a valuation of USD 73.55 billion in 2026, from USD 372.96 billion by 2034, growing at a CAGR of 22.50% during the forecast period from 2026 to 2034.
A self-driving car, or autonomous vehicle, is a vehicle that uses sensors, cameras, and artificial intelligence to travel safely without a human driver. This field represents a fundamental transformation in mobility where transportation shifts from individual asset ownership to service based models enabled by machine perception and decision making algorithms. According to the World Health Organisation, approximately 1.19 million people die annually from road traffic crashes, creating an urgent public health imperative that autonomous safety systems aim to address through elimination of human error, which contributes to over 90 per cent of accidents. As per the International Transport Forum, global urban passenger travel demand is projected to increase by 75% over a 35-year period to 2050, accelerating infrastructure requirements and environmental strain. As per the United Nations Department of Economic and Social Affairs, 68 percent of the world population will reside in urban areas by 2050, intensifying pressure on municipal infrastructure to integrate intelligent transport systems that optimize road utilization and reduce parking demands. Furthermore, according to the International Energy Agency, the transport sector accounts for 23% of global energy-related carbon dioxide emissions, with its total greenhouse gas emissions expanding at an average rate of 1.7% annually.
MARKET DRIVERS
Critical Road Safety Imperatives Accelerating Regulatory Support
Government agencies worldwide are increasingly recognizing autonomous vehicle technology as an essential tool, which is among the major growth factors of the self driving car market. They view it as a way to address persistent road safety crises that conventional measures have failed to resolve adequately. According to the National Highway Traffic Safety Administration, final data shows 40,901 fatalities occurred on US roads in 2023, representing a 4.3% decrease compared to the previous year. As per the European Commission, around 20,400 people were killed in road crashes across the EU in 2023, signalling a flatlining trend in several member states. According to Japan's National Police Agency, total traffic fatalities among citizens aged 65 and over reached 1,465 in 2023, accounting for 54.7% of all road deaths. Unlike consumer convenience features safety benefits provide compelling justification for public investment regulatory accommodation and liability framework development that purely commercial applications cannot achieve independently. Governments view autonomous vehicles as infrastructure level interventions comparable to seatbelt mandates or drunk driving laws rather than optional luxury technologies. This reframing transforms policy discussions from permission-based approval to proactive enablement strategies, including dedicated testing zones, updated traffic codes and insurance reforms designed specifically for driverless operations, accelerating deployment timelines beyond pure market demand signals alone.
Logistics Labour Shortages Creating Commercial Viability Pathways
Chronic driver shortages in freight transportation create immediate economic incentives for autonomous trucking adoption and contribute to the expansion of the self-driving car market. This financial drive exists independently of passenger vehicle maturity or consumer acceptance barriers. According to the American Trucking Associations, the US trucking industry faces a driver deficit that is projected to grow to 160,000 by 2030 due to an aging workforce and high turnover rates. As per the International Road Transport Union, Europe experiences a shortage of more than 502,000 professional truck drivers, creating a severe operational gap across the continent. According to China's Ministry of Public Security, the volume of newly issued driving licenses nationwide fell by about 16% over a two-year period, dropping to 20.51 million annual additions. This productivity advantage translates directly to cost per mile reductions that offset higher vehicle acquisition costs within 2 to 3 years, creating clear return on investment calculations for fleet operators. Unlike robotaxis that require complex urban navigation and passenger trust-building, highway autonomy addresses defined operational domains with predictable economics. This predictability enables commercial deployment while the technology continues maturing for more challenging environments.
MARKET RESTRAINTS
Sensor Performance Degradation in Adverse Weather Conditions
Autonomous vehicle perception systems experience significant reliability reductions during precipitation, fog, snow, and low visibility scenarios, which hinders the growth of the self-driving cars market. This creates safety gaps that prevent all-weather operational readiness required for commercial viability. As per empirical closed-course evaluations, automotive lidar point cloud density declines by 30% to 60% under moderate to heavy rain conditions due to atmospheric attenuation and beam scattering. As per the AAA Foundation for Traffic Safety, automatic emergency braking systems failed to prevent a collision in 33% of closed-course test runs during simulated rainfall at 35 miles per hour. According to the Insurance Institute for Highway Safety, driverless commercial robotaxis demonstrate a 68% lower crash rate than human driver benchmarks on public urban roads. Camera systems suffer from lens occlusion and reduced contrast, while radar experiences multipath interference from wet surfaces, creating sensor fusion conflicts that confidence scoring algorithms struggle to resolve reliably. These physical limitations cannot be solved through software updates alone, requiring hardware redesigns, protective enclosures, and redundant sensing modalities that add cost, weight, and complexity. Until perception systems achieve human-equivalent performance across all environmental conditions, geographic deployment remains restricted to favourable climates. This constraint limits the addressable market size and revenue potential for operators who invested in year-round service expectations.
Prohibitive Unit Economics Preventing Mass Market Affordability
Current autonomous vehicle system costs remain substantially above viable price points for consumer purchase or profitable ride-hailing operations, which further hampers the expansion of the self-driving car market. Without massive subsidies, this cost barrier prevents the realisation of scalable business models. According to the National Highway Traffic Safety Administration, autonomous vehicle developers submit standardised event data to satisfy national mandatory standing general order reporting timelines. As per sources, mass deployment of automotive-grade lidar units continues accelerating via deep hardware integration partnerships across prominent Chinese passenger vehicle manufacturing platforms. Unlike smartphones, where component costs dropped exponentially through consumer volume scaling, automotive safety requirements mandate expensive validation processes and redundant architectures that resist commoditization pressures. This economic reality confines deployments to well-capitalised companies willing to absorb losses indefinitely while waiting for component cost curves to intersect with viable fare structures, potentially delaying widespread adoption by decades or more beyond optimistic industry projections.
MARKET OPPORTUNITIES
Last Mile Delivery Automation Unlocking New Revenue Streams
Autonomous delivery robots and vans present a commercially viable, near-term opportunity for the self-driving car market. By targeting e-commerce fulfillment cost pressures, they bypass passenger safety complexities and steep regulatory hurdles. According to research, last-mile delivery represents up to 53% of total logistics and shipping costs, while a study indicates that businesses utilizing AI-powered routing and urban fulfillment centers can slash these delivery costs by 30%. According to the National Highway Traffic Safety Administration (NHTSA), Nuro received a landmark regulatory exemption in February 2020 allowing its custom cargo vehicle, the R2, to legally operate without mandated human-driven safety hardware like mirrors or windshields. As per official operational data from Starship Technologies, their autonomous sidewalk delivery robot fleet surpassed 8 million commercial deliveries globally, expanding its total footprint across international university campuses and neighborhood corridors. Retailers like Walmart and Kroger have deployed autonomous delivery pilots in 15 US markets, responding to consumer expectation for rapid fulfillment while managing labor cost inflation. Unlike passenger robotaxis requiring Level 4 capability in unpredictable urban traffic, delivery bots operate in geofenced low-speed zones with simplified perception requirements, enabling faster deployment cycles and lower capital intensity. This segment creates stepping stone toward full autonomy generating revenue data and public acceptance incrementally while technology matures for more demanding applications. Successful delivery operations also build mapping infrastructure and fleet management expertise transferable to future passenger services, creating compound strategic advantages for early movers establishing operational footprints now.
Mobility as a Service Integration Transforming Urban Transportation
Autonomous vehicles enable a fundamental restructuring of urban mobility away from private ownership, which opens the door for the expansion of the self-driving car market. They shift cities toward integrated multimodal service networks that optimise infrastructure utilisation and accessibility. According to the Institute for Transportation and Development Policy (ITDP), urban regions can achieve an 80% absolute reduction in transportation-related carbon dioxide emissions by seamlessly combining vehicle automation, widespread electrification, and extensive ride-sharing networks. As per sources, the firm behind the integrated mobility app Whim suffered severe losses and formally filed for bankruptcy protection, after which its core technology assets were acquired by a separate mobility platform. Municipal governments increasingly view autonomous mobility as public infrastructure rather than a private product, creating opportunities for public-private partnerships subsidizing deployment in exchange for equity access and data sharing agreements. Transit agencies facing budget constraints see autonomous shuttles as a solution to unprofitable fixed-route services in low-density suburbs, extending coverage without proportional cost increases. This institutional buyer base provides a stable demand foundation less susceptible to consumer sentiment volatility while embedding autonomous vehicles into long-term urban planning frameworks, ensuring sustained deployment regardless of retail market fluctuations or technology hype cycles affecting private sector investment decisions.
MARKET CHALLENGES
Liability Framework Ambiguity Creating Legal Uncertainty
The absence of clear legal standards assigning responsibility when autonomous vehicles cause harm creates insurmountable risk exposure, which obstructs the growth of the self driving cars market. This prevents insurers from underwriting policies and manufacturers from deploying them commercially. According to the RAND Corporation, the gradual transition toward autonomous driving systems shifts liability regimes away from conventional driver negligence and increasingly exposes vehicular manufacturers to heightened product liability risks. As per the European Union's revised Product Liability Directive (PLD), courts can legally presume a product is defective if a technical or scientific complexity makes it excessively difficult for a claimant to prove causation, alleviating traditional evidentiary burdens for plaintiffs in autonomous vehicle incidents. According to Swiss Re Institute, high tech embedded systems, lasers, and digital sensors elevate average collision repair costs for advanced vehicles, driving motor insurers to adjust risk models and premium pricing structures. Without legislative clarification, manufacturers face unlimited contingent liabilities that balance sheets cannot support, forcing conservative deployment strategies limiting operational domains and times to minimize exposure. Some jurisdictions enacted no fault compensation schemes, but funding mechanisms and coverage limits remain contested, creating a patchwork regulatory landscape complicating interstate and international operations. This legal vacuum persists despite years of discussion because stakeholders disagree fundamentally on whether autonomous vehicles should be regulated as products, services, or hybrid entities with unique liability allocation rules reflecting neither traditional automotive nor software industry precedents.
Cybersecurity Vulnerabilities Threatening Public Trust and Safety
Connected autonomous vehicles represent attractive targets for malicious actors seeking to disrupt transportation networks, steal personal data, or weaponise vehicles, causing physical harm at scale, which is a severe challenge to the self-driving car market. According to Upstream Security, recorded cyber incidents targeting connected automotive ecosystems surged 380% since 2020, with threat actors shifting toward large-scale attacks that impact entire mobility fleets. As per research involving UC San Diego engineering faculty, physical adversarial stickers and patches applied directly onto street stop signs can manipulate deep learning visual classification models into completely misidentifying the safety signs. According to the FBI’s Internet Crime Complaint Centre (IC3), overall domestic cybercrime financial losses escalated by 33% to an unprecedented $16.6 billion, primarily propelled by massive volumes of phishing, spoofing, and investment fraud complaints. Unlike traditional cybersecurity breaches affecting data confidentiality, autonomous vehicle compromises endanger human life directly, raising stakes beyond financial losses to existential safety concerns. Manufacturers must invest heavily in security by design, penetration testing and over-the-air update capabilities, adding development costs and validation complexity while acknowledging that perfect security is theoretically impossible against determined adversaries. A single high-profile incident involving a hacked autonomous vehicle could trigger public backlash and regulatory moratoriums, setting back industry progress by years regardless of statistical safety superiority versus human drivers, demonstrating how asymmetric threat landscapes constrain deployment velocity independent of technical maturity.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 22.50% |
| Segments Covered | By Application, Component, Automation Level, and region. |
| Various Analyses Covered | Global, Regional & Country Level Analysis, Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Regions Covered | North America, Europe, APAC, Latin America, Middle East & Africa |
| Market Leaders Profiled | Uber Technologies Inc., Daimler AG, Toyota Motor Corp, Tesla Inc., Google Inc., Nissan Motor Co. Ltd, Volvo Cars, Volkswagen AG, General Motors Company (GM), BMW, and Others. |
SEGMENTAL ANALYSIS
By Application Insights
Ride Hailing
The ride hailing segment dominated the self driving cars market and accounted for a substantial share in 2025. This dominance of the segment was driven by its established operational infrastructure and immediate alignment with the unit economics required for autonomous commercialisation. One of the major reasons behind this dominance is the existing network effect and user base that allow autonomous fleets to integrate seamlessly into platforms with millions of daily active users without requiring new customer acquisition costs. According to Uber Technologies Inc., its platform facilitated approximately 30 to 33 million trips per day on average throughout 2024, recording strong global trip volume and consumer utilisation. As per Lyft, its early autonomous vehicle partnership with Motional introduced over 100,000 riders to self-driving technology through public operations in Las Vegas. According to sources, distributing vehicle capital expenditure across a centralized fleet allows robotaxis to achieve dramatically higher asset utilization rates compared to the 5% average utilization seen in privately owned personal cars. Regulatory frameworks in Arizona, California, and Texas specifically accommodate commercial passenger transport, creating legal pathways unavailable to private autonomous vehicles. This regulatory first-mover advantage, combined with platform scale, creates insurmountable barriers for standalone autonomous taxi startups lacking distribution networks, forcing industry consolidation around established mobility platforms that control customer relationships and dispatch optimization algorithms essential for profitable operations.
Fueling this segment's ongoing lead is the ability to monetize data and optimize fleet positioning through real-time demand prediction, reducing deadhead miles and improving asset productivity. As per studies, the autonomous vehicle fleet has completed more than 10 million paid rides cumulatively since launching public operations in its primary regional markets. Machine learning models trained on years of historical trip data enable predictive prepositioning of autonomous vehicles, anticipating demand surges before they occur, minimising passenger wait times and maximising revenue generation per vehicle hour. As per Cruise LLC, the company focused on restarting its driverless fleet testing in multiple metropolitan hubs to rebuild consumer trust following a voluntary suspension of its public operations. Fleet operators leverage this intelligence to right-size vehicle deployment, matching supply to spatial-temporal demand patterns, avoiding oversaturation during low demand periods while ensuring availability during peaks. This operational efficiency translates directly to margin improvement, enabling fare structures competitive with human drivers despite higher vehicle costs. Furthermore, aggregated anonymized trip data creates valuable secondary revenue streams sold to urban planners, retailers and advertisers seeking mobility insights, creating diversified income sources beyond passenger fares alone, strengthening business model resilience against demand volatility.
Heavy Duty Trucks
The heavy-duty trucks segment is on the rise and is expected to be the fastest-growing segment in the market by witnessing a CAGR of 42.3% over the forecast period. This swift expansion of the segment is fuelled by acute labor shortages and superior highway automation economics. A key growth factor is the structural driver deficit, creating immediate operational necessity rather than discretionary technology adoption, as seen in passenger applications. According to TuSimple, autonomous trucks can navigate continuously for up to 20 hours daily compared to the 11-hour legal daily driving limits enforced for human operators. Highway environments present more predictable perception challenges than urban streets, enabling earlier commercial viability with current sensor technology. Shippers facing service failures and rate inflation willingly pay premiums for guaranteed capacity, creating demand pull independent of technology perfection. This B2B value proposition based on measurable ROI contrasts sharply with consumer applications requiring behavioural change acceptance, enabling faster deployment cycles and revenue generation while passenger autonomy continues maturing through extended testing phases.
Growth in this segment is propelled by regulatory harmonization across interstate commerce corridors, creating unified operational frameworks absent in fragmented municipal passenger vehicle jurisdictions. As per research, 28 US states passed legislation explicitly allowing "driver-out" autonomous vehicle operations, establishing individual state-level frameworks to govern driverless commercial deployment. Unlike city-by-city permitting processes requiring separate negotiations, safety cases, and fees for each robotaxi geography, interstate trucking benefits from existing federal oversight mechanisms adaptable to autonomous operations through rulemaking rather than new legislation. Industry associations successfully lobbied for exemption processes allowing longer combination vehicles and extended operating hours for autonomous trucks recognizing productivity benefits justify regulatory accommodation. Insurance frameworks also matured faster for commercial freight where actuarial data exists versus novel passenger liability scenarios enabling underwriting at viable rates. This regulatory tailwind reduces deployment friction and capital uncertainty, attracting institutional investment necessary for fleet scale expansion, accelerating market growth beyond technology development timelines alone.
By Component Insights
Hardware
The hardware segment led the self-driving car market and captured a significant share in 2025. Factors such as high unit costs and physical integration requirements preceding software functionality contributed to the leading position of this segment. This segment includes sensors, computing platforms, and actuators. The main driver is the substantial bill of materials required for redundant perception and control systems meeting automotive safety integrity levels. According to studies, average selling prices for long-range lidar hardware fluctuate between $450 and $1,000 per sensor depending on regional supplier manufacturing efficiencies, keeping overall multi-sensor system costs lower than legacy estimates. As per NVIDIA pricing announcements, next-generation mass production computing modules enter regional commercial supply chains starting at a base price point of $399 per unit. Unlike consumer electronics, where hardware commoditises rapidly, automotive safety requirements mandate specialised components with extended validation cycles limiting supplier competition and sustaining premium pricing. Redundancy architectures doubling critical components for fail operational capability further inflate hardware content per vehicle. Manufacturing complexity involving precision optics, semiconductor fabrication, and electromechanical assembly creates high barriers to entry, concentrating value among tier one suppliers and specialized technology firms. Even as software defines differentiation, physical hardware remains a prerequisite enabler, capturing the majority of current market spend as fleets build out vehicle inventories before transitioning to software-dominated recurring revenue models in mature deployment phases.
The foremost factor securing this segment's leading position is the continuous evolution of sensor technologies, preventing commoditization through generational upgrades and specification escalation. As per research, the newly engineered REV8 OS digital sensor architecture incorporates a specialized silicon chip design that introduces native color-sensing capabilities directly into the 3D lidar point cloud. Luminar Technologies reveals that the manufacturing company expanded its operations by initiating series production of its specialised 1550-nanometer long-range lidar systems for automotive integration on high-volume consumer vehicle lines. According to sources, vehicular vision systems increasingly pivot toward higher resolution 8-megapixel primary camera sensors to capture high-fidelity physical environment data for autonomous visual processing. Radar technology transitioned from mechanical scanning to solid-state imaging arrays, improving angular resolution while reducing size but increasing unit cost through semiconductor content additions. This technological treadmill prevents hardware stabilization at commodity price points as each generation introduces new capabilities justifying premium valuations. Suppliers investing in R&D recoup development expenses through early adopter pricing before competitors catch up, maintaining healthy margins throughout the product lifecycle. Fleet operators accept upgrade costs as necessary investments in safety and operational capability rather than optional enhancements, embedding sustained hardware demand within autonomous vehicle total cost of ownership calculations.
Software and Services
The software and services segment is likely to experience the fastest CAGR of 38.7% from 2026 to 2034 due to subscription business models and continuous improvement imperatives. Perpetual licensing is giving way to recurring revenue structures as the key growth factor. Consequently, this shift aligns supplier incentives with fleet success and ensures more predictable cash flows for operators. According to Mobileye Global Inc.'s consolidated financial reports, total aggregate annual revenues for the enterprise declined by approximately 20% year-over-year to settle at $1.654 billion. Cloud-based simulation and validation services charge usage-based pricing scaling with development intensity rather than fixed seat licenses, enabling startups to access enterprise-grade tools without prohibitive upfront investments. Over-the-air update capabilities allow feature additions and performance improvements post sale creating ongoing monetisation opportunities beyond the initial vehicle transaction. This business model evolution attracts software companies traditionally excluded from automotive supply chains, bringing agile development practices and cloud native architectures that accelerate innovation velocity while diversifying revenue bases against hardware cyclicality and inventory risks.
Multiple factors accelerate this growth, including the escalating complexity of edge case resolution requiring continuous data processing, annotation and model training that exceeds onboard compute capacities. As per Scale AI, autonomous vehicle developers spent over 2 billion dollars on data labelling and management services in 2024, representing a 35 per cent annual increase as perception algorithms encountered diminishing returns from simple dataset expansion necessitating sophisticated curation and synthetic generation techniques. As per Amazon Web Services, surging enterprise cloud infrastructure utilization and massive graphic processing unit cluster demands propelled the platform's total annual revenue to reach $330 billion. Remote assistance services employing human teleoperators to handle disengagements create hybrid labor technology offerings charging per intervention or hourly rates, supplementing pure automation with scalable human oversight during technology maturation. These service layers abstract complexity from fleet operators, enabling focus on core transportation business rather than AI research, democratising access to autonomous capabilities while creating sticky vendor relationships through data lock-in and workflow integration that resist switching even when alternative technologies emerge.
By Automation Level Insights
Level 4
In 2025, the level 4 segment held the majority share in the self driving cars market because of its optimal balance between capability and feasibility within defined operational domains. Geofenced operations provide the primary driver due to their regulatory and technical tractability. This targeted method delivers a genuine driverless value proposition without getting bogged down by the infinite edge cases of universal Level 5 autonomy. According to California Department of Motor Vehicles metrics, permitted autonomous vehicles logged over 4 million total test miles on public state roads during the 2024 reporting period, experiencing a temporary volume contraction compared to the preceding year. The Beijing High-Level Automated Driving Demonstration Zone indicates that municipal authorities deployed extensive intelligent roadside computing and network infrastructure across a continuous 600-square-kilometre zone to support multi-company autonomous driving operations. Unlike Level 3 conditional automation, requiring human fallback readiness and creating liability ambiguity and monitoring burden, Level 4 systems assume full responsibility within operational design domains, enabling true mobility service models without occupant engagement requirements. Investors favour Level 4 because it represents an achievable milestone with a clear path to revenue generation within 3- to 5 year horizons versus speculative Level 5 timelines extending decades. Fleet operators can quantify return on investment based on known geographic coverage and demand density, reducing uncertainty that plagued earlier autonomy hype cycles. This pragmatic scoping enables focused engineering resource allocation and measurable progress tracking, attracting sustained capital commitment through market downturns that eliminated less disciplined competitors pursuing unconstrained autonomy visions.
The leading position of this segment is bolstered by the emergence of standardized operational design domain definitions enabling interoperable safety certification and insurance underwriting frameworks. As per UL Standards & Engagement, the ANSI/UL 4600 standard outlines formal safety case architectures and goal-oriented hazard assessments to evaluate fully autonomous products operating completely independent of human safety driver supervision. According to Swiss Re Institute, commercial liability insurance markets encounter decelerating premium growth curves while scaling risk models to match evolving automated and commercial vehicle fleet technologies. Geofencing technologies matured enabling dynamic operational boundaries adjustable in real time based on weather traffic construction and special events expanding serviceable area without compromising safety guarantees. Mapping providers like HERE and TomTom developed HD map formats specifically supporting Level 4 localisation and planning, reducing integration complexity for new entrants. This ecosystem standardisation lowers barriers to entry while raising safety floors, preventing race-to-the-bottom dynamics that characterised early testing periods. Insurers can price risk based on operational domain characteristics rather than company-specific factors, creating liquid market for autonomous vehicle coverage essential for fleet financing. Regulators gain confidence approving expansions when standardized validation demonstrates equivalent safety across applicants, accelerating deployment velocity through reduced review cycles and predictable approval timelines.
Level 3
The Level 3 segment is expected to exhibit a noteworthy CAGR of 54.2% during the forecast period, owing to premium passenger vehicle integration and regulatory approvals enabling hands-free highway driving. Growth starts with consumer demand for advanced driver assistance features. They transition users from Level 2 to complete autonomy while keeping legal responsibility clear for manufacturers. According to Mercedes-Benz product declarations, the enterprise upgraded its Level 3 Drive Pilot system capabilities to legally support conditionally automated highway cruising velocities up to 95 kilometers per hour on domestic motorways. As per research, aggregate international new light-vehicle sales volumes are expected to reach 89.6 million total units, reflecting a conservative annual recovery trend across primary manufacturing markets. Consumers perceive tangible value in hands-free commuting, reducing fatigue during monotonous highway driving while retaining ownership flexibility and unrestricted geographic operation outside activation conditions. This value proposition resonates strongly with premium buyers willing to pay technology premiums, creating a profitable niche for OEMs funding continued autonomy R&D through near-term revenue streams rather than awaiting distant Level 5 monetisation horizons.
The prominence of this segment is further reinforced by evolving regulatory frameworks that establish clear liability transfer protocols, enabling manufacturer confidence in marketing conditional automation features. As per the United Nations Economic Commission for Europe (UNECE), an official regulatory amendment to UN Regulation No. 157 entered into force in January 2023 to expand the maximum permissible motorway automated driving velocity up to 130 kilometers per hour. The insurance industry developed specific Level 3 policy endorsements clarifying coverage transitions between human and automated modes, eliminating ambiguity that previously deterred manufacturers from activating available hardware capabilities. Consumer education campaigns by automotive associations improved understanding of system limitations, reducing misuse incidents and warranty claims associated with mode confusion. Dealer training programs ensured sales staff accurately communicated operational design domains, preventing overpromising that could trigger regulatory backlash or litigation. This coordinated stakeholder alignment created a virtuous cycle where regulatory clarity enabled product launches, which generated real-world validation data supporting further regulatory expansion, accelerating adoption velocity beyond technology development pace alone.
REGIONAL ANALYSIS
North America Market Analysis
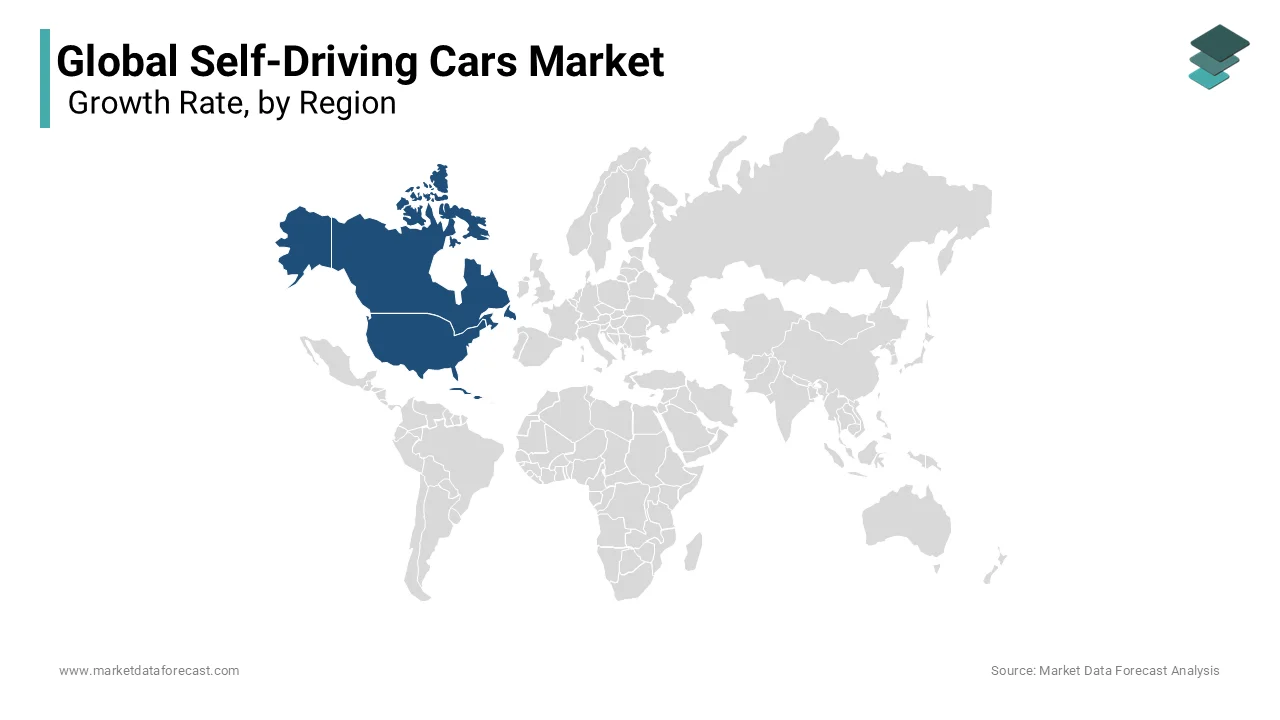
North America was the top performer in the global self-driving cars market and captured a 42.6% share in 2025. This prominence of the region's market was propelled by a permissive regulatory environment, deep capital markets, and technology company concentration in Silicon Valley and Arizona. The region’s market status reflects first-mover advantage in commercial robotaxi deployments, with Waymo Cruise and Zoox operating paid services across multiple metropolitan areas, accumulating billions of testing miles and establishing operational playbooks exported globally. According to the National Conference of State Legislatures (NCSL), 29 US states and Washington, D.C. have formally enacted structural autonomous vehicle legislation to establish targeted regional regulatory frameworks for driverless testing and operations. PitchBook indicates that global autonomous driving technology startups received a surging $2.9 billion in private venture funding during a single high-growth quarter in 2024, representing the highest vertical investment level since late 2021. Federal guidance documents provide nonbinding but influential safety assessment frameworks enabling innovation without prescriptive standards stifling development. However, regulatory divergence between states creates compliance complexity for multistate operators requiring separate permits, insurance, and reporting. Labour opposition from Teamsters and taxi unions influences policy debates, particularly in Northeast markets, limiting deployment geography despite technological readiness. Nevertheless, the region maintains leadership through a combination of capital availability, regulatory experimentation tolerance and consumer technology adoption propensity, creating self reinforcing ecosystem advantages difficult for other regions to replicate quickly despite catching efforts elsewhere.
Asia Pacific Market Analysis
Asia Pacific followed closely behind in the global market and occupied a 33.1% share in 2025. This growth of the APAC market was fuelled by government-led strategic initiatives, dense urban environments, and strong domestic technology champions in China, Japan, and South Korea. The region’s market status reflects state-directed development models where autonomous vehicles serve national industrial policy objectives, including technological sovereignty, ageing society mobility solutions and smart city infrastructure integration. According to China’s Ministry of Industry and Information Technology (MIIT), regional transportation authorities have opened over 57,000 kilometers of public demonstration roads and issued more than 20,000 testing and pilot licenses nationwide to accelerate automated vehicle ecosystems. As per RoAD to the L4 project framework in Japan, ministries and regional municipalities are actively cooperating to deploy Level 4 driverless autonomous mobility public transport services across 50 distinct domestic locations by 2025. Unlike North America’s private sector led approach, Asian governments provide direct subsidies for infrastructure buildout and regulatory sandboxes de risking private investment while ensuring alignment with national priorities. However, geopolitical tensions restrict technology transfer and cross-border collaboration, fragmenting the regional ecosystem despite geographic proximity. Demographic pressures create urgent domestic demand, ensuring sustained policy support regardless of global market sentiment fluctuations affecting investor-dependent Western counterparts.
Europe Market Analysis
Europe maintains a significant presence in the global self-driving cars market because of regulatory leadership, a safety-first approach, and strong automotive OEM integration rather than tech company disruption. The region’s market status reflects traditional automotive industry strength adapting existing manufacturing and supply chain capabilities toward autonomous mobility while prioritizing standardized safety certification over rapid deployment experimentation. According to the European Commission, the EU AI Act classifies autonomous driving technology as a high-risk system, forcing developers to meet strict data governance, cybersecurity, and risk management requirements before entering the market. As per the European Automobile Manufacturers' Association (ACEA), the European automotive sector serves as the region's top investor in innovation by spending approximately €73 billion annually on comprehensive research and development. German, French and British regulators collaborated on mutual recognition agreements for testing permits, reducing cross border friction for pan-European validation. Strong data privacy protections under GDPR shape technical architectures emphasizing on board processing and anonymization limiting cloud dependent approaches common elsewhere. Public scepticism toward surveillance technologies constrains data collection scope, slowing algorithm training compared to less regulated regions. However, rigorous safety standards create global credibility for European certifications, enabling export competitiveness in safety conscious markets. The region trades deployment speed for systemic robustness, betting that eventual mass adoption requires trust foundations built through demonstrable safety rather than first mover advantages potentially undermined by high-profile incidents.
Latin America Market Analysis
Latin America grew moderately in the global self-driving cars market. The region’s activity is concentrated in Brazil, Mexico, and Chile, driven by mining, logistics automation, and selective urban pilot programs rather than broad consumer deployment. The region’s market status reflects emerging market constraints including infrastructure deficits regulatory uncertainty and capital scarcity limiting autonomous vehicle applications to controlled industrial environments and geofenced tests. According to studies, initial driverless vehicle deployment is concentrated within highly controlled commercial environments, such as the introduction of autonomous trucks for internal pulp transport at Portocel. As per Anglo American, the mining enterprise arranged the deployment of Komatsu's FrontRunner Autonomous Haulage System across a fleet of 62 ultra-class haul trucks at its Los Bronces open-pit copper mine in Chile. Limited domestic technology development creates dependency on foreign suppliers, increasing vulnerability to currency fluctuations and trade barriers. However, resource extraction and agricultural logistics create natural niches where automation economics work despite broader market immaturity. Government interest in smart city initiatives creates occasional pilot funding but sustained deployment awaits infrastructure improvements and regulatory maturation currently progressing slower than technology availability suggests possible.
Middle East and Africa Market Analysis
The Middle East and Africa region is predicted to expand significantly in the global self-driving cars market from 2026 to 2034. Within this region, activity is heavily concentrated in the UAE, Saudi Arabia, and Israel. This growth is being driven by sovereign wealth investments, smart city mega-projects, and defense technology spillovers. The region’s market status reflects top down development models where autonomous mobility serves national vision strategies and futuristic branding rather than organic market demand or grassroots innovation ecosystems. According to the Dubai Roads and Transport Authority (RTA), municipal transport roadmaps aim for 25% of all transportation trips to be completely autonomous by 2030, with early public robotaxi trial fleets already passing 4 million cumulative kilometres traveled. As per the Saudi Public Investment Fund (PIF), the sovereign fund established Tasaru Mobility Investments to accelerate local supply chain development and manufacture localized future mobility components for its electric vehicle and autonomous sectors. Gulf states leverage sovereign capital to attract global operators offering subsidized deployments, regulatory fast tracks and infrastructure buildouts unavailable elsewhere. However, limited local talent pools and extreme climate conditions create operational challenges requiring technology adaptations not needed in temperate regions. Development remains enclave-focused within wealthy Gulf states with minimal spillover to the broader African continent, where basic infrastructure deficits preclude autonomous vehicle relevance for the foreseeable future despite occasional pilot announcements generating media attention disproportionate to actual deployment scale.
COMPETITIVE LANDSCAPE
Competition in the self driving cars market features intense rivalry between well capitalized technology companies traditional automotive manufacturers and specialized startups each pursuing distinct paths toward commercial viability and technological leadership. Tech giants leverage deep pockets data advantages and software expertise developing full stack solutions targeting robotaxi and logistics applications while accepting extended pre revenue periods betting on winner take all dynamics. Legacy automakers integrate autonomous capabilities incrementally through ADAS progressions monetizing intermediate levels while funding long term R&D through existing vehicle sales profits avoiding pure play cash burn risks. Specialized startups focus on niche applications like mining agriculture or last mile delivery where constrained environments enable earlier commercialization generating revenue and validation data transferable to broader markets later. Competition intensifies around talent acquisition regulatory relationships and strategic partnerships as differentiators beyond pure technical capability since safety validation requires years of accumulated operational experience difficult to replicate quickly. Consolidation accelerates as capital markets demand clearer paths to profitability forcing mergers acquisitions and strategic alliances among players lacking sufficient scale or funding to continue independent development indefinitely. However fragmentation persists due to diverse application requirements regional regulatory variations and multiple viable technological approaches preventing single dominant standard emergence enabling varied business models to coexist serving specific segments within this complex evolving global landscape characterized by high uncertainty and transformative potential simultaneously.
KEY MARKET PLAYERS
Some of the key players in the global self-driving cars market include
- Uber Technologies Inc.
- Daimler AG
- Waymo LLC
- Mobileye Global Inc
- Toyota Motor Corp
- Aurora Innovation Inc
- Tesla Inc.
- Google Inc.
- Nissan Motor Co. Ltd
- Volvo Cars
- Volkswagen AG
- General Motors Company (GM)
- BMW.
Top Players In The Market
- Waymo LLC maintains extensive involvement in the self driving cars market through commercial robotaxi services operating across multiple US metropolitan areas including Phoenix San Francisco and Los Angeles. The company recently expanded service coverage to include airport transfers and highway driving demonstrating technological maturity beyond geofenced urban cores. Waymo strengthened market position by launching freight delivery partnerships with logistics firms diversifying revenue streams beyond passenger transport while leveraging same autonomous driving stack. Their recent actions include opening new maintenance facilities and securing additional vehicle supply agreements with Hyundai and Geely ensuring fleet scalability. These initiatives demonstrate operational excellence and strategic diversification creating sustainable competitive advantages through proven safety records accumulated over billions of testing miles establishing industry benchmarks for regulatory approval processes and public trust building essential for long term deployment success globally.
- Mobileye Global Inc contributes significantly to the self driving cars market through advanced driver assistance systems and autonomous driving technology platforms integrated into millions of production vehicles worldwide. The company recently launched EyeQ6 chip family delivering enhanced processing performance for Level 3 and Level 4 applications while maintaining power efficiency critical for automotive thermal constraints. Mobileye strengthened market position through REM mapping service generating crowdsourced high definition maps from customer fleet data reducing dependency on dedicated mapping vehicles. Recent actions include expanding SuperVision deployments with Volkswagen Porsche and Audi creating scalable revenue model bridging ADAS and full autonomy. These strategies leverage massive installed base for continuous improvement while positioning company as essential enabler for OEMs pursuing autonomous capabilities without building entire technology stacks independently enabling broader ecosystem participation and sustained relevance across automation levels.
- Aurora Innovation Inc plays vital role in self driving cars market focusing exclusively on autonomous trucking applications addressing acute freight industry labor shortages through highway automation solutions. The company recently achieved driverless commercial operations on Texas interstate corridors connecting major logistics hubs validating business model viability and operational readiness for paying customers. Aurora strengthened market position through partnerships with Volvo Trucks and PACCAR integrating proprietary hardware directly into production vehicles reducing retrofit complexity and improving reliability. Recent actions include expanding terminal network and securing long term freight contracts with Uber Freight and Schneider National demonstrating carrier confidence. These initiatives prioritize B2B value creation over consumer applications enabling earlier path to profitability through measurable ROI propositions while accumulating highway driving data transferable to future passenger vehicle development creating compound strategic advantages in autonomous freight transportation segment.
Top Strategies Used By Key Market Participants
Key players in the self driving cars market employ vertical integration strategies controlling sensor hardware software stacks and fleet operations to ensure system optimization and capture full value chain margins rather than licensing components separately. Companies pursue strategic partnerships with established automakers leveraging manufacturing scale distribution networks and regulatory expertise while providing technology differentiation avoiding capital intensive vehicle production burdens. Geographic expansion follows corridor based deployment models concentrating resources on high demand routes achieving operational density before broadening coverage reducing per mile costs through utilization optimization. Business model diversification across passenger freight and data services spreads risk while creating cross segment synergies in technology development and operational learning. Continuous safety validation through simulation and real world testing builds regulatory credibility and public trust essential for deployment approvals and insurance underwriting at viable rates. Talent acquisition focuses on specialized AI robotics and safety engineering teams through competitive compensation and mission driven culture attracting scarce expertise critical for solving remaining technical challenges. Capital management balances aggressive R&D investment with disciplined spending extending runway through strategic fundraising joint ventures and selective monetization of intermediate technologies generating near term revenue while pursuing long term autonomy goals sustainably.
MARKET SEGMENTATION
This research report on the global self-driving cars market is segmented and sub-segmented into the following categories.
By Application
- Taxi
- Civil
- Public Transport
- Heavy Duty Trucks
- Ride Shares
- Ride Hail
By Component
- Hardware
- Software
- Services
By Automation Level
- Level 3
- Level 4
- Level 5
By Region
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East Africa