- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$87.73 BnMarket Estimate, 2026
$91.84 BnMarket Forecast, 2034
$132.42 BnCAGR, 2026–2034
4.68%Executive Summary: Europe Frozen Food Market
- Market Scope: Comprehensive regional analysis tracking frozen ready meals, fruits & vegetables, meat & poultry, seafood, bakery, and dairy products across offline and online distribution channels in major European country-level markets.
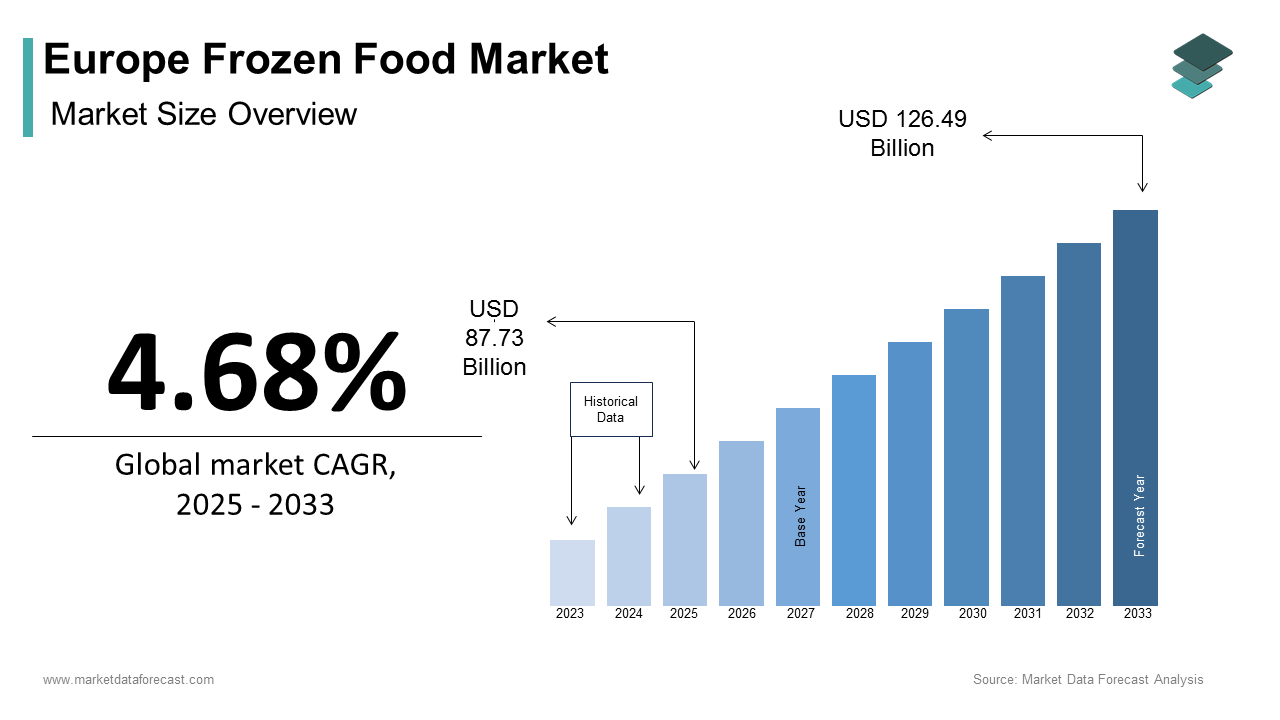
- Market Valuation: Valued at USD 87.73 billion in 2025, reaching USD 91.84 billion in 2026, and projected to expand to USD 132.42 billion by 2034, growing at a steady CAGR of 4.68% during the forecast period (2026–2034).
- Primary Growth Drivers: Rapid urbanization across Europe necessitating convenient meal solutions, shifting consumer preferences toward ready-to-eat and nutrient-rich frozen foods, and robust expansion into organic and plant-based frozen product lines. Key restraints include high energy costs and freezing technology expenses, maintenance challenges for smaller producers, and traditional consumer perceptions regarding nutritional value.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment / Focus Area | Key Insights & Trends |
|---|---|---|
| By Product | Frozen Ready Meals (45.3% share in 2025) & Fruits & Vegetables (Fastest CAGR at 6.2%) | Ready meals dominate due to urban time constraints and dual-income convenience needs; fruits & vegetables surge on health-conscious and organic trends. |
| By Distribution Channel | Offline Distribution (65.2% share in 2025) & Online Retail (Fastest CAGR at 8.5%) | Supermarkets/hypermarkets anchor reliable in-store visibility; online retail accelerates rapidly via e-commerce partnerships and home delivery subscription services. |
| By Region / Country | Germany (22.2% share in 2025) & United Kingdom (CAGR of 12.3%) | Germany leads via robust retail infrastructure and urban convenience demand; the UK expands rapidly driven by e-commerce hubs and plant-based innovations. |
Major Market Players & Market Structure
Market Structure: Highly competitive landscape balancing global food conglomerates (Nestlé, Unilever, McCain) with agile regional innovators focusing on sustainability, digital retail integration, and plant-based lines.
Key Companies: Nestlé S.A., McCain Foods Limited, Birds Eye Ltd., H.J. Heinz, Maple Leaf Foods Inc., ConAgra Foods Inc., Tyson Foods Inc., General Mills, BRF SA, Pinnacle Foods Inc., Mother Dairy Fruit & Vegetable Pvt. Ltd., Kraft Foods Group Inc., Ajinomoto Co. Inc., and Unilever PLC.
Europe Frozen Food Market Size
The Europe Frozen Food Market Size was expected to be worth USD 87.73 billion in 2025 and is anticipated to be worth USD 132.42 billion by 2034, up from USD 91.84 billion in 2026, growing at a CAGR of 4.68% during the forecast period.
Europe exhibits a mature consumption pattern driven by changing lifestyle dynamics and increasing urbanization across major economies. According to Eurostat, approximately 75% of households in Western European nations possess dedicated freezer appliances, indicating widespread infrastructure support for frozen food storage. European Commission data reveals that food waste in the European Union amounts to 88 million tonnes annually, with frozen foods demonstrating significantly lower spoilage rates compared to fresh produce due to their extended preservation capabilities. Consumer behavior studies conducted by the European Consumer Organisation indicate that 60% of shoppers prioritize time-saving solutions in meal preparation, reflecting the growing demand for convenient dietary options. Furthermore, the European Freezer Association states that the cold chain logistics network in Europe covers over 90% of retail outlets, ensuring consistent product quality from manufacturing to point of sale. These structural and behavioral factors create a robust foundation for the market while highlighting the essential role of frozen foods in reducing household food waste and supporting sustainable consumption patterns across the continent.
MARKET DRIVERS
Shifting Consumer Lifestyles and Demand for Convenience
Rapid urbanization and evolving work patterns across Europe have fundamentally altered consumer dining habits, which is a key factor driving the growth of the European frozen food market. The European Foundation for the Improvement of Living and Working Conditions reports that average working hours in countries like Germany and France exceed 40 hours per week, leaving limited time for traditional meal preparation. Consequently, households increasingly rely on ready-to-eat and ready-to-cook frozen meals that require minimal effort and time. Data from the European Institute for Gender Equality indicates that dual-income households now constitute over 65% of families in Northern Europe, further amplifying the need for quick culinary options. The rise of single-person households, which account for 34% of all households in the European Union as per Eurostat statistics, creates specific demand for portion-controlled frozen products that minimize waste. Younger demographics, particularly millennials and Generation Z consumers, prioritize convenience and variety, leading to increased adoption of international cuisine-inspired frozen meals. Survey results from the European Consumer Centre show that 55% of consumers under 35 years of age purchase frozen ready meals at least once a week. The integration of frozen foods into busy lifestyles is not merely a trend but a structural shift in dietary behavior. Retailers respond by expanding frozen food aisles and introducing premium gourmet options that cater to discerning tastes while maintaining ease of preparation. This convergence of time scarcity and culinary aspiration sustains robust growth in the convenience segment of the frozen food market.
Technological Advancements in Freezing and Preservation
Innovations in freezing technologies have significantly enhanced the quality and appeal of frozen food products, thereby overcoming historical perceptions of inferior taste and texture and contributing to the regional market expansion. Individual Quick Freezing technology allows producers to freeze each piece of food separately, preserving cellular structure and preventing clumping, which results in superior sensory experiences upon thawing. According to the European Food Safety Authority, modern freezing methods retain up to 90% of vitamins and minerals in vegetables and fruits, comparable to fresh counterparts when consumed shortly after harvest. Cryogenic freezing using liquid nitrogen has gained traction in premium segments, enabling ultra-rapid freezing that minimizes ice crystal formation and maintains original texture. According to research published in the European Journal of Clinical Nutrition, frozen fish and meat products exhibit negligible differences in protein quality and fatty acid profiles compared to fresh alternatives. Smart packaging innovations incorporating oxygen scavengers and moisture control films further extend shelf life and prevent freezer burn, enhancing consumer confidence. The European Packaging Federation notes that adoption of advanced barrier materials has reduced product returns due to quality issues by 25% in recent years. Additionally, blockchain-enabled traceability systems allow consumers to verify sourcing and processing conditions, fostering trust in frozen food safety. These technological strides have transformed frozen foods from mere survival staples to desirable culinary choices appealing to health-conscious and quality-driven consumers across Europe.
MARKET RESTRAINTS
Negative Perception Regarding Nutritional Value
Despite scientific evidence supporting the nutritional adequacy of frozen foods, persistent consumer misconceptions regarding their health benefits remain a significant restraint on market growth. Many Europeans associate frozen products with high levels of preservatives, sodium, and artificial additives, believing them to be less healthy than fresh alternatives. A survey conducted by the European Consumer Organisation reveals that 45% of respondents perceive frozen meals as processed and unhealthy, regardless of actual ingredient lists. This stigma is particularly pronounced among older demographics who prioritize traditional cooking methods and fresh ingredients. The European Heart Network highlights concerns about sodium content in ready meals, noting that some frozen dinners contain up to 800 milligrams of salt per serving, which exceeds recommended daily limits for certain individuals. Misinformation spread through social media platforms exacerbates these fears, leading to hesitation among health-conscious shoppers. Although manufacturers have reformulated products to reduce salt, sugar, and fat content, communication gaps prevent these improvements from reaching consumers effectively. Retailers struggle to counteract deep-seated biases through labeling alone, as emotional associations with freshness dominate purchasing decisions. Educational campaigns by industry bodies have had limited impact in shifting public opinion rapidly. Consequently, a substantial segment of the population continues to avoid frozen options despite their convenience and affordability, limiting overall market penetration and forcing companies to invest heavily in rebranding and transparency initiatives to rebuild trust.
High Energy Costs and Operational Expenses
The frozen food industry is inherently energy-intensive, requiring continuous refrigeration throughout production, storage, transportation, and retail display, which makes it highly vulnerable to fluctuating energy prices and negatively impacts regional market growth. The European energy crisis triggered by geopolitical tensions caused electricity and natural gas prices to surge by over 200% in 2022, according to data from the European Commission Energy Directorate. Cold storage facilities operate 24/7, consuming vast amounts of power to maintain temperatures below minus 18 degrees Celsius, which significantly increases operational overheads. The European Cold Chain Federation estimates that energy costs account for 15% to 20% of total logistics expenses for frozen goods, compared to 5% for ambient products. Retailers face similar pressures, with open freezer displays consuming substantial electricity, leading some chains to introduce glass doors or reduce frozen shelf space to cut costs. Small- and medium-sized producers lack the capital to invest in energy-efficient equipment such as variable speed compressors or solar-powered cold stores, forcing them to absorb higher bills or raise prices. Increased consumer prices dampen demand, particularly in price-sensitive markets like Southern and Eastern Europe, where inflation rates exceeded 10% in recent years, as reported by Eurostat. Manufacturers must balance cost recovery with competitiveness, often sacrificing margins to retain market share. Long-term investments in renewable energy and insulation technologies are necessary but require significant upfront capital that many firms cannot afford amidst economic uncertainty.
MARKET OPPORTUNITIES
Expansion of Plant-Based and Vegan Frozen Options
The rising popularity of plant-based diets presents a lucrative opportunity for innovation and growth within the Europe Frozen Food Market. Environmental concerns, ethical considerations, and health motivations drive increasing numbers of Europeans to adopt vegetarian and vegan lifestyles. The European Vegetarian Union reports that the number of vegetarians and vegans in Europe has doubled over the past decade, with Germany, the Netherlands, and the United Kingdom leading this transition. Frozen food manufacturers are responding by launching diverse ranges of plant-based ready meals, burgers, nuggets, and desserts that mimic meat textures and flavors using pea, soy, and wheat proteins. Market analysis by the Good Food Institute indicates that sales of plant-based frozen products grew by 30% year-on-year, outpacing conventional meat categories. Innovations in extrusion and fermentation technologies enable the creation of realistic meat alternatives that appeal to flexitarians who seek to reduce animal product consumption without sacrificing taste. Retailers dedicate prominent shelf space to these items, recognizing their high turnover rates and premium pricing potential. Collaborations between food tech startups and established frozen food brands accelerate product development and market entry. Regulatory support through the European Green Deal encourages sustainable food systems, providing incentives for companies developing low-carbon footprint plant-based options. As consumer awareness of environmental impact grows, demand for convenient, cruelty-free frozen meals will continue to expand, offering substantial revenue opportunities for proactive manufacturers.
Growth of E-Commerce and Direct-to-Consumer Channels
The rapid expansion of online grocery shopping and direct-to-consumer delivery services opens new distribution avenues for frozen food manufacturers, bypassing traditional retail constraints. According to the European E-Commerce Association, online grocery sales in Europe increased by 40% during recent years, with frozen categories showing resilient growth due to improved last-mile logistics. Specialized cold chain delivery networks now enable reliable home delivery of frozen goods, maintaining temperature integrity through insulated packaging and dry ice solutions. Major retailers like Tesco, Carrefour, and Amazon Fresh have invested heavily in automated fulfillment centers equipped with advanced freezing technologies, ensuring product quality upon arrival. Direct-to-consumer brands leverage digital marketing to reach niche audiences, offering subscription boxes of gourmet frozen meals, artisanal ice creams, and specialty ethnic cuisines. Data from Statista indicates that 25% of European households now purchase frozen foods online regularly, citing convenience and wider selection as primary drivers. This channel allows manufacturers to gather detailed consumer data, enabling personalized recommendations and dynamic pricing strategies. Social media integration facilitates viral marketing campaigns targeting younger demographics who prefer digital engagement. Partnerships with food delivery platforms like Deliveroo and Uber Eats expand reach for impulse purchases of frozen snacks and desserts. As logistics efficiency improves and consumer comfort with online frozen shopping grows, this channel will become increasingly vital for market expansion and brand loyalty building.
MARKET CHALLENGES
Supply Chain Disruptions and Raw Material Volatility
Global supply chain instabilities pose significant challenges to the Europe frozen food market, which is affecting the availability and cost consistency of key raw ingredients. Dependence on imported commodities exposes manufacturers to geopolitical risks and trade barriers. The Russian-Ukrainian conflict disrupted grain and sunflower oil supplies, causing price spikes of up to 50% for certain inputs, according to the Food and Agriculture Organization of the United Nations. Labor shortages in agriculture and processing sectors, exacerbated by post-pandemic migration patterns, reduce harvest yields and increase wages, further straining production budgets. The European Logistics Association reports that container shipping delays and port congestion add weeks to lead times, forcing companies to hold larger inventories, which ties up capital and increases storage costs. Climate change-induced extreme weather events damage crop yields in Southern Europe, affecting the availability of tomatoes, peppers, and berries essential for frozen mixed vegetable products. Droughts in Italy and Spain reduced olive oil and vegetable production by 20% in recent seasons, as per national agricultural ministry data. Manufacturers struggle to maintain stable pricing and product formulations amidst such volatility, leading to occasional stockouts and consumer dissatisfaction. Diversifying supplier bases and investing in local sourcing initiatives mitigate risks but require long-term strategic planning and collaboration with farmers. Building resilient supply chains remains a critical priority to ensure uninterrupted product flow and market stability.
Stringent Regulatory Compliance and Labeling Requirements
Navigating complex and evolving regulatory frameworks across European Union member states imposes substantial compliance burdens on frozen food manufacturers, which further challenges the European frozen food market growth. The European Food Safety Authority enforces strict guidelines on food additives, hygiene standards, and nutritional labeling, requiring rigorous documentation and testing protocols. Recent updates to the EU Farm to Fork Strategy mandate clearer origin labeling and sustainability metrics, forcing companies to overhaul packaging and supply chain tracking systems. Compliance with allergen labeling regulations is particularly challenging for frozen ready meals containing multiple ingredients sourced from various suppliers. The European Commission requires declaration of 14 major allergens with zero tolerance for cross-contamination, necessitating dedicated production lines and extensive cleaning procedures that increase operational complexity. Non-compliance risks severe penalties, product recalls, and reputational damage, deterring smaller players from entering the market. Variations in national interpretations of EU laws create additional hurdles for companies operating across borders, requiring localized legal expertise and adaptive packaging designs. The introduction of digital product passports under the Circular Economy Action Plan will soon require detailed environmental impact data for each product, adding another layer of administrative responsibility. Keeping pace with these regulatory changes demands continuous investment in legal counsel, quality assurance teams, and IT systems. Failure to adapt swiftly can result in market exclusion, making regulatory agility a critical competitive factor in the Europe Frozen Food Market.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 4.68% |
| Segments Covered | By Product, End User, and Region |
| Various Analyses Covered | Global, Regional & Country Level Analysis; Segment-Level Analysis; DROC, PESTLE Analysis; Porter’s Five Forces Analysis; Competitive Landscape; Analyst Overview of Investment Opportunities |
| Regions Covered | UK, France, Spain, Germany, Italy, Russia, Sweden, Denmark, Switzerland, Netherlands, Turkey, and Czech Republic |
| Market Leaders Profiled | H.J. Heinz, Nestlé, Maple Leaf Foods Inc., ConAgra Foods Inc., Tyson Foods Inc., General Mills, BRF SA, Pinnacle Foods Inc., Mother Dairy Fruit & Vegetable Pvt. Ltd., Kraft Foods Group Inc., Ajinomoto Co. Inc., and Unilever PLC. |
SEGMENTAL ANALYSIS
By Product Insights
The frozen ready meals segment dominated the market by holding the largest share of the European market in 2025. The dominance of the frozen ready meals segment in the European market is attributed to the intense demand for convenience among time-constrained consumers and the increasing sophistication of culinary offerings. This category encompasses a wide variety of dishes, including pasta, curries, pizzas, and traditional regional specialties that require minimal preparation time. The dominance is primarily fueled by the structural shift in European household dynamics, where dual-income families and single-person households seek efficient meal solutions without compromising on taste or quality. According to Eurostat, over 34% of households in the European Union consist of single occupants who prefer portion-controlled ready meals to minimize food waste and cooking effort. The European Consumer Organisation indicates that 60% of urban consumers prioritize speed in meal preparation, leading to a surge in weekly purchases of frozen entrees. Furthermore, advancements in flash-freezing technology have significantly improved the texture and flavor retention of complex dishes, making them indistinguishable from freshly prepared meals. Retailers have expanded their premium ranges featuring gourmet ingredients and international cuisines, which appeal to adventurous eaters. The availability of healthy options such as low-calorie, high-protein, and organic ready meals has also broadened the consumer base beyond traditional convenience seekers. Major supermarket chains across Germany, France, and the United Kingdom dedicate substantial shelf space to this category, reflecting its high turnover rates and profitability. The integration of ready meals into subscription services and online grocery platforms further cements their market leadership by ensuring consistent accessibility and variety for modern European households.
However, the frozen vegetables and fruits segment is estimated to register a promising CAGR of 7.45 over the forecast period in the European market owing to the rising health consciousness, environmental awareness, and the need to reduce food waste. Consumers are increasingly recognizing that frozen produce retains comparable nutritional value to fresh items while offering greater convenience and longer shelf life. The European Food Safety Authority confirms that freezing locks in vitamins and minerals shortly after harvest, preventing degradation that occurs during transportation and storage of fresh produce. According to the European Commission, approximately 88 million tonnes of food are wasted annually in the EU, with fruits and vegetables accounting for a significant portion due to spoilage. Frozen options eliminate this waste, as they can be stored for months without losing quality. The versatility of frozen fruits and berries in smoothies, baking, and desserts appeals to younger demographics who prioritize healthy snacking. Additionally, the availability of out-of-season produce year-round allows consumers to enjoy diverse diets regardless of climatic constraints. Retailers are expanding their organic frozen produce lines, catering to the growing demand for chemical-free options. The ease of use saves time and water, further appealing to eco-conscious households. As dietary guidelines emphasize increased fruit and vegetable intake, frozen options provide an accessible and affordable way to meet these recommendations, driving robust segment growth.
By End User Insights
The retail segment accounted for the dominant share of the European market in 2025. The growth of the retail segment in the European market is attributed to the widespread availability of frozen products in supermarkets, hypermarkets, and convenience stores across the continent. Household consumption remains the primary driver as Europeans increasingly stock their freezers with a variety of items for daily meals. According to Eurostat, over 75% of households in Western Europe own a freezer appliance, facilitating regular purchases of frozen goods. Major retail chains like Tesco, Carrefour, Aldi, and Lidl have expanded their frozen food aisles, offering extensive ranges from basic staples to premium gourmet items. The convenience of one-stop shopping allows consumers to buy frozen foods alongside other groceries, enhancing basket size. Private label brands offered by retailers have gained significant traction due to their competitive pricing and improving quality, capturing a substantial share of the market. Promotional activities such as multi-buy offers and seasonal discounts further stimulate retail sales. The integration of loyalty programs enables retailers to analyze purchasing patterns and tailor assortments to local preferences. Additionally, the rise of discount supermarkets in countries like Germany and Poland has made frozen foods more accessible to price-sensitive consumers. Retailers also invest in energy-efficient freezer displays to reduce operational costs while maintaining product quality. The strong infrastructure of cold chain logistics ensures consistent stock availability, minimizing out-of-stock situations. As retail continues to be the primary touchpoint for consumers, the segment maintains its leadership through continuous innovation in product assortment, pricing strategies, and customer experience enhancements.
However, the foodservice segment is emerging as the fastest-growing end-user segment in the Europe frozen food market and is estimated to grow at a CAGR of 7.1% over the forecast period owing to the increasing reliance of restaurants, cafes, and institutional caterers on frozen ingredients to ensure consistency, efficiency, and cost control. The post-pandemic recovery of the hospitality sector has led to labor shortages, prompting operators to adopt semi-prepared and fully prepared frozen items to reduce kitchen workload. According to the European Hospitality Association, over 60% of restaurants now use frozen components for sauces, bases, and proteins to streamline operations. Frozen foods offer standardized quality, which is crucial for chain restaurants aiming to deliver uniform customer experiences across multiple locations. The ability to minimize food waste by using exact portions from frozen inventory helps operators manage costs effectively. Additionally, the variety of specialized frozen products, such as artisanal breads, pre-cut vegetables, and gourmet desserts, allows menus to expand without requiring extensive skilled labor. Institutional sectors like schools, hospitals, and corporate canteens are also increasing their use of frozen foods to meet nutritional guidelines and budget constraints. The rise of cloud kitchens and delivery-only concepts further accelerates demand, as these models prioritize speed and efficiency. Suppliers are developing customized solutions for foodservice clients, including bulk packaging and tailored formulations. As the industry evolves towards greater operational efficiency and scalability, the adoption of frozen foods in foodservice is expected to grow rapidly, outpacing retail growth rates.
REGIONAL ANALYSIS
Germany Frozen Food Market Analysis
Germany led the market by capturing 21.2% of the European market share in 2025 due to a strong culture of convenience and high appliance ownership. The country is home to major discount retailers like Aldi and Lidl, which have pioneered the sale of high-quality private label frozen goods. According to the German Federal Statistical Office, over 85% of households possess a freezer, facilitating regular purchases. The busy urban lifestyle in cities like Berlin and Munich drives demand for ready meals and frozen vegetables. German consumers are increasingly health-conscious, leading to growth in organic and plant-based frozen options. The country is also a major producer of frozen potato products and bakery items, exporting significantly to neighboring nations. Regulatory standards for food quality are stringent, ensuring high consumer trust in frozen products. The energy crisis has prompted investments in energy-efficient cold storage and retail displays. Manufacturers focus on sustainability with recyclable packaging and reduced carbon footprints. The mature market sees steady growth driven by innovation in premium segments and convenience formats. The strong industrial base supports advanced freezing technologies, maintaining product quality. As work-life balance remains a priority for Germans, the reliance on frozen foods for quick meals continues to rise. The presence of leading global and local players ensures a competitive landscape with continuous product development. Germany serves as a benchmark for the European market in terms of efficiency and quality standards.

France Frozen Food Market Analysis
France occupies the second-largest share of the European market due to its culinary heritage and growing acceptance of frozen gourmet products. Traditionally focused on fresh ingredients, French consumers are increasingly embracing frozen foods for their convenience and reduced waste. The French Agency for Food, Environmental and Occupational Health and Safety confirms that freezing preserves nutritional value effectively, appealing to health-aware shoppers. Major retailers like Carrefour and Auchan have expanded their premium frozen ranges, featuring French classics such as coq au vin and ratatouille. The rise of single-person households in Paris and other urban centers drives demand for portion-controlled meals. France is a leading producer of frozen vegetables and fruits, leveraging its agricultural strength. The government supports initiatives to reduce food waste, encouraging the use of frozen produce in households and institutions. Artisanal frozen bakeries and patisseries have gained popularity, offering high-quality desserts and breads. The tourism sector contributes to demand, with hotels and restaurants using frozen ingredients for consistency. Regulatory frameworks emphasize clear labeling and origin transparency, building consumer confidence. Innovation in plant-based and organic frozen options is accelerating. The market benefits from a strong cold chain infrastructure ensuring product integrity. As culinary attitudes evolve, France continues to integrate frozen foods into its dining culture, balancing tradition with modern convenience.
UK Frozen Food Market Analysis
The UK holds a notable share of the European market owing to the high convenience orientation and a well-developed retail sector. British consumers are among the highest per capita users of frozen foods in Europe, particularly ready meals and frozen pizzas. Data from the British Frozen Food Federation indicates that 99% of households own a freezer and 80% buy frozen food regularly. The busy lifestyle and long working hours in London and other major cities fuel demand for quick meal solutions. Retailers like Tesco, Sainsbury's, and Iceland have extensive frozen aisles offering diverse options from budget to premium. Iceland, a specialist frozen food retailer, plays a unique role in educating consumers and promoting the benefits of freezing. The UK is a leader in innovation, with many new product launches in healthy and ethical categories. Post-Brexit supply chain adjustments have highlighted the importance of frozen imports for stability. The rise of veganism has spurred growth in plant-based frozen meats and meals. Energy costs have impacted operations, but retailers are investing in efficiency. The market is mature, with strong brand loyalty and high penetration. Consumer education campaigns continue to combat misconceptions about frozen food quality. The UK remains a dynamic market with high consumption levels and continuous innovation in product formats.
Italy Frozen Food Market Analysis
Italy represents a key regional segment in the European market and is characterized by a strong tradition of fresh food but growing adoption of frozen convenience items. Italian consumers are increasingly accepting frozen products, particularly for vegetables, fruits, and ready-to-cook bases like soffritto. The Italian Frozen Food Institute reports that consumption has risen by 15% in recent years as younger generations prioritize time-saving. Major retailers like Coop and Conad have expanded their frozen selections, including regional specialties. The foodservice sector is a significant driver, with restaurants using frozen ingredients for consistency and cost control. Italy is a major exporter of frozen tomato products and mozzarella cheese, leveraging its agricultural expertise. Health consciousness is driving demand for frozen organic vegetables and fruits. The government promotes anti-waste initiatives, encouraging the use of frozen foods to extend shelf life. Urbanization in Milan and Rome increases demand for convenient meal options. Manufacturers focus on high-quality ingredients and traditional recipes to appeal to discerning tastes. The market is growing steadily as cultural barriers diminish. Innovation in gluten-free and lactose-free frozen products caters to specific dietary needs. The cold chain infrastructure is robust, ensuring quality distribution. Italy balances its culinary heritage with modern convenience, driving gradual but steady market expansion.
Spain Frozen Food Market Analysis
Spain is expected to record a healthy CAGR in the European market during the forecast period owing to changing lifestyle patterns and increasing urbanization. Traditionally reliant on fresh markets, Spanish consumers are adopting frozen foods for convenience, especially in major cities like Madrid and Barcelona. The Spanish Federation of Frozen Foods notes that household penetration is rising, with younger demographics leading the trend. Retailers like Mercadona and Carrefour have expanded their frozen ranges, offering affordable and diverse options. The tourism industry drives demand in the foodservice sector, with hotels and restaurants using frozen ingredients for efficiency. Spain is a major producer of frozen vegetables and seafood, exporting significantly to other European countries. Economic factors have made frozen foods attractive for budget-conscious consumers. The warm climate increases the appeal of frozen desserts and beverages. Government initiatives to reduce food waste support the adoption of frozen produce. Innovation in ready meals featuring Mediterranean flavors is gaining traction. The market is less mature than Northern Europe but growing rapidly. Improvements in cold chain logistics enhance product availability. Consumer education is improving perceptions of quality. As work patterns change and dual-income households increase, the demand for convenient frozen solutions is expected to accelerate. Spain presents significant growth potential in the coming years.
COMPETITION OVERVIEW
The Europe Frozen Food Market features intense competition among multinational corporations, regional specialists, and private label retailers striving for dominance. Global giants leverage extensive distribution networks and brand recognition to maintain leadership, while local players compete on authenticity and niche offerings. Price sensitivity drives significant rivalry, particularly in discount segments where private labels challenge established brands with cost-effective alternatives. Innovation in health-conscious and sustainable products serves as a key differentiator, attracting discerning consumers. Regulatory compliance regarding labeling and environmental standards creates barriers to entry, favoring larger entities with robust resources. Supply chain resilience has become crucial amid geopolitical tensions and energy volatility, prompting investments in local sourcing and efficient logistics. Digital engagement through e-commerce and social media enhances brand visibility and customer loyalty. Mergers and acquisitions consolidate market power, enabling economies of scale and broader market reach. The competitive landscape is dynamic, with continuous product launches and promotional activities shaping consumer preferences. Companies must balance cost efficiency with quality and sustainability to succeed in this mature yet evolving market environment across diverse European cultures.
KEY MARKET PLAYERS
A few major players in the Europe frozen food market include
- H.J. Heinz
- Nestlé
- Maple Leaf Foods Inc
- ConAgra Foods Inc
- Tyson Foods Inc
- General Mills
- BRF SA
- Pinnacle Foods Inc
- Mother Dairy Fruit & Vegetable Pvt. Ltd
- Kraft Foods Group Inc
- Ajinomoto Co. Inc
- Unilever PLC
TOP STRATEGIES USED BY KEY MARKET PARTICIPANTS
Key players in the Europe Frozen Food Market employ multifaceted strategies to sustain growth and competitive advantage. Product innovation remains central, with companies launching healthy organic and plant-based options to align with wellness trends. Sustainability initiatives are critical as firms invest in renewable energy, recyclable packaging,g and waste reduction to meet regulatory and consumer demands. Strategic mergers and acquisitions enable expansion into new geographic regions and diversification of product portfolios. Digital transformation enhances supply chain efficiency through data analytics and automation, improving inventory management and logistics. Private label development allows retailers to offer affordable alternatives while maintaining quality standards. Collaborations with local suppliers ensure raw material security and support community economies. Marketing efforts focus on educating consumers about the nutritional benefits and convenience of frozen foods to combat negative perceptions. Pricing strategies adapt to economic fluctuations, ensuring accessibility for diverse consumer segments. These comprehensive approaches drive market penetration and brand loyalty across the region.
LEADING PLAYERS IN THE MARKET
- Nomad Foods stands as a leading independent frozen food company in Europe specializing in pizza and appetizers under brands like Dr Oetker Pizza and Birds Eye. The company focuses on sustainable sourcing and innovative product development to meet evolving consumer preferences for convenience and quality. Recent actions include significant investments in renewable energy across its manufacturing facilities to reduce its carbon footprint and enhance operational efficiency. Nomad has expanded its portfolio through strategic acquisitions of regional brands, strengthening its presence in key markets like Italy and the United Kingdom. The company actively promotes plant-based options and recyclable packaging, aligning with European sustainability goals. By leveraging advanced freezing technologies and maintaining strong relationships with major retailers, Nomad Foods ensures consistent product availability and high customer satisfaction. Its commitment to corporate social responsibility and continuous innovation solidifies its position as a dominant force in the European frozen food landscape, driving growth through ethical practices and superior product offerings.
- Aryzta is a prominent player in the Europe frozen food market known for its diverse portfolio of private label and branded products, including vegetables, fruits, and ready meals. The company emphasizes operational excellence and supply chain efficiency to deliver high-quality products at competitive prices. Recent initiatives involve expanding production capacity in Eastern Europe to capitalize on growing demand and lower manufacturing costs. Aryzta has invested heavily in digital transformation, optimizing inventory management and logistics through artificial intelligence and data analytics. The company prioritizes sustainability by implementing water conservation techniques and reducing plastic usage in packaging. Strategic partnerships with local farmers ensure a steady supply of fresh raw materials, supporting rural economies. Aryzta also focuses on health-conscious innovations, introducing low-salt and organic ranges to cater to changing dietary trends. These efforts enhance brand loyalty and market reach, positioning Aryzta as a reliable partner for retailers and consumers seeking value and quality in frozen food solutions across the continent.
- Froneri International operates as a major joint venture between Nestlé and PAI Partners, focusing exclusively on ice cream and frozen desserts in Europe. The company manages iconic brands such as Häagen-Dazs, Mövenpick, and Nestlé Ice Cream, delivering premium experiences to consumers. Recent strategies include expanding distribution networks in emerging European markets and enhancing direct-to-consumer capabilities through e-commerce platforms. Froneri invests in sustainable dairy sourcing and eco-friendly packaging materials to address environmental concerns. The company leverages global research and development resources to introduce innovative flavors and textures appealing to diverse palates. Marketing campaigns emphasize indulgence and quality, strengthening emotional connections with customers. Froneri also optimizes its manufacturing footprint by consolidating production sites for greater efficiency and reduced emissions. By balancing global brand power with local market insights, Froneri International maintains a strong competitive edge, driving growth through product excellence and sustainable business practices in the dynamic European frozen dessert sector.
DETAILED SEGMENTATION OF EUROPE FROZEN FOOD MARKET INCLUDED IN THIS REPORT
This research report on the Europe frozen food market has been segmented and sub-segmented based on product, distribution channel & region.
By Product
- Frozen Ready Meals
- Frozen Fruits & Vegetables
- Frozen Meat & Poultry
- Frozen Seafood
- Frozen Bakery Products
- Frozen Dairy Products
- Others
By End User
- Supermarkets/Hypermarkets
- Convenience Stores
- Online Retail
- Specialty Stores
- Others
By Region
- UK
- France
- Spain
- Germany
- Italy
- Russia
- Sweden
- Denmark
- Switzerland
- Netherlands
- Turkey
- Czech Republic
- Rest of Europe