- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$24.93 BnMarket Estimate, 2026
$27.48 BnMarket Forecast, 2034
$59.81 BnCAGR, 2026–2034
10.21%Executive Summary: Global Brown Sugar Market
- Market Scope: Comprehensive global market analysis of brown sugar covering product types, application areas, distribution channels, and regional dynamics across the food and beverage industry.
- Market Valuation: Valued at USD 24.93 billion in 2025, estimated at USD 27.48 billion in 2026, and projected to reach USD 59.81 billion by 2034, registering an exponential CAGR of 10.21% from 2026 to 2034.
- Primary Growth Drivers: Rapid expansion of the urban food and beverage industry; increasing demand for energy and fruit-flavored drinks; growing consumer interest in luxury baked goods; and the superior hygroscopic/flavor-enhancing properties of molasses content in brown sugar for bakery manufacturing.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment / Position | Fastest-Growing Segment |
|---|---|---|
| By Type | Light Brown Sugar (standardized for household and commercial use) | Dark Brown Sugar (high molasses content variants) |
| By Application | Bakery (principal consumer segment due to hygroscopic properties) | Beverages (energy/fruit-based) & Confectionery |
| By Distribution Channel | Hypermarkets & Supermarkets (major retail footprint) | Convenience & Specialty Stores |
| By Region | Asia-Pacific (dominates global production and consumption in tropical climates) | Europe & North America |
Major Market Players & Market Structure
Market Structure: A consolidated yet globally expanding market driven by major international sugar processors (e.g., Tereos, Wilmar International, Mitr Phol) focusing on regional production capacity expansion and strategic industry acquisitions.
Key Companies: AkzoNobel NV, Masco Corporation, Domino Sugar, Hempel A/S, Axalta Coating Systems Ltd, Jotun A/S, Imperial Sugar, The Valspar Corporation, Nippon Paint Holding Co. Ltd, BASF SE, Ragus AG, and PPG Industries Inc.
 Download Free Sample Report
Global Brown Sugar Market Size
The global brown sugar market size was valued at USD 24.93 billion in 2025 and is projected to reach USD 59.81 billion by 2034 from USD 27.48 billion in 2026, growing at a CAGR of 10.21%.
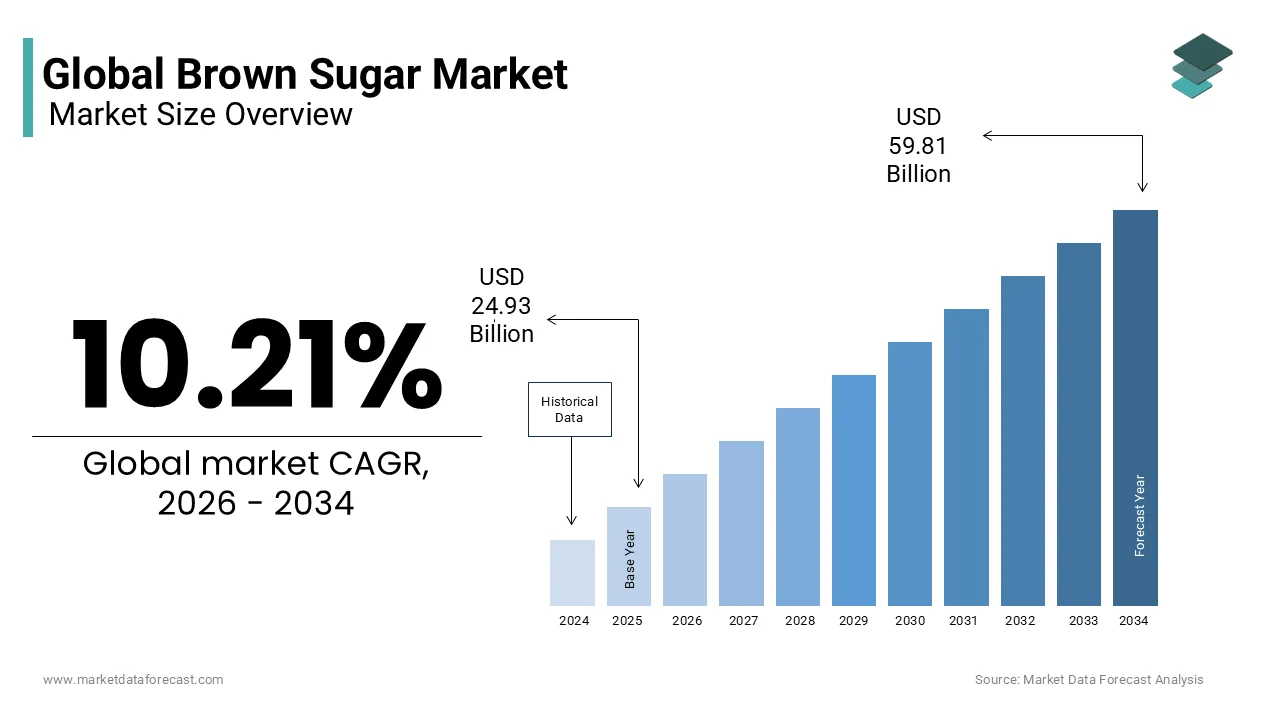
The brown sugar is unrefined or partially refined sucrose crystals that retain molasses content offering distinct flavor profiles and nutritional perceptions compared to white sugar. According to the study, global sugar production reached 180 million metric tons in the recent harvest season reflecting the massive scale of the underlying agricultural sector. The retention of molasses in brown sugar provides trace minerals such as , potassium, and iron, which differentiates it from fully refined alternatives. As per the World Health Organization, excessive sugar consumption remains a primary driver of obesity and diabetes with over 422 million people worldwide living with diabetes. This health context influences consumer choices towards perceived natural sweeteners like brown sugar despite similar caloric content. According to the Food and Agriculture Organization of the United Nations, sugarcane cultivation occupies approximately 26 million hectares globally with the extensive land use associated with this crop.
MARKET DRIVERS
Rising Preference for Natural and Minimally Processed Ingredients
The rising preference for natural and minimally processed ingredients, significantly bolsters the growth of the brown sugar market. Consumers are increasingly scrutinizing ingredient lists and avoiding highly refined additives, which drives demand for brown sugar as a perceived wholesome alternative. The trend is particularly strong in North America and Europe, where health consciousness is high. As per the Journal of Nutrition Education and Behavior studies, consumers associate brown color in sugar with higher nutrient content and less processing although the nutritional difference is marginal. This perception drives premiumization in the baking and confectionery sectors. Furthermore, the growth of home baking during recent years has sustained demand for high quality baking ingredients. The sales of specialty baking ingredients, including brown sugar have remained robust due to sustained consumer interest in homemade goods. Manufacturers are responding by launching organic and non-GMO certified brown sugar variants to capture this discerning segment.
Expansion of the Artisanal Bakery and Confectionery Sector
The expansion of the artisanal bakery and confectionery sector is creating specialized demand for premium sweeteners with unique flavor profiles, which is also propelling the growth of the brown sugar market. Artisanal bakers and chocolatiers prefer brown sugar for its ability to enhance moisture texture and depth of flavor in products such as cookies, cakes, and gourmet chocolates. Brown sugar is essential in these formulations because its molasses content interacts with leavening agents to produce desirable textures. Additionally, the rise of craft chocolate makers who experiment with unconventional pairings often utilize brown sugar to complement dark chocolate notes. The innovation in flavor combinations is a key trend driving product development. These niche but influential segments value consistency and quality over price sensitivity.
MARKET RESTRAINTS
Health Concerns and Sugar Reduction Initiatives
The health concerns and government led sugar reduction initiatives, primarily discouraging excessive consumption of all forms of added sugars, which is restricting the growth of the brown sugar market. Despite its natural image, brown sugar is chemically similar to white sugar and contributes to the same health risks when consumed in excess. According to the World Health Organization, recommendations suggest limiting free sugar intake to less than 10% of total energy intake to prevent noncommunicable diseases. Many governments have implemented sugar taxes and labeling requirements that affect all sugary products including those using brown sugar. As per the Centers for Disease Control and Prevention, more than 40% of adults in the United States are obese, which has intensified public health campaigns against sugar consumption. These campaigns often do not distinguish between types of sugar leading to a general decline in usage. Furthermore, food manufacturers are reformulating products to reduce overall sugar content replacing it with low calorie sweeteners or fruit purees. Consumer education about the glycemic index also leads some individuals to avoid brown sugar in favor of alternative sweeteners.
Volatility in Raw Material Prices and Supply Chain Disruptions
The volatility in raw material prices and supply chain disruptions are impeding the growth of the brown sugar market. Brown sugar is derived from sugarcane or sugar beets, which are subject to weather conditions pest outbreaks and geopolitical factors that affect yield and pricing. These fluctuations make it difficult for manufacturers to maintain stable pricing for end consumers. As per the Food and Agriculture Organization of the United Nations, climate change is expected to increase the frequency of extreme weather events, impacting agricultural productivity. This long-term threat adds risk to supply chain planning. Furthermore, logistical challenges such as port congestion and fuel cost increases raise the cost of transporting bulk sugar. The freight rates have remained elevated affecting the profitability of imported sugar. Small and medium sized buyers are particularly vulnerable to these cost pressures as they lack the bargaining power of large multinational corporations.
MARKET OPPORTUNITIES
Innovation in Functional and Fortified Sweeteners
The innovation in functional and fortified sweeteners by allowing manufacturers to differentiate their products through added health benefits is fuelling the growth of the brown sugar market. Companies are exploring ways to enrich brown sugar with vitamins minerals or prebiotics to appeal to health-conscious consumers, who still desire sweetness. Fortified brown sugar can position itself as a functional ingredient rather than just a sweetener. The advancements in microencapsulation technology allow for the stable incorporation of sensitive nutrients into sugar crystals without affecting taste or texture. This technical capability opens new application areas in infant nutrition and dietary supplements. Furthermore, the trend towards personalized nutrition encourages the development of specialized sugar blends tailored to specific dietary needs such as low glycemic or high fiber options. Collaborations with research institutions can further validate health claims and build consumer trust.
Growth in Organic and Sustainable Certification Segments
The growth in organic and sustainable certification by tapping into the ethical consumption trend that is also to enhance the growth of the brown sugar market. Consumers are increasingly willing to pay a premium for products that are certified organic fair trade or sustainably sourced. Brown sugar produced under organic standards avoids synthetic pesticides and fertilizers, which appeals to environmentally conscious buyers. Brands that obtain these certifications can access premium retail channels and build strong brand loyalty. Furthermore, corporate sustainability goals drive large food manufacturers to source responsibly certified ingredients to meet their environmental social and governance targets. Companies with strong sustainability credentials enjoy better brand reputation and customer retention. Additionally, the transparency provided by blockchain technology in supply chains enhances trust in certification claims. This traceability allows consumers to verify the origin and practices behind their brown sugar.
MARKET CHALLENGES
Regulatory Pressure on Labeling and Health Claims
The regulatory pressure on labeling and health claims are major factors to impede the growth of the brown sugar market. Authorities are cracking down on misleading claims that suggest brown sugar is significantly healthier than white sugar due to its mineral content. The strict guidelines govern nutrition and health claims to prevent consumer deception. This means manufacturers cannot explicitly promote brown sugar as a nutritious alternative without rigorous scientific substantiation. As per the Federal Trade Commission in the United States advertising must be truthful and not misleading which limits marketing angles that rely on naturalness implies health. This regulatory scrutiny forces companies to invest in legal compliance and reformulate messaging. Furthermore, mandatory front of pack labeling systems in countries like Chile and Mexico warn consumers about high sugar content regardless of the type. Such measures dampen consumer enthusiasm for brown sugar based products. Additionally, varying regulations across different areas complicate global branding strategies for multinational companies.
Competition from Alternative Natural Sweeteners
The competition from alternative natural sweeteners poses, as consumers explore diverse options for reducing refined sugar intake is a another factor to degrade the growth of the brown sugar market. Sweeteners such as honey maple syrup, agave nectar, and coconut sugar are gaining popularity due to their unique flavors and perceived health advantages. These alternatives often carry stronger health halos than brown sugar, which is still viewed as a form of sucrose. The maple syrup sales have grown steadily driven by its antioxidant content and natural origin. Coconut sugar is another direct competitor with a lower glycemic index, which appeals to diabetic consumers. Additionally, the rise of zero calorie natural sweeteners like stevia and monk fruit offers a guilt free option for those strictly monitoring calorie intake. The International Stevia Council states that stevia usage in food and beverages has doubled in the last five years.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 10.21% |
| Segments Covered | By Type, Application, Distribution Channel, and Region. |
| Various Analyses Covered | Global, Regional and Country Level Analysis; Segment-Level Analysis; DROC; PESTLE Analysis; Porter’s Five Forces Analysis; Competitive Landscape; Analyst Overview of Investment Opportunities |
| Regions Covered | North America, Europe, APAC, Latin America, Middle East & Africa |
| Market Leaders Profiled | AkzoNobel NV, Masco Corporation, Domino Sugar, Hempel A/S, Axalta Coating Systems Ltd, Jotun A/S, Imperial Sugar, The Valspar Corporation, Nippon Paint Holding Co. Ltd, BASF SE, Ragus AG, and PPG Industries Inc. |
SEGMENTAL ANALYSIS
By Type Insights
The light brown sugar segment was the largest by accounting for 44.9% of the brown sugar market share in 2025 due to its versatility and mild flavor profile, which appeals to a broad range of culinary applications. Its widespread acceptance in household cooking also contributes to its market leadership as consumers find it suitable for everyday sweetening needs. The consistency in crystal size and moisture content makes it ideal for industrial food processing where standardization is critical. Furthermore, major food manufacturers prefer light brown sugar for mass produced items such as breakfast cereals and granola bars due to its uniform browning characteristics. The light brown sugar offers optimal water activity control, which extends the shelf life of baked products.
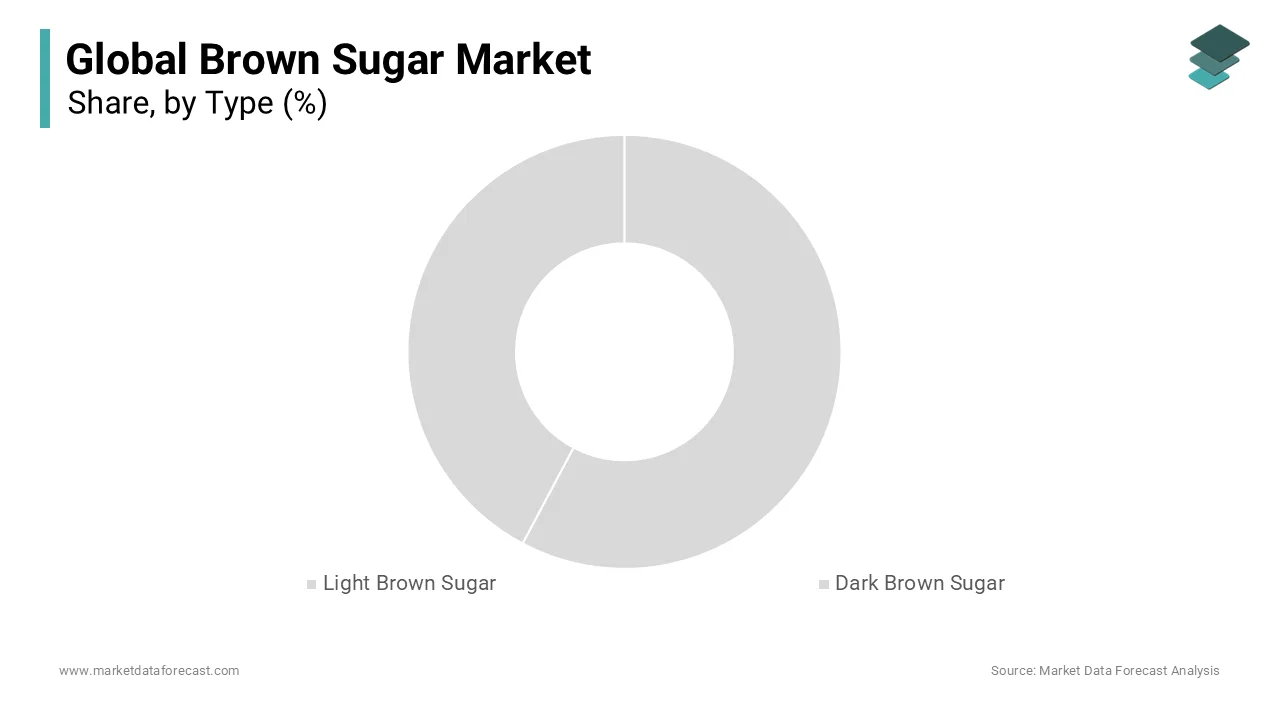
The dark brown sugar segment is expected to grow at a fastest CAGR of 5.8% during the forecast period with the rising demand for intense flavor profiles in gourmet and artisanal food products. Dark brown sugar contains a higher concentration of molasses, which imparts a robust caramel taste and deeper color that is increasingly favored by chefs and premium brands. This trend is particularly evident in the craft chocolate and premium cookie sectors where depth of flavor is a key differentiator. The growing popularity of Caribbean and Latin American cuisines, which traditionally utilize dark sugars also boosts demand. Furthermore, health-conscious consumers perceive dark brown sugar as having higher mineral content due to the increased molasses presence although the difference is marginal. Manufacturers are responding by launching organic and single origin dark brown sugar variants to cater to this niche but rapidly expanding segment.
By Application Insights
The bakery segment was accounted in holding a dominant share of the brown sugar market in 2025 with the essential ingredient for achieving desired texture moisture and flavor in a wide array of baked goods. Its hygroscopic nature helps retain moisture in cakes cookies and breads ensuring a soft and chewy consistency that consumers prefer. The versatility of brown sugar allows it to be used in both sweet and savory baked items making it indispensable for commercial bakeries. Brown sugar also contributes to the Maillard reaction, which creates appealing golden brown crusts and complex flavors in baked products. The sales of baking supplies, including brown sugar remain consistently high as consumers continue to engage in homemade food preparation. Additionally, the expansion of the artisanal bakery sector, which emphasizes quality ingredients supports steady demand for premium brown sugar varieties.
The beverages segment is likely to grow at a fastest CAGR of 6.2% from 2026 to 2034 with the innovation in ready to drink teas and specialty coffee formulations. Brown sugar adds a distinct caramel note and richness to beverages that white sugar cannot replicate, making it a popular choice for premium drink brands. The bubble tea phenomenon which originated in Asia and spread globally relies heavily on brown sugar syrup for its signature flavor and visual appeal. As per the International Coffee Organization, specialty coffee shops are increasingly offering brown sugar as a premium sweetener option to differentiate their menus. This trend is supported by the growing preference for natural and less processed ingredients in drinks. Furthermore, the development of brown sugar infused energy drinks and functional beverages opens new avenues for market expansion. The Institute of Food Technologists states that brown sugar syrups provide better stability and mouthfeel in cold beverages compared to granulated forms.
By Distribution Channel Insights
The hypermarkets and supermarkets segment held a significant share of the Brown Sugar Market in 2025 due to their extensive reach wide product assortment and ability to offer competitive pricing. These large retail formats serve as the primary shopping destination for households purchasing bulk grocery items, including staples like brown sugar. The one stop shopping convenience attracts a large volume of consumers, who prefer to buy all their kitchen essentials in a single trip. Hypermarkets also leverage their bargaining power to negotiate lower prices from suppliers, which translates to cost savings for consumers. Furthermore, these retailers invest in prominent shelf placements and promotional campaigns that drive impulse purchases. The established logistics networks of hypermarkets ensure consistent stock availability, reducing the risk of out of stock situations.
The specialty stores segment is esteemed to register a fastest CAGR of 7.5% from 2026 to 2034 with the increasing consumer demand for organic fair trade and artisanal sugar varieties. Specialty stores focus on curated selections of high quality and ethically sourced products, which appeal to discerning shoppers willing to pay a premium. These stores often carry niche brown sugar brands that are not available in mainstream supermarkets such as single origin or unrefined variants. Specialty stores also foster community engagement through workshops and tasting events which educate consumers about the benefits of different sugar types. This educational approach builds brand loyalty and encourages trial of premium products. Furthermore, the rise of boutique grocery chains in urban areas provides additional distribution points for specialized brown sugar products. The National Association of Specialty Food Trade states that specialty retailers are key drivers of innovation in the food sector.
REGIONAL ANALYSIS
North America Brown Sugar Market Analysis
North America was the largest contributor in the brown sugar market by holding 56.4% of the share in 2025 with the high consumption rates and a well-established retail infrastructure. The presence of major food manufacturing hubs also supports steady industrial demand. As per the study, the commercial bakery sector continues to expand introducing new products that utilize brown sugar for its functional properties. Consumer preference for clean label ingredients has led to increased demand for organic and non-GMO certified brown sugar variants. Furthermore, the influence of social media and cooking shows has revitalized interest in baking among younger demographics. This cultural engagement sustains demand, despite health concerns. Regulatory frameworks regarding labeling and health claims are strict but clear providing a stable operating environment for manufacturers.
Europe Brown Sugar Market Analysis
Europe brown sugar market held next with 23.4% of the share in 2025 with the diverse culinary traditions and stringent regulatory standards regarding sugar consumption. The popularity of artisanal baking and the growing trend towards sustainable and ethically sourced ingredients. Consumers in countries like France, Germany, and the United Kingdom prefer high quality brown sugar for pastries and confectionery. The artisanal bakery sector is robust contributing to steady demand for premium brown sugar varieties. The rise of veganism and plant-based diets has also boosted the use of brown sugar as a natural sweetener in alternative desserts. The Vegan Society reports that the number of vegans in Europe has doubled in the last five years driving demand for compliant ingredients. Furthermore, fair trade certification is highly valued by European consumers who prioritize ethical sourcing. Fairtrade International states that Europe accounts for the majority of global fair trade sugar sales.
Asia Pacific Brown Sugar Market Analysis
Asia Pacific brown sugar market growth is anticipated to grow at a fastest CAGR in coming years with the urbanization, rising disposable incomes, and the expansion of the food and beverage industry. The proliferation of bubble tea shops cafes and bakeries, which extensively use brown sugar for its distinctive flavor. The middle class in the region is expanding rapidly leading to increased spending on dining out and premium food products. The cultural affinity for sweet treats and the influence of Western baking trends also support demand. Furthermore, the local production of sugarcane in countries like Thailand and India ensures adequate supply and competitive pricing. The International Sugar Organization notes that Asia is a major producer of raw sugar which facilitates the manufacture of brown sugar. E-commerce platforms are playing a crucial role in distributing specialty brown sugar products to remote areas.
Latin America Brown Sugar Market Analysis
Latin America brown sugar growth is propelled with the major producer of sugarcane and a region with deep cultural ties to traditional sweeteners. The local consumption patterns, where brown sugar known as panela or rapadura is a staple in households and traditional recipes. The small scale producers contribute significantly to the regional supply of unrefined brown sugar. This decentralized production supports rural economies and ensures widespread availability. The export potential is also significant as demand for natural and organic sweeteners grows in North America and Europe. Fair trade initiatives help local farmers access international markets at premium prices. The culinary tourism is a growing segment in the region.
Middle East and Africa Brown Sugar Market Analysis
The Middle East and Africa brown sugar market growth is driven by urbanization and the gradual adoption of international culinary trends. According to the study, economic growth in several African countries is leading to increased consumption of processed and packaged foods. Brown sugar is increasingly used in hotels cafes and bakeries catering to tourists and expatriates. The hospitality industry in the Middle East is investing heavily in diverse menu offerings, including Western style desserts that require brown sugar. Import dependence is high in many countries, which makes the market sensitive to global price fluctuations. However, local production of sugarcane in countries like Egypt and Sudan provides some domestic supply. The Food and Agriculture Organization of the United Nations highlights efforts to improve agricultural productivity in the region which could boost local sugar processing. Rising health awareness is also influencing consumer choices towards natural sweeteners.
COMPETITIVE LANDSCAPE
The competition in the Brown Sugar Market is characterized by a mix of established multinational corporations and regional producers vying for market share through quality and innovation. Major players leverage their extensive distribution networks and brand recognition to dominate retail shelves while smaller niche brands focus on organic and artisanal segments. Regulatory pressures regarding sugar consumption and labeling requirements add complexity to the competitive landscape forcing companies to adapt quickly. Innovation in packaging and sustainable sourcing practices serves as a key differentiator for brands seeking to attract environmentally conscious consumers. The rise of private label products from large retailers also intensifies competition by offering lower priced alternatives. Strategic collaborations with food manufacturers and bakeries help suppliers secure steady demand and reduce volatility.
KEY MARKET PLAYERS
Some of the key players in global brown sugar market are
- AkzoNobel NV
- Masco Corporation
- Domino Sugar
- Hempel A/S
- Axalta Coating Systems Ltd
- Jotun A/S
- Imperial Sugar
- The Valspar Corporation
- Nippon Paint Holding Co. Ltd
- BASF SE
- Ragus AG
- PPG Industries Inc
Top Players in the Market
- Domino Sugar is a prominent player in the North American brown sugar market known for its high quality and consistent product offerings. The company contributes significantly by supplying both retail and industrial customers with premium light and dark brown sugar variants. Recent actions include upgrading its refining facilities to enhance production efficiency and reduce environmental impact. Domino has also launched new packaging solutions that improve shelf life and convenience for consumers. The company actively engages in community outreach programs to build brand loyalty and trust.
- Imperial Sugar operates as a key manufacturer and distributor of brown sugar products serving a wide range of culinary and industrial applications. The company is involved in producing specialty sugars that cater to the needs of artisanal bakers and large-scale food processors. Recent initiatives, include expanding its distribution network to reach more regional areas and enhance product availability. Imperial Sugar has invested in sustainable sourcing practices to ensure the long term viability of its supply chain. The company also collaborates with chefs and food influencers to promote innovative uses of brown sugar in modern recipes. These efforts help Imperial Sugar maintain a strong brand presence and appeal to diverse consumer segments.
- Ragus AG is a leading European producer of specialty sugars, including high quality brown sugar for the confectionery and bakery sectors. The company contributes to the market by providing customized sugar solutions that meet specific technical requirements for texture and flavor. Recent actions involve investing in research and development to create novel sugar blends with enhanced functional properties. Ragus AG has also strengthened its partnerships with major food manufacturers to secure long term supply contracts. The company emphasizes transparency and traceability in its sourcing processes to align with consumer demand for ethical products.
Top Strategies Used by Key Market Participants
Key players in the Brown Sugar Market, primarily employ product differentiation and sustainable sourcing strategies to strengthen their competitive position. Companies are increasingly launching organic and fair trade certified brown sugar variants to appeal to health conscious and ethically minded consumers. This approach helps brands command premium prices and build loyalty among discerning shoppers. Another major strategy involves investing in advanced processing technologies to improve product consistency and reduce environmental impact. Manufacturers are also forming strategic partnerships with local farmers to secure stable raw material supplies and support community development. Digital marketing campaigns highlighting the versatility and natural qualities of brown sugar are widely used to engage consumers. Additionally, companies are expanding their distribution channels through e commerce platforms to reach broader audiences.
MARKET SEGMENTATION
This research report on the global brown sugar market has been segmented and sub-segmented based on type, application, distribution channel & region.
By Type
- Light Brown Sugar
- Dark Brown Sugar
By Application
- Bakery
- Confectionary
- Ice-Creams
- Beverages
By Distribution Channel
- Hypermarkets and Supermarkets
- Convenience Stores
- Retailers
- Specialty Stores
By Region
- North America
- Asia Pacific
- Europe
- Latin America
- Middle East and Africa